
Advertisement
Here's What Analysts Are Forecasting For Lime Technologies AB (publ) (STO:LIME) After Its First-Quarter Results
Investors in Lime Technologies AB (publ) (STO:LIME) had a good week, as its shares rose 3.1% to close at kr378 following the release of its quarterly results. The result was positive overall - although revenues of kr188m were in line with what the analysts predicted, Lime Technologies surprised by delivering a statutory profit of kr2.09 per share, modestly greater than expected. The analysts typically update their forecasts at each earnings report, and we can judge from their estimates whether their view of the company has changed or if there are any new concerns to be aware of. With this in mind, we've gathered the latest statutory forecasts to see what the analysts are expecting for next year.
We check all companies for important risks. See what we found for Lime Technologies in our free report.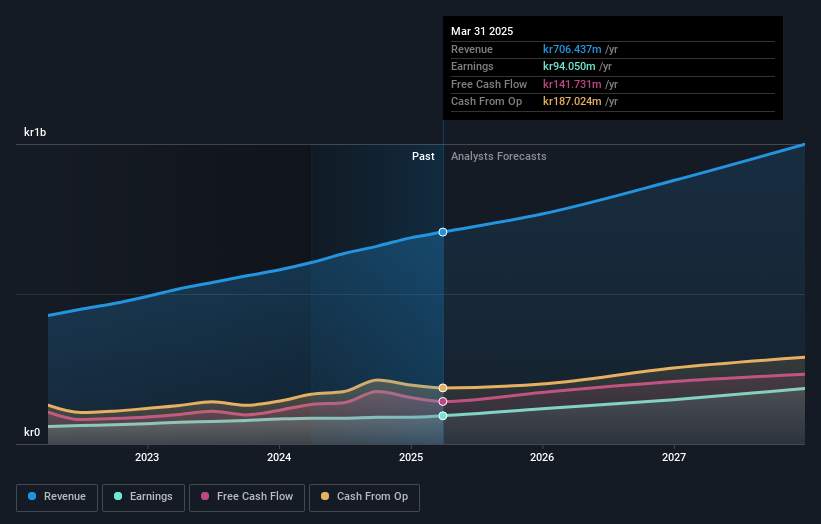
After the latest results, the five analysts covering Lime Technologies are now predicting revenues of kr766.4m in 2025. If met, this would reflect a decent 8.5% improvement in revenue compared to the last 12 months. Per-share earnings are expected to shoot up 25% to kr8.83. In the lead-up to this report, the analysts had been modelling revenues of kr774.8m and earnings per share (EPS) of kr8.92 in 2025. The consensus analysts don't seem to have seen anything in these results that would have changed their view on the business, given there's been no major change to their estimates.
Check out our latest analysis for Lime Technologies
The analysts reconfirmed their price target of kr389, showing that the business is executing well and in line with expectations. It could also be instructive to look at the range of analyst estimates, to evaluate how different the outlier opinions are from the mean. The most optimistic Lime Technologies analyst has a price target of kr416 per share, while the most pessimistic values it at kr355. The narrow spread of estimates could suggest that the business' future is relatively easy to value, or thatthe analysts have a strong view on its prospects.
Looking at the bigger picture now, one of the ways we can make sense of these forecasts is to see how they measure up against both past performance and industry growth estimates. It's pretty clear that there is an expectation that Lime Technologies' revenue growth will slow down substantially, with revenues to the end of 2025 expected to display 11% growth on an annualised basis. This is compared to a historical growth rate of 17% over the past five years. Compare this against other companies (with analyst forecasts) in the industry, which are in aggregate expected to see revenue growth of 15% annually. So it's pretty clear that, while revenue growth is expected to slow down, the wider industry is also expected to grow faster than Lime Technologies.
The Bottom Line
The most important thing to take away is that there's been no major change in sentiment, with the analysts reconfirming that the business is performing in line with their previous earnings per share estimates. Fortunately, the analysts also reconfirmed their revenue estimates, suggesting that it's tracking in line with expectations. Although our data does suggest that Lime Technologies' revenue is expected to perform worse than the wider industry. The consensus price target held steady at kr389, with the latest estimates not enough to have an impact on their price targets.
Keeping that in mind, we still think that the longer term trajectory of the business is much more important for investors to consider. We have estimates - from multiple Lime Technologies analysts - going out to 2027, and you can see them free on our platform here.
It might also be worth considering whether Lime Technologies' debt load is appropriate, using our debt analysis tools on the Simply Wall St platform, here.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
When oil spikes, crude gets the attention. I think the boring refiner in the middle is where it gets interesting, and a record shows why.
78
marcus_reid
It's cyclical, but there's a hedging case. Worth being precise about it though. Refiners buy crude and sell products, so a crude spike alone hurts them. In 2008 oil hit 147 and refining margins collapsed. What they hedge is a product supply shock, not an oil one. This is what is happening now.
steve_investor
Goldman says the supply response has already started. Higher utilisation, yields shifted to diesel.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About OM:LIME
Lime Technologies
Lime Technologies AB (publ) software as a service (SaaS) based customer relationship management (CRM) solutions in the Nordic region.
Outstanding track record with reasonable growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.574.9% undervalued
54 followersusers have followed this narrative
1 commentusers have commented on this narrative
12 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17019.6% undervalued
35 followersusers have followed this narrative
2 commentsusers have commented on this narrative
7 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.8% undervalued
25 followersusers have followed this narrative
1 commentusers have commented on this narrative
12 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.3% undervalued
10 followersusers have followed this narrative
4 commentsusers have commented on this narrative
5 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Boab Metals ·
Boab Metals, Sorby Hills Project $411M NPV at $27 Silver, Imagine $150–$200 Silver
Fair Value:AU$11.6996.2% undervalued
9 followersusers have followed this narrative
4 commentsusers have commented on this narrative
1 likeusers have liked this narrative
RE

RecMag on Agfa-Gevaert ·
Agfa-Gevaert is a digital and materials turnaround opportunity, with growth potential in ZIRFON, but carrying legacy risks.
Fair Value:€5.3991.6% undervalued
29 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RE

RecMag on Proximus ·
Proximus The Amplify Reset, State-Backed, Debt-Disciplined, and Building Toward €400M FCF by 2030
Fair Value:€821.6% undervalued
41 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28019.9% undervalued
374 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k72.6% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9118.3% overvalued
219 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
