
Advertisement
- United States
- /
- Semiconductors
- /
- NasdaqGS:NVDA
Assessing Nvidia (NVDA) Valuation After Recent Pullback And Conflicting Fair Value Signals
Recent performance snapshot
NVIDIA (NVDA) has seen mixed share performance recently, with the stock down 6.2% over the past day, down 2.9% over the past week, and down 3.0% over the past month, while still up 15.3% over the past 3 months.
See our latest analysis for NVIDIA.
The recent pullback, with the latest share price at US$205.10 and short term share price returns softening, contrasts with very strong 1 year and multi year total shareholder returns. This points to investors still pricing in significant AI infrastructure potential and risk.
If NVIDIA has you thinking about where else AI demand could flow, it may be worth scanning other potential beneficiaries using our screener for 48 AI infrastructure stocks
With NVIDIA now at US$205.10 after a strong multi year run, revenue of US$253.5b and net income of US$159.6b, should you view temporary weakness as a potential opening, or assume markets are already pricing in future growth?
Most Popular Narrative: 39.7% Undervalued
At a last close of $205.10 versus a narrative fair value of $339.90, the most followed view on NVIDIA points to a large gap between market price and projected potential.
Nvidia will hit $400b annual revenue in 5 years time. ~90% of revenue will come from data centre customers. This equates to $90b / quarter, or equivalent to 30,000 Blackwell racks (at ~$3m per rack).
Curious how that revenue outlook feeds into the fair value? The narrative leans on aggressive data center demand, rich margins and a premium earnings multiple. The exact mix might surprise you.
Result: Fair Value of $339.90 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, this hinges on NVIDIA maintaining AI software dominance and premium pricing power, while avoiding regulatory or geopolitical shocks that could curb data center demand.
Wall Street's queuing for one rocket. While SpaceX counts down to its IPO, other companies tied to the new space race are already in orbit. → 20 Compelling Space Companies watchlist · Global Space Race Investing Ideas screener · Scan the sector by valuation on Rocket Lab's valuation page.
Another view: cash flows paint a tighter picture
While the most followed narrative points to a fair value of $339.90, our DCF model points to a future cash flow value of $188.98, which sits below the current $205.10 share price and implies NVIDIA is trading above that estimate.
This gap between narrative driven upside and the SWS DCF model’s more cautious output raises a simple question for you: which set of assumptions feels closer to how NVIDIA might actually convert AI demand into long term cash flows, and how much valuation risk are you comfortable carrying?
Look into how the SWS DCF model arrives at its fair value.
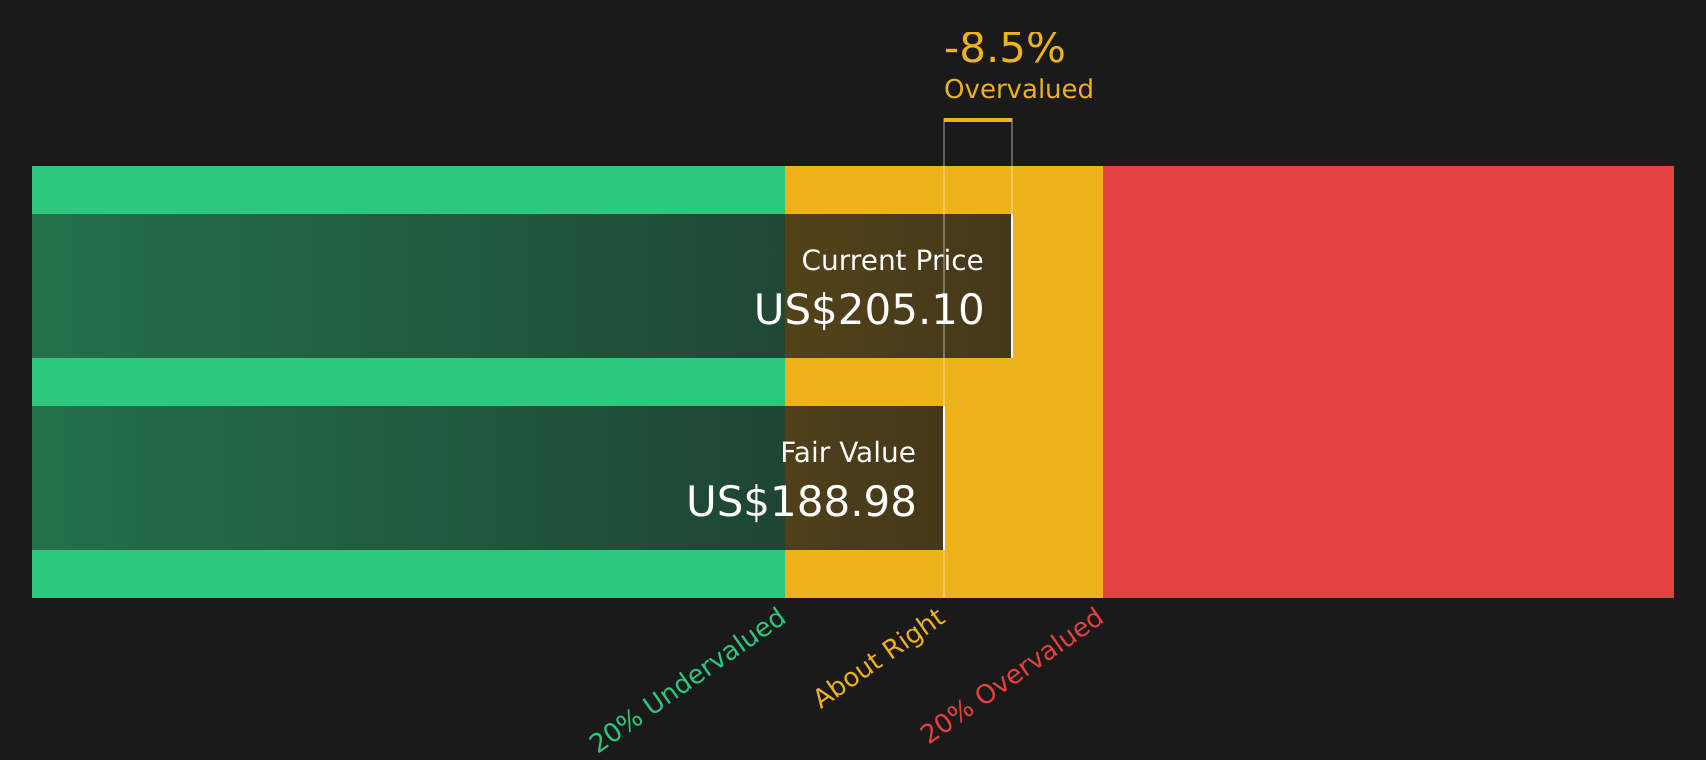
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NVIDIA for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 49 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly split between upside potential and valuation risk, it makes sense to check the underlying data yourself and move quickly to shape your own view by weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas?
If NVIDIA is already on your radar, do not stop there. Broader opportunities could be sitting in plain sight, and skipping them might cost you future options.
- Spot potential bargains before the crowd by scanning companies our models flag as strong value candidates using the 49 high quality undervalued stocks.
- Strengthen your income game by checking out companies offering robust yields and payout profiles through the 9 dividend fortresses.
- Prioritise resilience by focusing on companies with healthier finances and lower risk scores via the 64 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if NVIDIA might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Is Nvidia actually expensive at 32 times earnings? I think that number can melt faster than people realise.
1
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?

Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
32
About NasdaqGS:NVDA
NVIDIA
Operates as a data center scale AI infrastructure company in the United States, Taiwan, China, Hong Kong, Europe, and internationally.
Exceptional growth potential with flawless balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
69 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
49 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
41 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Benz Mining ·
Benz Mining, From 510 koz Historical Resource to 10 Moz Target: Can Glenburgh Actually Convert?
Fair Value:CA$6.2835.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HU

Hunter_Z on Teamstar Berhad ·
Teamstar Berhad's Profits Soar with 13.0% PE Growth in 2026
Fair Value:RM 0.765.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AN


andrei9868 on Intuit ·
Intuit’s Big Bets Are Working — and the Market Is Still Pricing the Old Story
Fair Value:US$50028.5% undervalued
0 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
357 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
205 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
231 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


