Advertisement
- United States
- /
- Hospitality
- /
- NasdaqGS:TCOM
Trip.com Group (TCOM) Stock May Be Undervalued After A 48% Fall
SI

Reviewed by Bailey Pemberton
Trip.com Group has had a rough stretch in 2026, with the share price sharply lower year to date even as the broader valuation checks currently lean on the cheap side. The stock’s recent slide raises a clear question for investors who follow Trip.com Group closely, because the market is pricing in a lot of pessimism while several valuation indicators suggest the business may be discounted.
- Year to date, Trip.com Group is down 47.6%, which signals that sentiment around the stock has weakened significantly.
- Trip.com Group’s long term value will likely hinge on how consistently it can convert its travel demand into cash flow. Any renewed pressure on travel activity or sustained cost inflation may drag on profitability and investor confidence.
- The broader checks lean cheap, with Trip.com Group screening as undervalued on multiple metrics and earning a value score of 6 out of 6 in recent analysis.
The stock’s next move may depend on whether this steep share price decline has already more than accounted for the risks facing Trip.com Group or whether the current discount still overstates the downside.
Capitalize on the reset in Trip.com Group by lining it up against other potentially mispriced opportunities in our curated list of 32 high quality undervalued stocks.Is Trip.com Group Still Cheap on Earnings?
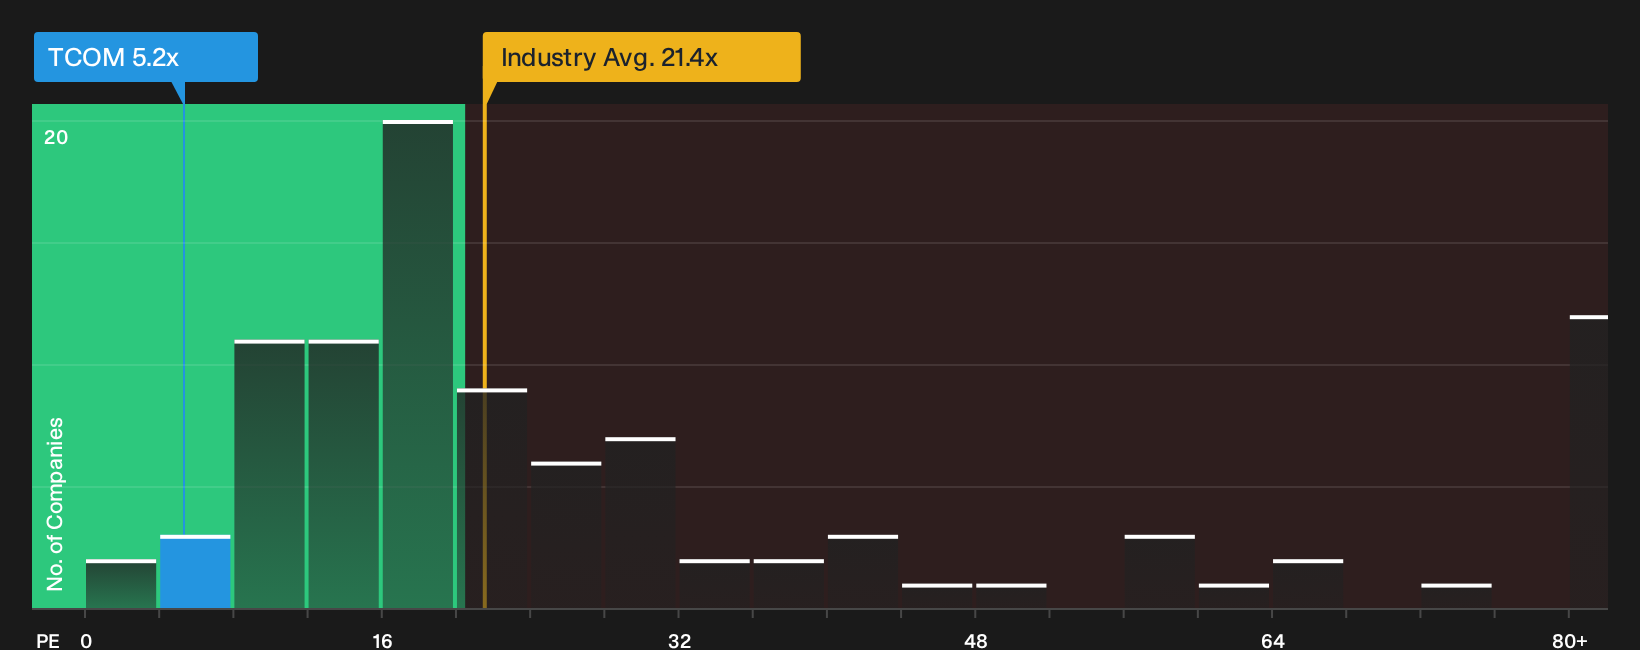
The P/E ratio is a useful shorthand here because Trip.com Group has positive earnings that can be compared directly with peers in the hospitality space. On this yardstick, the stock trades on about 5.2x earnings, which is well below the broader hospitality industry average of roughly 21.4x and also below peer companies that cluster around 18.1x.
A more tailored check that adjusts for Trip.com Group’s growth profile, margins, size and risk points to a fair P/E of about 13.6x. That is higher than the current 5.2x level, which indicates that the market is assigning a steep discount to the business relative to what this framework suggests might be reasonable for its earnings power.
On this P/E measure, Trip.com Group stock appears undervalued compared with both its fair multiple and sector benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
The Trip.com Group Narrative: What Would Justify Today's Price?
Trip.com Group’s valuation gap sets up a natural question that Narratives try to answer for you, because they spell out which paths for growth, profitability and earnings would need to play out for the current share price to look clearly too low or too high. Each narrative links its number to a specific view on where Trip.com Group's revenue trajectory, margin profile and risk balance could head next, giving you a reference point you can revisit as fresh information comes in.
One of the top community narratives on Trip.com Group: 35% undervalued
"Ongoing investment in proprietary artificial intelligence, personalized recommendation engines, and integrated one-stop trip planning tools is driving higher user engagement, stronger repeat bookings, and better operating leverage…"
Read one of the top narratives on Trip.com Group
Do you think there's more to the story for Trip.com Group? Head over to our Community to see what others are saying!
The Bottom Line
Trip.com Group screens as undervalued on earnings-based checks, with market multiples implying a discount to both tailored fair-value estimates and sector peers. That kind of gap only closes if investors gain more confidence that cash generation and profitability can hold up against any pressure on travel demand or costs. The key question is whether the current markdown is compensation for those risks or an overreaction that leaves mispricing on the table. Your view on the durability of Trip.com Group’s booking volumes and margin profile is what really decides the call from here.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Trip.com Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
The US closed a loophole that helped Temu and Shein. Does that put local retailers back on a level playing field?
78
Jake_Merritt
The domestic retailers competing most directly with Temu and Shein are themselves among the largest importers in the country.
a
arjun_dyig0
Zooming out and looking at the effect of these regulatory changes last year, US manufacturing - production is at a seven year high. But employment is down. It's is interesting,
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
13
About NasdaqGS:TCOM
Trip.com Group
Through its subsidiaries, operates as a travel service provider for accommodation reservation, transportation ticketing, packaged tours, in-destination, corporate travel management, and other travel-related services in China and internationally.
Very undervalued with flawless balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2541.0% undervalued
189 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4938.9% undervalued
42 followersusers have followed this narrative
2 commentsusers have commented on this narrative
13 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k16.9% undervalued
30 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2537.2% undervalued
11 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
AN


andre_santos on Realty Income ·
Realty Income - A Fundamental and Historical Valuation
Fair Value:US$62.114.2% undervalued
90 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RO


RockeTeller on Manuka Resources ·
Manuka Resources Just Restarted Gold, Silver Hits Q4 with $805M NPV vs $152M Cap
Fair Value:AU$4.7998.6% undervalued
11 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
TI

TimLee on Pentech Holdings Berhad ·
Why Pentech Stands Out After 2QFY26
Fair Value:RM 0.5334.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1426 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8920.9% undervalued
1609 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.5% undervalued
1632 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion
CO


Constantin_Mar on Platform Group SE KGaA ·
Quite a lot of speculation presented as if it were evidence.You are combining alleged payment disputes, alleged bank actions, legal disputes with journalists and other unverified claims to imply that TPG’s financial reporting is somehow unreliable or that the company is approaching insolvency. That’s a very serious conclusion, but the evidence you’ve presented doesn’t establish it.TPG’s financial statements, share count, debt, cash flow and acquisitions can all be checked against official filings and corporate documents. That’s called due diligence. Repeating allegations and then pointing to a low P/E doesn’t prove anything.In fact, the P/E below 1 is precisely the reason the underlying numbers need to be investigated rather than dismissed. If you have documentary evidence that TPG’s reported figures are false, that banks actually cancelled the alleged facilities, or that the company is insolvent, publish the documents and numbers.Otherwise, this reads less like analysis and more like an attempt to create fear and selling pressure around a micro-cap stock.Claims require evidence. Allegations are not evidence.
1
|0

