
Advertisement
- India
- /
- Trade Distributors
- /
- NSEI:CNL
Key Things To Consider Before Buying Creative Peripherals and Distribution Limited (NSE:CREATIVE) For Its Dividend
Dividend paying stocks like Creative Peripherals and Distribution Limited (NSE:CREATIVE) tend to be popular with investors, and for good reason - some research suggests a significant amount of all stock market returns come from reinvested dividends. Yet sometimes, investors buy a popular dividend stock because of its yield, and then lose money if the company's dividend doesn't live up to expectations.
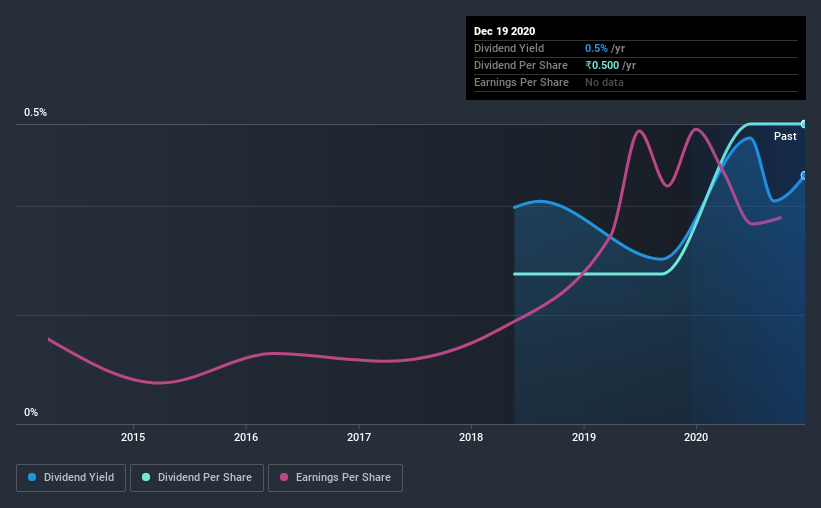
Some readers mightn't know much about Creative Peripherals and Distribution's 0.5% dividend, as it has only been paying distributions for the last three years. A low dividend might not be a bad thing, if the company is reinvesting heavily and growing its sales and profits. There are a few simple ways to reduce the risks of buying Creative Peripherals and Distribution for its dividend, and we'll go through these below.
Click the interactive chart for our full dividend analysis
Payout ratios
Dividends are usually paid out of company earnings. If a company is paying more than it earns, then the dividend might become unsustainable - hardly an ideal situation. So we need to form a view on if a company's dividend is sustainable, relative to its net profit after tax. Creative Peripherals and Distribution paid out 9.1% of its profit as dividends, over the trailing twelve month period. We like this low payout ratio, because it implies the dividend is well covered and leaves ample opportunity for reinvestment.
Another important check we do is to see if the free cash flow generated is sufficient to pay the dividend. Unfortunately, while Creative Peripherals and Distribution pays a dividend, it also reported negative free cash flow last year. While there may be a good reason for this, it's not ideal from a dividend perspective.
Consider getting our latest analysis on Creative Peripherals and Distribution's financial position here.
Dividend Volatility
One of the major risks of relying on dividend income, is the potential for a company to struggle financially and cut its dividend. Not only is your income cut, but the value of your investment declines as well - nasty. The dividend has not fluctuated much, but with a relatively short payment history, we can't be sure this is sustainable across a full market cycle. During the past three-year period, the first annual payment was ₹0.3 in 2017, compared to ₹0.5 last year. This works out to be a compound annual growth rate (CAGR) of approximately 26% a year over that time.
We're not overly excited about the relatively short history of dividend payments, however the dividend is growing at a nice rate and we might take a closer look.
Dividend Growth Potential
While dividend payments have been relatively reliable, it would also be nice if earnings per share (EPS) were growing, as this is essential to maintaining the dividend's purchasing power over the long term. Strong earnings per share (EPS) growth might encourage our interest in the company despite fluctuating dividends, which is why it's great to see Creative Peripherals and Distribution has grown its earnings per share at 24% per annum over the past five years. The company is only paying out a fraction of its earnings as dividends, and in the past been able to use the retained earnings to grow its profits rapidly - an ideal combination.
Conclusion
To summarise, shareholders should always check that Creative Peripherals and Distribution's dividends are affordable, that its dividend payments are relatively stable, and that it has decent prospects for growing its earnings and dividend. Firstly, the company has a conservative payout ratio, although we'd note that its cashflow in the past year was substantially lower than its reported profit. Next, earnings growth has been good, but unfortunately the company has not been paying dividends as long as we'd like. In sum, we find it hard to get excited about Creative Peripherals and Distribution from a dividend perspective. It's not that we think it's a bad business; just that there are other companies that perform better on these criteria.
Companies possessing a stable dividend policy will likely enjoy greater investor interest than those suffering from a more inconsistent approach. Still, investors need to consider a host of other factors, apart from dividend payments, when analysing a company. Case in point: We've spotted 3 warning signs for Creative Peripherals and Distribution (of which 1 is potentially serious!) you should know about.
If you are a dividend investor, you might also want to look at our curated list of dividend stocks yielding above 3%.
If you’re looking to trade Creative Peripherals and Distribution, open an account with the lowest-cost* platform trusted by professionals, Interactive Brokers. Their clients from over 200 countries and territories trade stocks, options, futures, forex, bonds and funds worldwide from a single integrated account. Promoted
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
*Interactive Brokers Rated Lowest Cost Broker by StockBrokers.com Annual Online Review 2020
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
810
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
74
About NSEI:CNL
Creative Newtech
Distributes information technology (IT), gaming, imaging, and lifestyle products in India and internationally.
Proven track record with mediocre balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CL


Clive_Thompson on Upside Gold ·
Upside Gold - New Technical Report Expected in Q1 2027 Could Re-Rate The Stock.
Fair Value:CA$1.552.7% undervalued
3 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8829.7% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.8% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8532.0% undervalued
25 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
KA

KASHIF_RIAZ_ on MCB Bank ·
MCB Bank: high-quality income anchor — 9% yield, cheap earnings, modest upside
Fair Value:PK₨45011.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
EP

Epstein_Research on Honey Badger Silver ·
Honey Badger Silver Delivers strong PEA, market likes it!
Fair Value:CA$260.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
KA

KASHIF_RIAZ_ on Service Long March Tyres ·
SLM: Pakistan's radial-tyre import-substitution play, fairly valued near listing price
Fair Value:PK₨258.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.6% undervalued
1490 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8918.3% undervalued
1649 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.4% undervalued
1664 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative


