Advertisement
- United States
- /
- Software
- /
- NasdaqGS:NTNX
Can Expanded Azure Virtual Desktop Support Deepen Nutanix’s (NTNX) Hybrid Cloud Advantage?
SI

Reviewed by Sasha Jovanovic
- At Microsoft Ignite 2025, Nutanix announced that its Nutanix Cloud Platform will support Microsoft Azure Virtual Desktop for hybrid environments, enabling organizations to run Azure Virtual Desktop on premises using the Nutanix AHV hypervisor.
- This collaboration brings enhanced flexibility and regulatory compliance for industries handling sensitive data, reinforcing Nutanix’s commitment to advancing hybrid cloud solutions.
- We'll explore how Nutanix's expanded Azure Virtual Desktop support could further strengthen its multi-cloud positioning within the investment narrative.
We've found 14 US stocks that are forecast to pay a dividend yield of over 6% next year. See the full list for free.
Nutanix Investment Narrative Recap
To be a Nutanix shareholder, you need to believe in the increasing adoption of hybrid and multi-cloud environments and the company's potential to expand its enterprise infrastructure footprint. The announcement of Azure Virtual Desktop support on Nutanix AHV strengthens its cloud partnerships but does not materially change the current short-term catalyst, capturing more hybrid cloud market share, or the largest risk, which remains intensifying competition from public cloud vendors.
Among recent announcements, Nutanix’s updated earnings guidance for fiscal 2026 is particularly relevant. Management forecasts revenue between US$2.82 billion and US$2.86 billion for the year, reflecting confidence in ongoing enterprise demand and the effects of strategic partnerships, which serve as core drivers behind the company’s near-term growth catalysts.
However, investors should be mindful that despite the enhanced Azure integration, pricing pressure from established IT vendors and cloud providers remains an important risk ...
Read the full narrative on Nutanix (it's free!)
Nutanix's narrative projects $3.9 billion in revenue and $513.0 million in earnings by 2028. This requires 15.3% yearly revenue growth and a $324.6 million earnings increase from the current earnings of $188.4 million.
Uncover how Nutanix's forecasts yield a $85.78 fair value, a 82% upside to its current price.
Exploring Other Perspectives
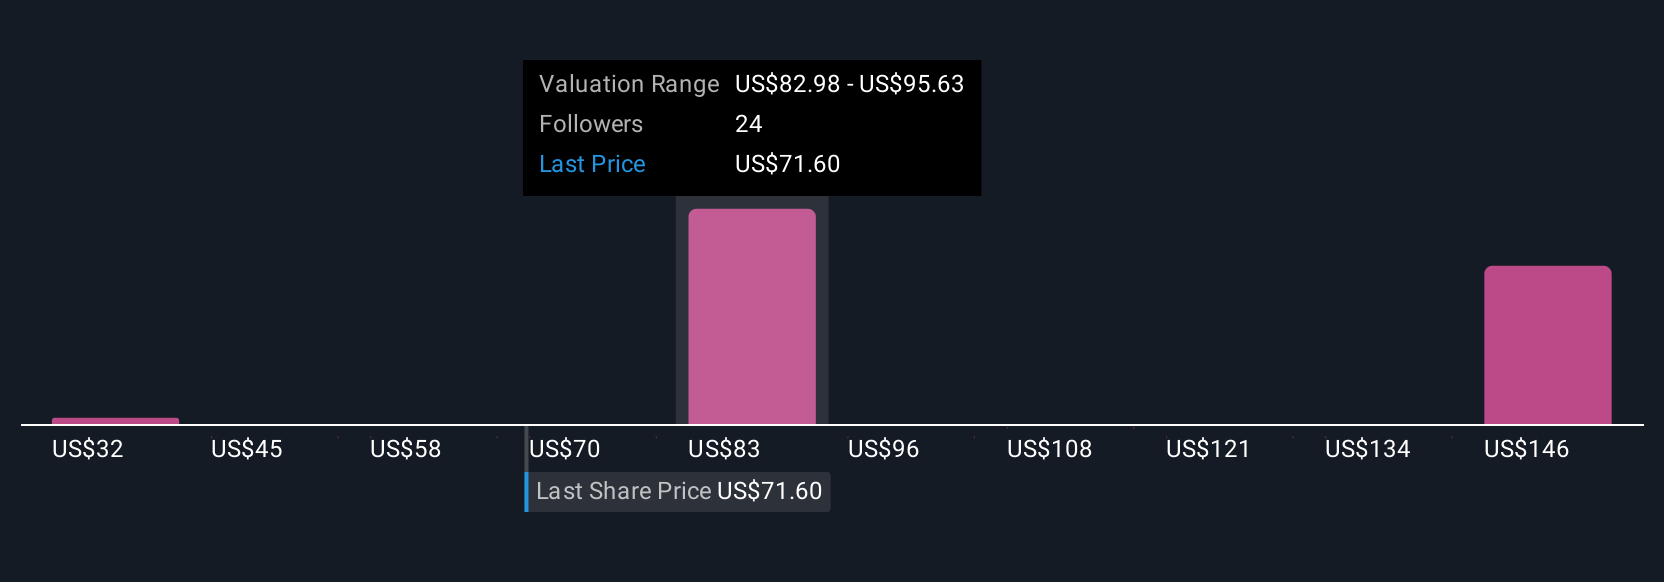
Simply Wall St Community members provided eight fair value estimates for Nutanix, ranging from US$32.34 to US$118.13 per share. While many see potential in hybrid and multi-cloud catalysts, significant differences in opinion reflect how views on competition and future growth can shape your outlook.
Explore 8 other fair value estimates on Nutanix - why the stock might be worth over 2x more than the current price!
Build Your Own Nutanix Narrative
Disagree with existing narratives? Create your own in under 3 minutes - extraordinary investment returns rarely come from following the herd.
- A great starting point for your Nutanix research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- Our free Nutanix research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Nutanix's overall financial health at a glance.
No Opportunity In Nutanix?
Markets shift fast. These stocks won't stay hidden for long. Get the list while it matters:
- The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 25 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
- These 11 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Nutanix might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
A landmark settlement is meant to punish Meta (META). If the 1998 tobacco deal is any guide, it might protect it.
108
ZO
zoe_vi5fn
Any moat with an opt-out clause for your competitors is just a fence around your own garden.
CO
connor_iwn1g
Worth looking at what previous legal action actually did to Meta rather than reaching for tobacco. The FTC's record five billion dollar privacy fine in 2019 was met with the stock rising, because it came in below fears and removed an open question. GDPR was designed to constrain large platforms and increased their share of the European ad market, because compliance cost fell hardest on small intermediaries. The FTC's antitrust case, the one that could genuinely have broken the company up, was decided in Meta's favour last November. The only thing that ever meaningfully hurt the business was Apple changing a tracking default, and Meta out-spent that too, while the ad-tech firms that could not afford to rebuild disappeared. The pattern is not that Meta survives regulation. It is that regulation keeps costing its smaller competitors more.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
10
About NasdaqGS:NTNX
Nutanix
Provides an enterprise cloud platform in North America, Europe, the Asia Pacific, the Middle East, Latin America, and Africa.
Flawless balance sheet with solid track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5861.4% undervalued
59 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.1% undervalued
62 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11632.1% undervalued
12 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Santacruz Silver Mining ·
Santacruz Silver, 5.6M Oz Silver Producer Trading at Low Multiples, 100X Per-Share Upside in $200 Silver
Fair Value:CA$142.990.7% undervalued
96 followersusers have followed this narrative
14 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Eaton ·
"Grid-to-Chip: How Eaton Controls the Physical Bottlenecks of AI Data Centers"
Fair Value:US$517.0622.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
QU


QuanD on NVIDIA ·
Nvidia Isn’t Cisco. And It’s Still Cheap
Fair Value:US$359.2239.4% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS

oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28022.3% undervalued
365 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9122.3% overvalued
213 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0943.9% undervalued
240 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative
Trending Discussion

DA

david_8pjjo on Axon Enterprise ·
One factor to consider for Axon's growth is whether the Russia - Ukraine war continues. Axon's Dedrone (dead drone) product could be a game changer, however if it is too successful, it could lead to an end of the war, thereby reducing Dedrone sales - an unintended consequence!David Lane
0
|0
