Advertisement
- United States
- /
- IT
- /
- NasdaqGS:FSLY
Is Fastly (FSLY) Pricing Look Rational After Prolonged Share Price Declines
SI

Reviewed by Bailey Pemberton
- If you are wondering whether Fastly's current share price reflects its real worth, you are not alone. This article will walk through what the numbers actually say about the stock.
- Fastly's shares last closed at US$8.57, with returns of a 7.4% decline over 7 days, an 18.6% decline over 30 days, a 15.9% decline year to date, a 15.3% decline over 1 year, a 13.2% decline over 3 years and a 91.6% decline over 5 years. These moves may have changed how investors think about its potential and risk.
- Recent attention on Fastly has been shaped more by its broader business developments and industry sentiment than by any one event, with investors weighing how its content delivery and edge computing services fit into long term digital infrastructure trends. This context is important when thinking about whether the current price reflects what the business could reasonably be worth.
- Fastly currently has a valuation score of 2 out of 6, which means it screens as undervalued on 2 of the 6 valuation checks we will walk through next. We will also look at an even more complete way to think about value at the end of the article.
Fastly scores just 2/6 on our valuation checks. See what other red flags we found in the full valuation breakdown.
Approach 1: Fastly Discounted Cash Flow (DCF) Analysis
A Discounted Cash Flow, or DCF, model takes estimates of the cash a company could generate in the future and discounts those back to today to arrive at an estimate of what the business might be worth right now.
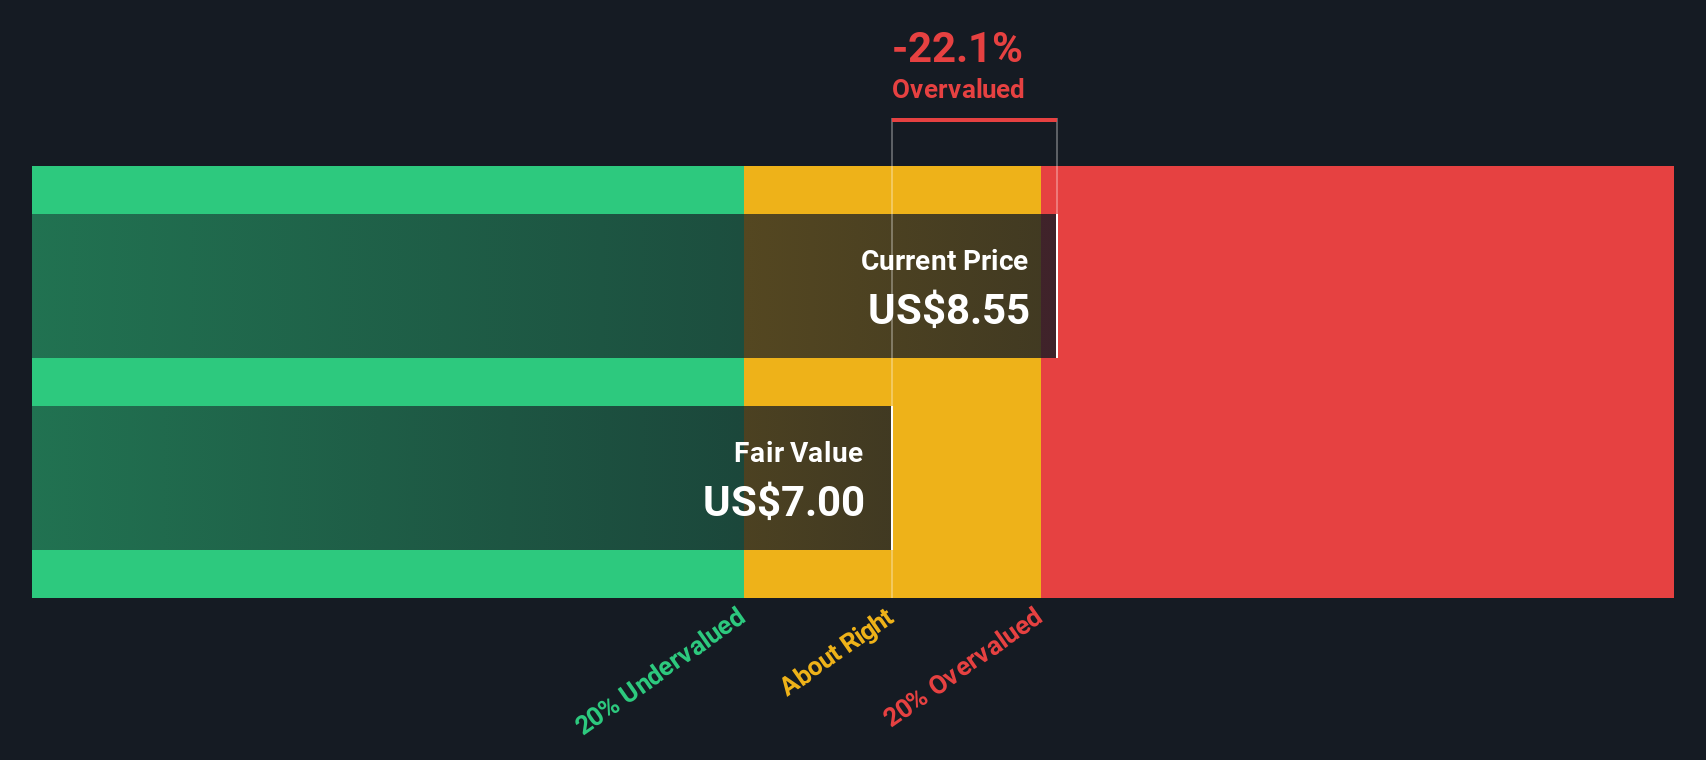
For Fastly, the model used is a 2 Stage Free Cash Flow to Equity approach. The latest twelve month free cash flow is about $31.29 million. Analysts provide free cash flow estimates out to 2027, with Simply Wall St then extending those cash flows further using its own assumptions. The ten year projections show discounted free cash flows each year, ending with a discounted figure of about $28.62 million in 2035.
Pulling all those discounted cash flows together gives an estimated intrinsic value of around $5.43 per share. Compared with the recent share price of US$8.57, the model implies Fastly is about 57.9% overvalued on this DCF view.
Result: OVERVALUED
Our Discounted Cash Flow (DCF) analysis suggests Fastly may be overvalued by 57.9%. Discover 53 high quality undervalued stocks or create your own screener to find better value opportunities.
Approach 2: Fastly Price vs Sales
For companies where earnings are limited or volatile, the P/S ratio is often a useful way to think about value because it compares what investors pay for each dollar of revenue instead of profits that can swing around.
Growth expectations and risk both matter here. Higher expected growth or lower perceived risk can justify a higher P/S multiple, while slower expected growth or higher uncertainty tend to support a lower, more conservative range.
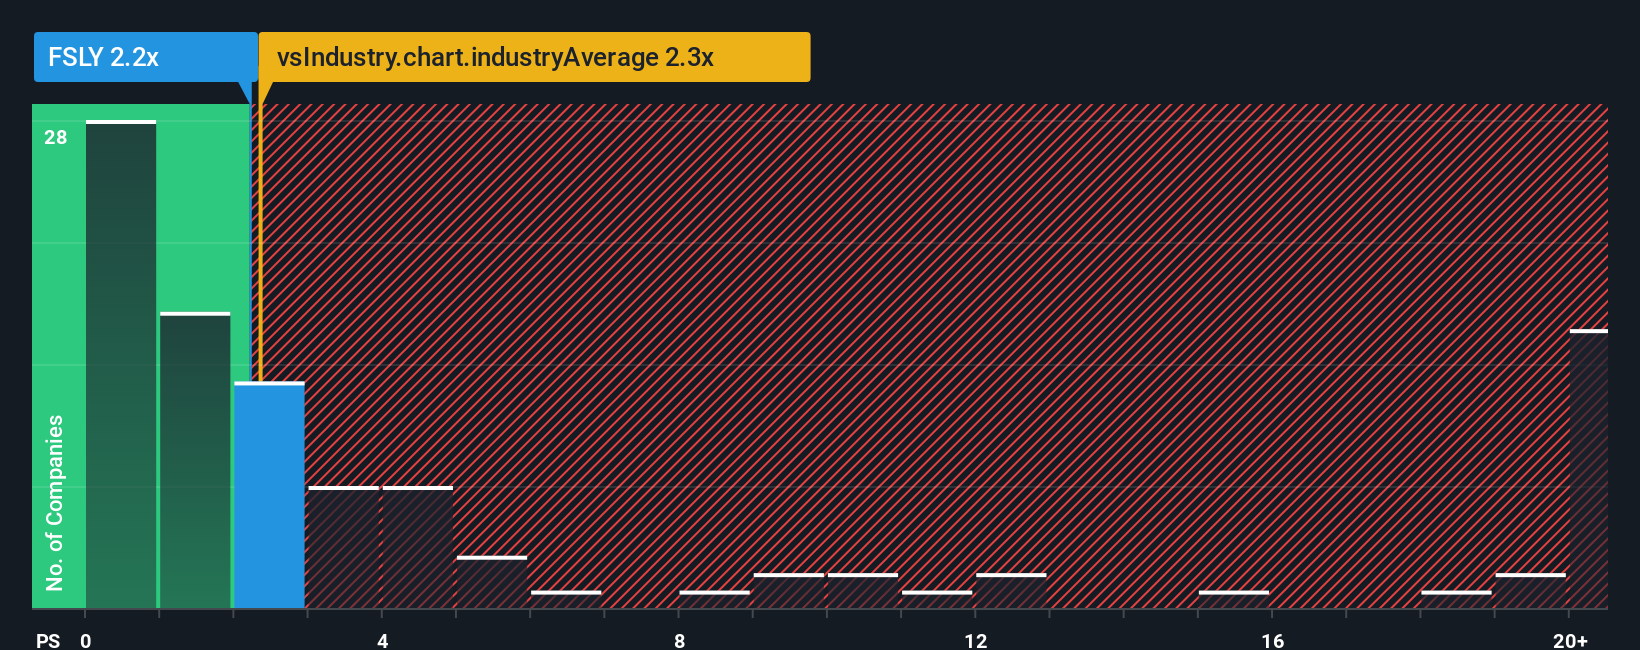
Fastly currently trades on a P/S ratio of 2.16x. That sits close to the wider IT industry average of 2.02x and below the peer group average of 4.42x. Simply Wall St also provides a proprietary “Fair Ratio” for Fastly of 2.37x, which reflects factors such as the company’s growth profile, profit margins, industry, size and key risks, rather than just a simple comparison with industry or peers.
This Fair Ratio can be more tailored than a straight peer or sector check, because it ties the multiple to company specific characteristics instead of assuming that all IT names deserve similar pricing.
Comparing Fastly’s current 2.16x P/S to the 2.37x Fair Ratio suggests the shares screen as undervalued on this metric.
Result: UNDERVALUED
P/S ratios tell one story, but what if the real opportunity lies elsewhere? Start investing in legacies, not executives. Discover our 22 top founder-led companies.
Upgrade Your Decision Making: Choose your Fastly Narrative
Earlier we mentioned that there is an even better way to understand valuation. Let us introduce you to Narratives, which are simply your own story about a company, tied directly to numbers like fair value, future revenue, earnings and margins.
On Simply Wall St, Narratives live in the Community page and give you a clear link between Fastly’s business story, a forecast you are comfortable with and the fair value that drops out of those assumptions.
You can then compare that fair value to the current share price to help decide whether you think Fastly looks attractive, fully priced or expensive based on your view, instead of relying only on headline multiples.
The powerful part is that Narratives update as new information such as earnings or news is added to the platform. This means your view on Fastly can stay current without you rebuilding your forecast from scratch.
For example, one Fastly Narrative on the Community page might assume a relatively high fair value based on optimistic revenue growth and improving margins. Another Narrative might point to a lower fair value built on more conservative growth and profitability assumptions.
Do you think there's more to the story for Fastly? Head over to our Community to see what others are saying!

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Is Nvidia actually expensive at 32 times earnings? I think that number can melt faster than people realise.
76
MA
marcus_l38oa
Why would I fret over Nvidia results now? I think it's moment has gone. I will invert and see what companies can be the next Nvidia.
SE
sean_3pk06
Multiple has already melted 50 percent in the last year. It can melt another 50 percent from here in the next year?
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?

Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
32
About NasdaqGS:FSLY
Fastly
Operates an edge cloud platform for processing, serving, and securing its customer’s applications in the United States, the Asia Pacific, Europe, and internationally.
Flawless balance sheet with low risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
69 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
49 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
41 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
11 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
HU

Hunter_Z on Sorento Capital Berhad ·
Sorento Capital 季报回顾:盈利能力显著提升下的稳健前行
Fair Value:RM 0.7513.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HU

Hunter_Z on Swift Energy Technology Berhad ·
Swift Energy’s 3Q Profit Triples as Order Book Hits RM173mil
Fair Value:RM 0.548.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HU

Hunter_Z on Enest Group Berhad ·
Enest Group Berhad: Q2 Profit at RM1.24 Million as Group Eyes Expansion Opportunities
Fair Value:RM 0.250.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
357 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
205 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
231 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


