
Advertisement
- United States
- /
- Aerospace & Defense
- /
- NYSE:CRS
Carpenter Technology (CRS) Could Be 27% Undervalued As Pullback Tests Growth Story
Recent trading in Carpenter Technology (CRS) has caught investor attention after a sharp pullback, with the share price down about 18% over the past month and past 3 months despite strong trailing multiyear returns.
Over the past year, Carpenter Technology has seen its share price advance strongly despite the recent pullback. The year-to-date share price return of 35.5% and a one-year total shareholder return of 86.0% point to momentum that has cooled in the last quarter as investors reassess growth expectations and risk around the current US$458.45 level.
Scan how Carpenter Technology compares to peers facing similar momentum shifts by checking a curated set of 17 high quality undiscovered gems in related industrial and capital goods markets.
The recent slide leaves Carpenter Technology trading well below its highs, yet still sitting on very strong trailing returns. Does that setback now tilt the risk reward toward fresh buyers, or suggest the easy money has already been made?
Most Popular Narrative: 27% Undervalued
On the most followed narrative, Carpenter Technology's fair value of $625.88 sits meaningfully above the recent $458.45 close. This frames the latest pullback as a gap between modeled earnings power and market pricing.
The brownfield expansion project is set to add high-purity melt capacity, allowing Carpenter to further leverage the industry supply-demand imbalance over the medium to long term, this will support higher volumes and sustained pricing power, translating into increased revenue and operating income beginning FY28.
Read the complete narrative. Read the complete narrative.
Want to know what kind of revenue runway, margin profile, and future earnings multiple need to line up for that valuation to hold? The narrative leans heavily on aerospace demand, power generation strength, and a richer mix of higher value alloys. Curious how those moving parts are stitched together into one fair value number and which assumptions really carry the load?
Result: Fair Value of $625.88 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Carpenter Technology's heavy reliance on aerospace and defense demand, along with the large brownfield expansion spend, could quickly challenge that undervaluation story.
Find out about the key risks to this Carpenter Technology narrative.
Next Steps
Mixed messages on Carpenter Technology's valuation and risk profile can be confusing, so move quickly, review the data first hand, then weigh both the 4 key rewards and 1 important warning sign.
Looking for more Carpenter Technology investment ideas?
If this Carpenter Technology narrative has sharpened your thinking, do not stop here. Broader opportunities are moving every day, and the best setups rarely wait around.
- Target quality first by scanning a list of solid balance sheet and fundamentals (24 results) that can handle shocks and still keep their financial foundations intact.
- Hunt for mispriced opportunities with a 31 high quality undervalued stocks that filters for stronger fundamentals than the current share prices might suggest.
- Prioritise resilience with a 10 resilient stocks with low risk scores so you are not caught off guard when volatility picks up again.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
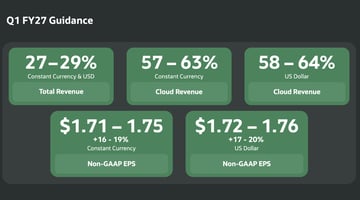
Oracle has $638 billion of orders it can't fill yet. Tonight tells us how much it's costing to get ready.
97
s
sean_3pk06
Sixty-eight percent gross margin business is buying its way into a thirty-five percent gross margin business, and revenue growth is the metric everyone is watching.
d
devon_jd150
This is important about Oracle. Nvidia went to six of the biggest asset managers on earth to make sure someone else held this risk. Oracle just borrowed the money and held it itself.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NYSE:CRS
Carpenter Technology
Manufactures, fabricates, and distributes specialty metals in the United States, Europe, the Asia Pacific, Mexico, Canada, and internationally.
Flawless balance sheet with solid track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2536.2% undervalued
186 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4934.6% undervalued
35 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.9% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
TI

TimLee on Pentech Holdings Berhad ·
Why Pentech Stands Out After 2QFY26
Fair Value:RM 0.5333.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RO


RockeTeller on Lahontan Gold ·
Lahontan Gold: Past-Producing Nevada Gold Mine Targets 2027 Construction
Fair Value:CA$9.0595.6% undervalued
20 followersusers have followed this narrative
9 commentsusers have commented on this narrative
1 likeusers have liked this narrative
SZ


Szock on Sanofi ·
Sanofi stocks will shine with an 8% profit surge
Fair Value:€72.232.8% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.1% undervalued
1406 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.8% undervalued
1621 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.7% undervalued
1594 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative

