
Advertisement
Reply S.p.A. (BIT:REY), is not the largest company out there, but it saw significant share price movement during recent months on the BIT, rising to highs of €157 and falling to the lows of €116. Some share price movements can give investors a better opportunity to enter into the stock, and potentially buy at a lower price. A question to answer is whether Reply's current trading price of €118 reflective of the actual value of the mid-cap? Or is it currently undervalued, providing us with the opportunity to buy? Let’s take a look at Reply’s outlook and value based on the most recent financial data to see if there are any catalysts for a price change.
Check out our latest analysis for Reply
What's the opportunity in Reply?
The share price seems sensible at the moment according to my price multiple model, where I compare the company's price-to-earnings ratio to the industry average. In this instance, I’ve used the price-to-earnings (PE) ratio given that there is not enough information to reliably forecast the stock’s cash flows. I find that Reply’s ratio of 29.17x is trading slightly above its industry peers’ ratio of 26.2x, which means if you buy Reply today, you’d be paying a relatively sensible price for it. And if you believe Reply should be trading in this range, then there isn’t really any room for the share price grow beyond the levels of other industry peers over the long-term. Although, there may be an opportunity to buy in the future. This is because Reply’s beta (a measure of share price volatility) is high, meaning its price movements will be exaggerated relative to the rest of the market. If the market is bearish, the company’s shares will likely fall by more than the rest of the market, providing a prime buying opportunity.
What kind of growth will Reply generate?
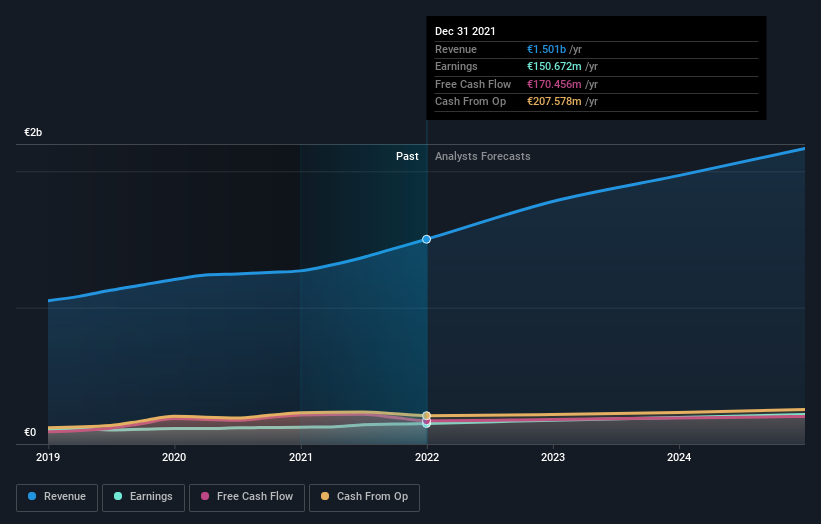
Future outlook is an important aspect when you’re looking at buying a stock, especially if you are an investor looking for growth in your portfolio. Although value investors would argue that it’s the intrinsic value relative to the price that matter the most, a more compelling investment thesis would be high growth potential at a cheap price. With profit expected to grow by 43% over the next couple of years, the future seems bright for Reply. It looks like higher cash flow is on the cards for the stock, which should feed into a higher share valuation.
What this means for you:
Are you a shareholder? REY’s optimistic future growth appears to have been factored into the current share price, with shares trading around industry price multiples. However, there are also other important factors which we haven’t considered today, such as the financial strength of the company. Have these factors changed since the last time you looked at REY? Will you have enough confidence to invest in the company should the price drop below the industry PE ratio?
Are you a potential investor? If you’ve been keeping tabs on REY, now may not be the most optimal time to buy, given it is trading around industry price multiples. However, the positive outlook is encouraging for REY, which means it’s worth diving deeper into other factors such as the strength of its balance sheet, in order to take advantage of the next price drop.
With this in mind, we wouldn't consider investing in a stock unless we had a thorough understanding of the risks. Every company has risks, and we've spotted 1 warning sign for Reply you should know about.
If you are no longer interested in Reply, you can use our free platform to see our list of over 50 other stocks with a high growth potential.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.

 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
98
About BIT:REY
Reply
Provides consulting, system integration, and digital services based on communication channels and digital media in Italy and internationally.
Flawless balance sheet with solid track record and pays a dividend.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0615.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TO


Tokyo on Novo Nordisk ·
EU#2 - From Humble Beginnings to Global Powerhouse
Fair Value:DKK 851.0469.6% undervalued
75 followersusers have followed this narrative
11 commentsusers have commented on this narrative
25 likesusers have liked this narrative
HA


HarishPK on Zoetis ·
Decision Making Under Ambiguity – A Case Study on Expectations Investing
Fair Value:US$91.320.2% undervalued
3 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
RE


RedCandleRx on AppLovin ·
Why the Market Still Misprices AppLovin as Just a Gaming Network
Fair Value:US$50735.2% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Recently Updated Narratives
MA


MarkoVT on Alphabet ·
Mo' Money, Mo' Problems
Fair Value:US$443.3622.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on AutoZone ·
AZO | AutoZone, Inc.: What They Said vs. What They Did
Fair Value:US$2.83k2.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FR


FRAGMENTS on Five Point Holdings ·
Five Point Trades Around $5. It Has $2.34 Billion of Economic Capital. How Much Reaches One Share?
Fair Value:US$5.6613.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.4% undervalued
1496 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN
AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.9% undervalued
1651 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.0% undervalued
1670 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


JO

john_mwm1h on Hemab Therapeutics Holdings ·
One thing I find disappointing about this model is how rare disease communities can become attractive targets because development pathways may move faster with smaller patient populations. The marketing they run creates the impression that patients are constantly in danger or have no meaningful options without the newest treatment, which does not reflect every patient’s experience.I would bet many do not even realize that gene therapy for Glanzmann Thrombasthenia is getting closer to clinical trials, yet that research continues to struggle for funding while commercial drug developers can raise hundreds of millions of dollars.
0
|0