
Advertisement
- United Kingdom
- /
- Other Utilities
- /
- LSE:CNA
Centrica (LON:CNA) Has Some Difficulty Using Its Capital Effectively
What financial metrics can indicate to us that a company is maturing or even in decline? A business that's potentially in decline often shows two trends, a return on capital employed (ROCE) that's declining, and a base of capital employed that's also declining. This reveals that the company isn't compounding shareholder wealth because returns are falling and its net asset base is shrinking. On that note, looking into Centrica (LON:CNA), we weren't too upbeat about how things were going.
Understanding Return On Capital Employed (ROCE)
Just to clarify if you're unsure, ROCE is a metric for evaluating how much pre-tax income (in percentage terms) a company earns on the capital invested in its business. To calculate this metric for Centrica, this is the formula:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.027 = UK£244m ÷ (UK£27b - UK£18b) (Based on the trailing twelve months to December 2021).
So, Centrica has an ROCE of 2.7%. Ultimately, that's a low return and it under-performs the Integrated Utilities industry average of 5.1%.
Check out our latest analysis for Centrica
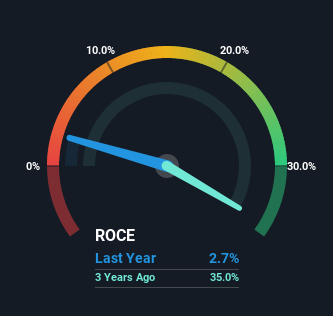
In the above chart we have measured Centrica's prior ROCE against its prior performance, but the future is arguably more important. If you'd like to see what analysts are forecasting going forward, you should check out our free report for Centrica.
What The Trend Of ROCE Can Tell Us
We are a bit anxious about the trends of ROCE at Centrica. To be more specific, today's ROCE was 9.5% five years ago but has since fallen to 2.7%. On top of that, the business is utilizing 35% less capital within its operations. The combination of lower ROCE and less capital employed can indicate that a business is likely to be facing some competitive headwinds or seeing an erosion to its moat. If these underlying trends continue, we wouldn't be too optimistic going forward.
While on the subject, we noticed that the ratio of current liabilities to total assets has risen to 66%, which has impacted the ROCE. If current liabilities hadn't increased as much as they did, the ROCE could actually be even lower. And with current liabilities at these levels, suppliers or short-term creditors are effectively funding a large part of the business, which can introduce some risks.
The Bottom Line
To see Centrica reducing the capital employed in the business in tandem with diminishing returns, is concerning. Investors haven't taken kindly to these developments, since the stock has declined 51% from where it was five years ago. With underlying trends that aren't great in these areas, we'd consider looking elsewhere.
On a final note, we found 2 warning signs for Centrica (1 is potentially serious) you should be aware of.
While Centrica isn't earning the highest return, check out this free list of companies that are earning high returns on equity with solid balance sheets.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
The most boring corner of the market just hit a 50-year low against stocks. History says that's when it's worth paying attention.

98
p
pri_dlp7z
Supply-driven inflation breaks stocks and bonds at the same time. That is the one scenario commodities cover and nothing else does.
s
stefano_751bk
What the graphs says is that S&P 500 is just too expensive
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
72
About LSE:CNA
Centrica
Operates as an integrated energy company in the United Kingdom, Ireland, Scandinavia, North America, and internationally.
Very undervalued with excellent balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
71 followersusers have followed this narrative
1 commentusers have commented on this narrative
18 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4931.2% undervalued
13 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.7% undervalued
14 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
Recently Updated Narratives
DA


davidlsander on Ubisoft Entertainment ·
Is Ubisoft the Market’s Biggest Pricing Error? Why Forensic Value Points to €33 Per Share
Fair Value:€33.885.6% undervalued
96 followersusers have followed this narrative
8 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AL


Alhabib on Zevra Therapeutics ·
revenue is growing while new-patient acquisition has decelerated sharply
Fair Value:US$13.58.1% undervalued
6 followersusers have followed this narrative
2 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO


John_Eric on IREN ·
The Bitcoin Miner Who Accidentally Built the Best Real Estate Portfolio in AI
Fair Value:US$307.285.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8323.9% undervalued
1385 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
131 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32720.9% undervalued
1606 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative


