
Advertisement
- Hong Kong
- /
- Construction
- /
- SEHK:1459
Jujiang Construction Group (HKG:1459) Has A Rock Solid Balance Sheet
Legendary fund manager Li Lu (who Charlie Munger backed) once said, 'The biggest investment risk is not the volatility of prices, but whether you will suffer a permanent loss of capital.' So it seems the smart money knows that debt - which is usually involved in bankruptcies - is a very important factor, when you assess how risky a company is. As with many other companies Jujiang Construction Group Co., Ltd. (HKG:1459) makes use of debt. But the more important question is: how much risk is that debt creating?
When Is Debt Dangerous?
Generally speaking, debt only becomes a real problem when a company can't easily pay it off, either by raising capital or with its own cash flow. Part and parcel of capitalism is the process of 'creative destruction' where failed businesses are mercilessly liquidated by their bankers. However, a more common (but still painful) scenario is that it has to raise new equity capital at a low price, thus permanently diluting shareholders. Of course, debt can be an important tool in businesses, particularly capital heavy businesses. When we examine debt levels, we first consider both cash and debt levels, together.
See our latest analysis for Jujiang Construction Group
What Is Jujiang Construction Group's Net Debt?
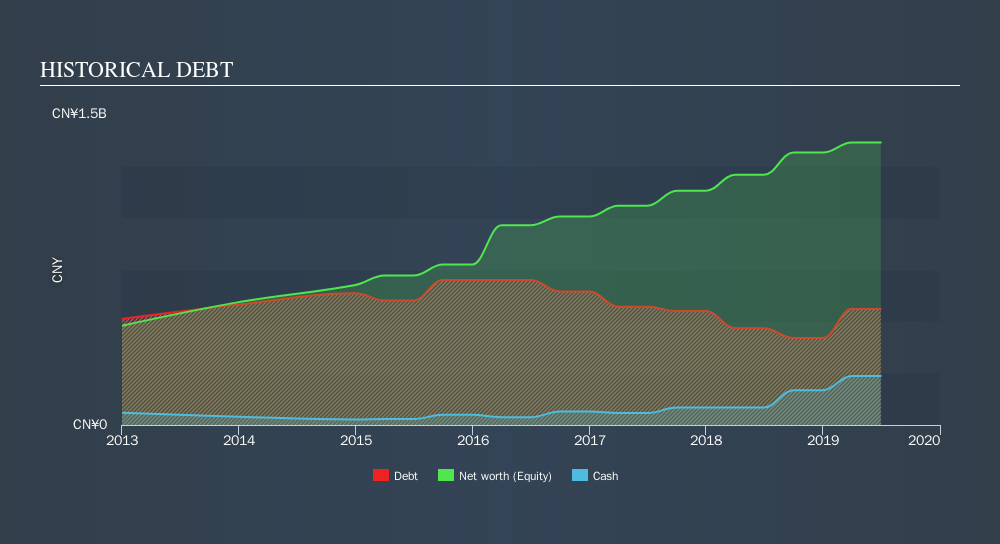
The image below, which you can click on for greater detail, shows that at June 2019 Jujiang Construction Group had debt of CN¥560.1m, up from CN¥466.7m in one year. However, it also had CN¥236.9m in cash, and so its net debt is CN¥323.2m.
A Look At Jujiang Construction Group's Liabilities
The latest balance sheet data shows that Jujiang Construction Group had liabilities of CN¥3.83b due within a year, and liabilities of CN¥102.4m falling due after that. Offsetting this, it had CN¥236.9m in cash and CN¥4.21b in receivables that were due within 12 months. So it actually has CN¥519.1m more liquid assets than total liabilities.
This luscious liquidity implies that Jujiang Construction Group's balance sheet is sturdy like a giant sequoia tree. On this view, it seems its balance sheet is as strong as a black-belt karate master.
We use two main ratios to inform us about debt levels relative to earnings. The first is net debt divided by earnings before interest, tax, depreciation, and amortization (EBITDA), while the second is how many times its earnings before interest and tax (EBIT) covers its interest expense (or its interest cover, for short). The advantage of this approach is that we take into account both the absolute quantum of debt (with net debt to EBITDA) and the actual interest expenses associated with that debt (with its interest cover ratio).
Jujiang Construction Group has net debt of just 1.1 times EBITDA, indicating that it is certainly not a reckless borrower. And it boasts interest cover of 7.2 times, which is more than adequate. Fortunately, Jujiang Construction Group grew its EBIT by 7.7% in the last year, making that debt load look even more manageable. There's no doubt that we learn most about debt from the balance sheet. But it is Jujiang Construction Group's earnings that will influence how the balance sheet holds up in the future. So if you're keen to discover more about its earnings, it might be worth checking out this graph of its long term earnings trend.
Finally, a company can only pay off debt with cold hard cash, not accounting profits. So it's worth checking how much of that EBIT is backed by free cash flow. Over the last three years, Jujiang Construction Group actually produced more free cash flow than EBIT. That sort of strong cash conversion gets us as excited as the crowd when the beat drops at a Daft Punk concert.
Our View
Happily, Jujiang Construction Group's impressive conversion of EBIT to free cash flow implies it has the upper hand on its debt. And that's just the beginning of the good news since its level of total liabilities is also very heartening. It looks Jujiang Construction Group has no trouble standing on its own two feet, and it has no reason to fear its lenders. To our minds it has a healthy happy balance sheet. Given Jujiang Construction Group has a strong balance sheet is profitable and pays a dividend, it would be good to know how fast its dividends are growing, if at all. You can find out instantly by clicking this link.
Of course, if you're the type of investor who prefers buying stocks without the burden of debt, then don't hesitate to discover our exclusive list of net cash growth stocks, today.
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned. Thank you for reading.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
912
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
84
About SEHK:1459
Jujiang Construction Group
Provides construction contracting services for residential, commercial, industrial, and public works in the People’s Republic of China and Hong Kong.
Excellent balance sheet and good value.
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0625.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.5% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8528.7% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
ON

Ontological on Hinge Health ·
Scaling Digital Musculoskeletal Care With Strong Growth and Margins, Hinge Health (HNGE)
Fair Value:US$145.0434.9% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HO

hongjuan_p6tor on DSC Holdings ·
DSC is not a second car dealer like Carvana but a used car dealer enabler
Fair Value:US$3.32103.9% overvalued
1 followerusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
TI

TimLee on 3REN Berhad ·
3REN Berhad Is Powering the Semiconductor Ecosystem and Smart Manufacturing
Fair Value:RM 0.6843.4% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.9% undervalued
1493 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.0% undervalued
1652 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.0% undervalued
1669 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


PE
peng_i7fl6 on DSC Holdings ·
What stood out to me in this piece is how Zou draws a clear line between DSC and platforms like Carvana. DSC doesn't sell cars itself — it sits behind dealers and provides the operating system and transaction services. Once you frame it that way, the 90% market share starts to mean something real. Dealers run their daily work on the system: listings, pricing, inventory. The data accumulates bit by bit, and that's not something a competitor can buy its way into. You can't just throw money at it and get tens of thousands of dealers to switch systems.Her point about EVs was practical too. More brands, more models, more trim levels — dealer SKU management has gotten a lot messier, and pricing moves fast. Relying on gut feel from the old days doesn't cut it anymore. That demand isn't something the company invented; the industry just got to this point on its own.On the stock, her answer was honest. Management can't control short-term price action after listing, so they focus on running the business and delivering results. That reads more credible than pumping a narrative.The things I'd watch: whether dealer retention holds up, and whether the data and AI tools eventually show up as real revenue. A good story still has to pass the financials.
0
|0