Advertisement
- United States
- /
- Electronic Equipment and Components
- /
- NasdaqCM:MVIS
MicroVision Faces Nasdaq Bid Price Warning As Long Term Weakness Persists
SI

Reviewed by Bailey Pemberton
- MicroVision (NasdaqGM:MVIS) has received a notification from Nasdaq regarding a minimum bid price deficiency.
- The notice indicates that the company is currently not meeting Nasdaq's required minimum bid price for continued listing.
- This development raises the possibility of future delisting if MicroVision does not regain compliance within the specified timeframe.
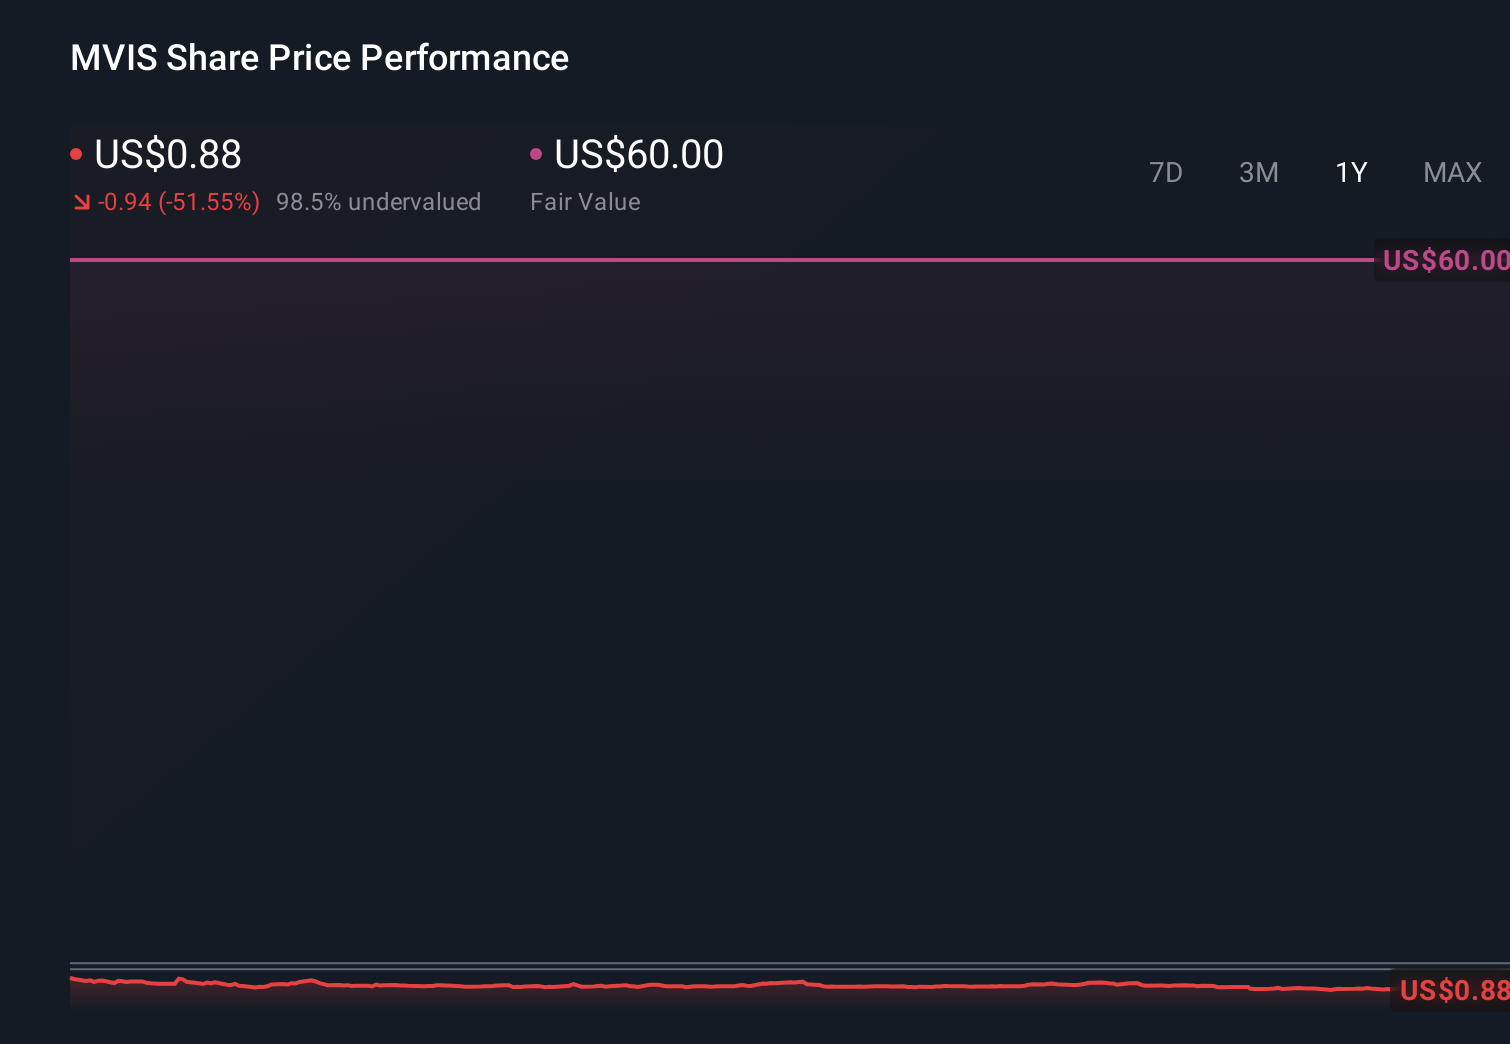
For you as an investor, this Nasdaq notice is a clear signal that MicroVision's current share price of $0.8809 has fallen below an important listing threshold. The stock has seen a 44.6% decline over the past year and a 64.8% decline over three years, which places this latest development in the wider context of prolonged share price weakness.
MicroVision's value score of 1 and a 5 year return of an 88.1% decline indicate that sentiment around the stock has been under pressure for an extended period. From here, the key factors to monitor are how the company responds to the deficiency notice and whether any corporate actions or business updates are announced that are aimed at regaining compliance with Nasdaq's listing rules.
Stay updated on the most important news stories for MicroVision by adding it to your watchlist or portfolio. Alternatively, explore our Community to discover new perspectives on MicroVision.
Is MicroVision financially strong enough to weather the next crisis?
The Nasdaq notice puts a clear regulatory clock on MicroVision, as it has 180 days from January 12, 2026 to get its share price back to at least US$1 for 10 consecutive business days. While the letter does not affect current trading, operations, SEC reporting or contracts, it introduces an additional overhang for investors because failure to regain compliance could eventually lead to delisting or a move to a lower tier market.
MicroVision Narrative, Put in a Regulatory Spotlight
This development feeds directly into the existing narrative around MicroVision as a company with prolonged share price weakness and pressure on sentiment. For investors who already see the stock as higher risk, the bid price deficiency can reinforce concerns about how the equity story is being received in the market.
Risks and rewards now in sharper focus
- ⚠️ The company faces 3 flagged risks, including a history of shareholder dilution in the past year, which can weigh on confidence during a compliance window.
- ⚠️ MicroVision does not have meaningful revenue of more than US$3m, so it has less operating scale to absorb prolonged market or funding pressure.
- ⚠️ The business is currently unprofitable and not forecast to become profitable over the next 3 years, which can limit flexibility if it considers options such as capital raises or restructuring.
- 🎁 On the other side, analysts see revenue growth potential of 54.91% per year, which some investors may view as a possible offset to the regulatory and financial risks if execution improves.
What to watch from here
From here, you may want to watch for any announced actions to support the share price, such as potential corporate moves, business updates or shareholder communications that address the Nasdaq timeline. You can also stay close to how the story evolves by following community views and detailed stock write ups in this narrative hub.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Is Nvidia actually expensive at 32 times earnings? I think that number can melt faster than people realise.
77
MA
marcus_l38oa
Why would I fret over Nvidia results now? I think it's moment has gone. I will invert and see what companies can be the next Nvidia.
SE
sean_3pk06
Multiple has already melted 50 percent in the last year. It can melt another 50 percent from here in the next year?
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?

Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
42
About NasdaqCM:MVIS
MicroVision
Develops and commercializes lidar sensors and perception solutions in the United States, Germany, and internationally.
Moderate risk with adequate balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
69 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
52 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
47 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
12 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
AS


AstrisCorporateAdvisory on Restar ·
Monitoring next steps
Fair Value:JP¥2.59k96.7% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
PR


prajeeshprathap on Medpace Holdings ·
Why Medpace Outperforms Competitors in the Mid-Sized Biotech Niche
Fair Value:US$53614.6% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AS

AstrisCorporateAdvisory on Polaris Holdings ·
Share gains to fuel earnings momentum
Fair Value:JP¥211.168.6% undervalued
4 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
359 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
206 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
231 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


