
Advertisement
- United States
- /
- Software
- /
- NasdaqGS:CFLT
Confluent (CFLT) Valuation Check After Mixed Returns And Ongoing IBM Acquisition Debate
Why Confluent (CFLT) is on investors’ radar today
Confluent (CFLT) is drawing attention after recent share performance data highlighted contrasting returns, including a gain over the past 3 months and a decline across the past year. This pattern is prompting fresh questions about its valuation.
See our latest analysis for Confluent.
The recent 34.86% 3 month share price return contrasts with a 12.31% decline in 1 year total shareholder return. This suggests that momentum has picked up again, even though longer term holders have yet to see a recovery.
If Confluent’s recent move has you looking beyond a single name, this could be a good moment to size up 58 profitable AI stocks that aren't just burning cash as potential next ideas on your list.
With Confluent trading at US$30.56, only around 1% below the average analyst price target and with a calculated intrinsic value that sits higher than today’s price, you have to ask yourself: is this a chance to buy, or is the market already pricing in future growth?
Most Popular Narrative: 30% Undervalued
Confluent’s most followed narrative pegs fair value at about $30.65, almost level with the last close at $30.56, yet still frames the shares as undervalued.
Analysts trimmed their fair value estimate for Confluent slightly from about $30.77 to $30.65. This reflects a mix of cautious views around the pending IBM acquisition and downgrades, as well as more upbeat commentary on stabilizing cloud growth, improving margins, and ongoing product momentum that supports a lower assumed future P/E multiple.
Recent research has highlighted a split in how professionals view Confluent. Some are focused on execution and product momentum, while others center on the pending IBM takeover and deal mechanics.
Want to see what kind of revenue path, margin lift and future earnings multiple have to come together to support that valuation? The full narrative lays out a very specific growth runway, a profitability shift and a premium future P/E assumption that is far from ordinary. If you are curious which of those inputs does most of the heavy lifting in the model, the details are all there.
Result: Fair Value of $30.65 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, there are still clear pressure points, including slower cloud consumption trends and competitive threats from open source or self managed alternatives that could challenge this upbeat scenario.
Find out about the key risks to this Confluent narrative.
Another View: Price Suggests a Richer Story
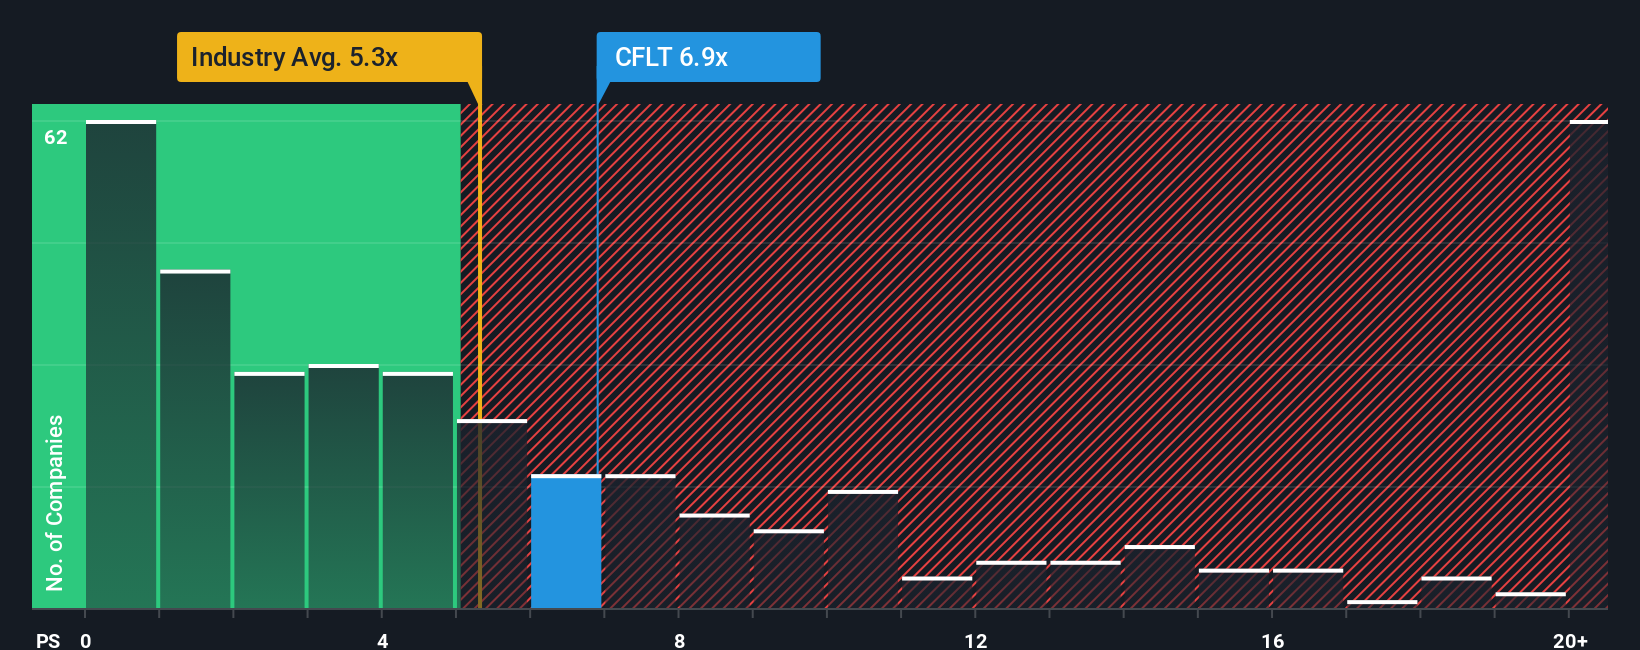
That 30% undervalued narrative sits uncomfortably against how the market is actually pricing Confluent today. On a P/S of 9.4x, the shares trade well above the US Software average of 3.6x, the peer average of 6.4x, and even our fair ratio of 7x. That kind of gap can signal either upside conviction or valuation risk. Which side do you think you are on?
See what the numbers say about this price — find out in our valuation breakdown.
Build Your Own Confluent Narrative
If you are not sold on this view or prefer to rely on your own homework, you can develop a custom Confluent thesis in just a few minutes: Do it your way.
A great starting point for your Confluent research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
Ready to hunt for your next idea?
If Confluent has sharpened your thinking, do not stop here. Broaden your watchlist with focused screens that surface specific types of opportunities in minutes.
- Target potential mispricings by reviewing companies highlighted in our 54 high quality undervalued stocks and see which ones deserve a closer look on your shortlist.
- Strengthen your focus on resilience by scanning stocks in the 83 resilient stocks with low risk scores and see which names align with a steadier risk profile.
- Spot lesser known opportunities by checking our screener containing 24 high quality undiscovered gems and see which companies might not yet be on everyone else’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

710
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
10
About NasdaqGS:CFLT
Confluent
Operates a data streaming platform in the United States and internationally.
Excellent balance sheet with very low risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
61 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17014.4% undervalued
43 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.6% undervalued
44 followersusers have followed this narrative
2 commentsusers have commented on this narrative
17 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.9% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on KNOT Offshore Partners ·
KNOP | KNOT Offshore Partners LP: What They Said vs. What They Did
Fair Value:US$10.774.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AS


AstrisCorporateAdvisory on Ryobi ·
Entering a year of earnings consolidation
Fair Value:JP¥2.37k15.9% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
BL


Blagget on Terra Balcanica Resources ·
The C$4M Explorer Positioned to Become Europe's First Antimony Mine
Fair Value:CA$0.490.0% undervalued
6 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.4% undervalued
375 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k45.8% undervalued
129 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9121.5% overvalued
223 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
