Advertisement
- United States
- /
- Software
- /
- NasdaqGS:ADBE
Is Adobe’s (ADBE) Freemium AI Pivot Reframing Its Core Investment Story Amid Leadership Change?
SI

Reviewed by Sasha Jovanovic
- In recent days, Adobe has faced split analyst opinions, leadership transitions including a CEO and CFO search, and a shift toward a slower-converting freemium and AI-focused business model that is reshaping how it grows its user base and recurring revenue.
- At the same time, Adobe’s role in initiatives like Transcend’s Unlock partner program underlines how central its tools have become in enterprise AI workflows, even as investors debate how effectively the company can turn this usage into earnings.
- Next, we’ll examine how Adobe’s leadership search and freemium-focused AI strategy may influence the company’s existing investment narrative and assumptions.
Capitalize on the AI infrastructure supercycle with our selection of the 54 best 'picks and shovels' of the AI gold rush converting record-breaking demand into massive cash flow.
Adobe Investment Narrative Recap
To own Adobe today, you need to believe its freemium and AI-heavy model can turn a much larger user base into durable subscription cash flows, despite leadership turnover and debate over AI monetization. The main near term catalyst remains evidence that freemium users and AI tools can scale revenue efficiently, while the biggest risk is that intensifying AI competition and pricing pressure keep that monetization below expectations. The latest analyst rating split does not materially change those core questions.
Among recent updates, Adobe’s participation in Transcend’s Unlock partner program stands out, because it highlights how embedded Adobe’s tools are becoming inside enterprise AI data and governance workflows. That positioning directly intersects with the key catalyst of AI driven products like Firefly and Acrobat AI Assistant, since it reinforces Adobe’s role in the broader AI stack even as markets weigh how quickly that usage might translate into subscription growth.
Yet beneath the product buzz, investors should be aware that competitive pressure on AI pricing and user conversion could...
Read the full narrative on Adobe (it's free!)
Adobe's narrative projects $32.0 billion revenue and $9.1 billion earnings by 2029. This requires 9.4% yearly revenue growth and about a $1.9 billion earnings increase from $7.2 billion today.
Uncover how Adobe's forecasts yield a $331.63 fair value, a 47% upside to its current price.
Exploring Other Perspectives
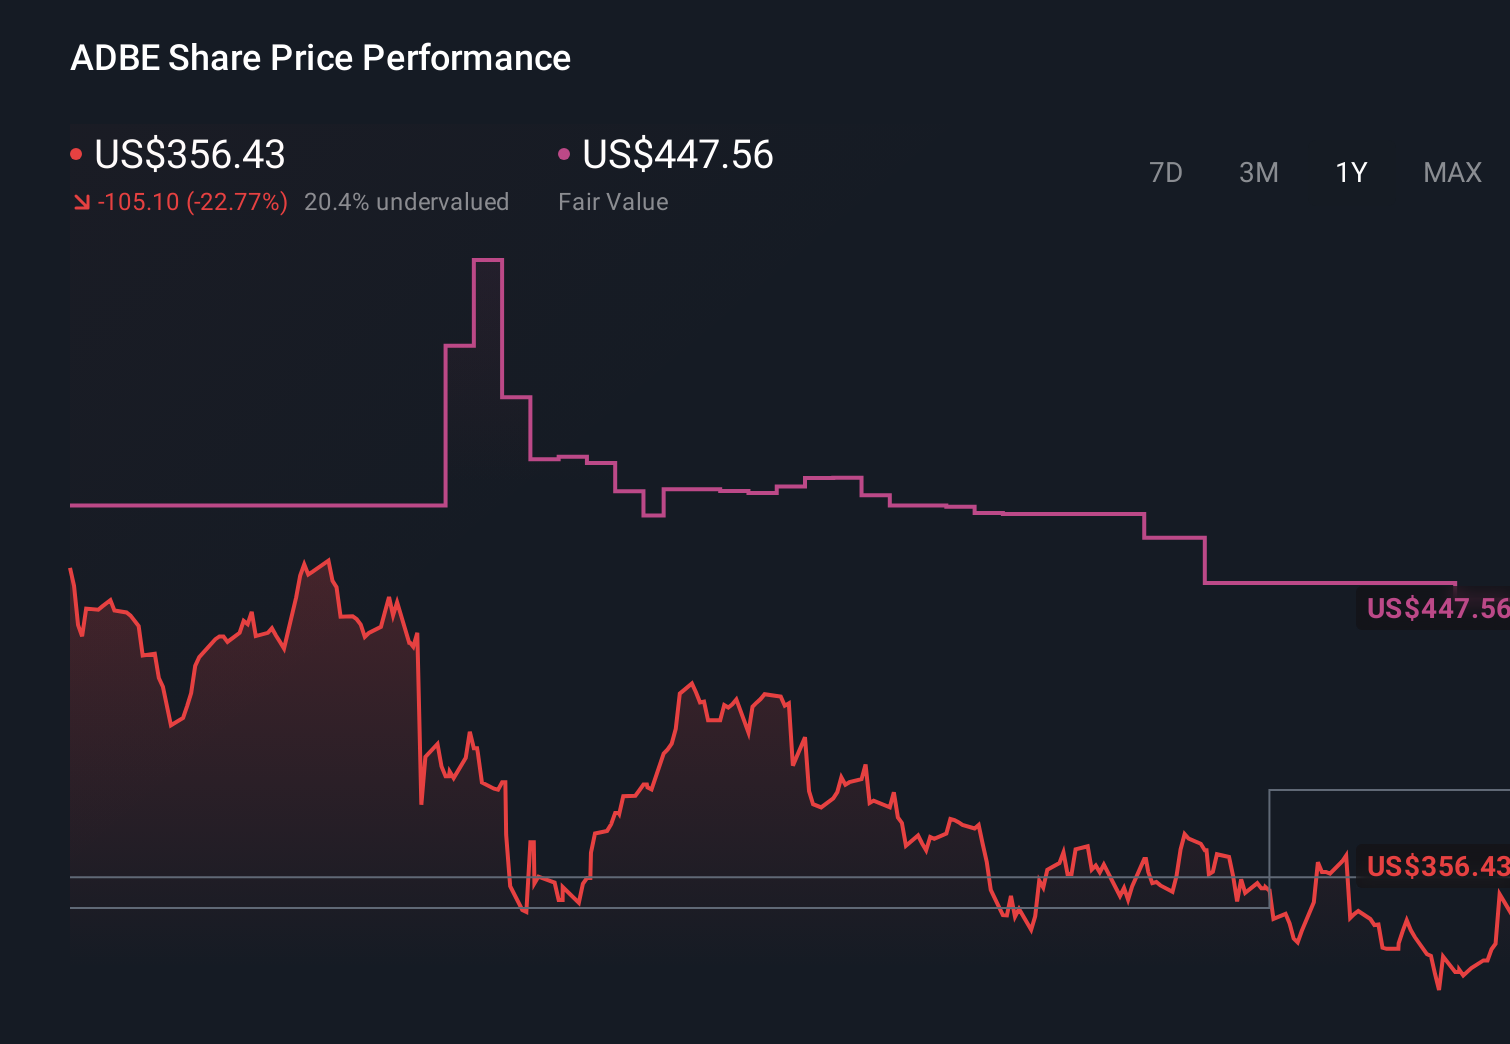
Some of the most optimistic analysts expected Adobe to reach about US$34.9 billion in revenue and US$10.5 billion in earnings by 2029, which is far more bullish than the baseline view and could be tested by how the freemium and AI pivot responds to the latest concerns around growth and leadership.
Explore 77 other fair value estimates on Adobe - why the stock might be worth over 2x more than the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Adobe research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- Our free Adobe research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Adobe's overall financial health at a glance.
No Opportunity In Adobe?
Every day counts. These free picks are already gaining attention. See them before the crowd does:
- Find 46 companies with promising cash flow potential yet trading below their fair value.
- Invest in the nuclear renaissance through our list of 90 elite nuclear energy infrastructure plays powering the global AI revolution.
- Uncover the next big thing with 21 elite penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Nvidia's (NVDA) record profit had a US$7.8 billion catch. That chunk came from betting on its own customers, not from selling its chips.
147
JA

Jake_Merritt
The circularity worth examining is not the mark-to-market line. A large and growing share of Nvidia's revenue comes from companies funded by venture capital, and Nvidia participates in some of those rounds. That is the loop. The paper gains are just an accounting reflection of it, so focusing on them means arguing about the mirror rather than the room.
NA
nadia_y3d8i
Hyperscalers grew 13% sequentially, the other AI segment grew 25% and 138% year on year. The faster half is the funded half. AI venture funding was over 400 billion in the first half with about 70% spent on compute. That is an interesting composition shift like I mentioned yesterday.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
00
About NasdaqGS:ADBE
Adobe
Operates as a technology company worldwide.
Undervalued with adequate balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.5% undervalued
58 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
56 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11633.7% undervalued
12 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
TH


TheFutureOfValue on GQG Partners ·
Structural Resilience and Alpha Architecture: Why GQG Partners Represents an ASX Blue Chip Stock of the Future
Fair Value:AU$25.6494.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
BL


BlackGoat on IREN ·
IREN's Bold Moves in Sustainable Bitcoin Mining & AI Data Centers
Fair Value:US$71.4843.3% undervalued
249 followersusers have followed this narrative
15 commentsusers have commented on this narrative
0 likesusers have liked this narrative
SA

SashaJ on Astera Labs ·
Astera Labs - A Great Story But At What Price
Fair Value:US$335.829.4% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.6% undervalued
365 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9120.3% overvalued
213 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0946.1% undervalued
237 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


