Advertisement
- United States
- /
- Biotech
- /
- NasdaqGS:RXRX
Will Recursion (RXRX) Share Registration Deepen Its Tech Partnerships or Signal a Shift in Strategy?
SI

Reviewed by Sasha Jovanovic
- Earlier this week, Recursion Pharmaceuticals registered over 7 million Class A common shares for resale, which had been issued to Tempus AI as payment for annual license fees.
- This development signals a significant move in asset management and partnership monetization, highlighting both the company's use of equity and its technology-driven collaborations.
- We will now examine how the registration of Tempus AI's shares may influence Recursion Pharmaceuticals’ investment narrative and business outlook.
Rare earth metals are the new gold rush. Find out which 35 stocks are leading the charge.
Recursion Pharmaceuticals Investment Narrative Recap
At its core, Recursion Pharmaceuticals’ investment case centers on the potential of AI-driven drug discovery platforms to transform R&D efficiency and attract significant pharma partnerships, a narrative built on accelerating clinical progress and data-powered collaboration. The recent registration for resale of over 7 million shares to Tempus AI, while reflecting active balance sheet and partnership management, does not shift the current focus: advancing key internal programs and navigating early-stage clinical risks remain the primary near-term catalyst and a critical business risk.
The June announcement of Boltz-2, Recursion’s open-sourced biomolecular foundation model, is particularly relevant given its integration with Tempus AI and broader partner ecosystem. Continued rollout and uptake of cutting-edge AI tools like Boltz-2 is intended to drive superior R&D performance, potentially influencing both collaborations and internal pipeline milestones, but execution risk around realizing marketable assets persists.
By contrast, investors should remain aware of the ongoing risk that Recursion’s heavy reliance on revenues from a small group of pharma partners poses to topline stability, especially if partnership terms shift or milestones are delayed…
Read the full narrative on Recursion Pharmaceuticals (it's free!)
Recursion Pharmaceuticals' outlook anticipates $220.9 million in revenue and $35.5 million in earnings by 2028. This scenario relies on 50.7% annual revenue growth and a $684.6 million increase in earnings from the current $-649.1 million.
Uncover how Recursion Pharmaceuticals' forecasts yield a $6.33 fair value, a 37% upside to its current price.
Exploring Other Perspectives
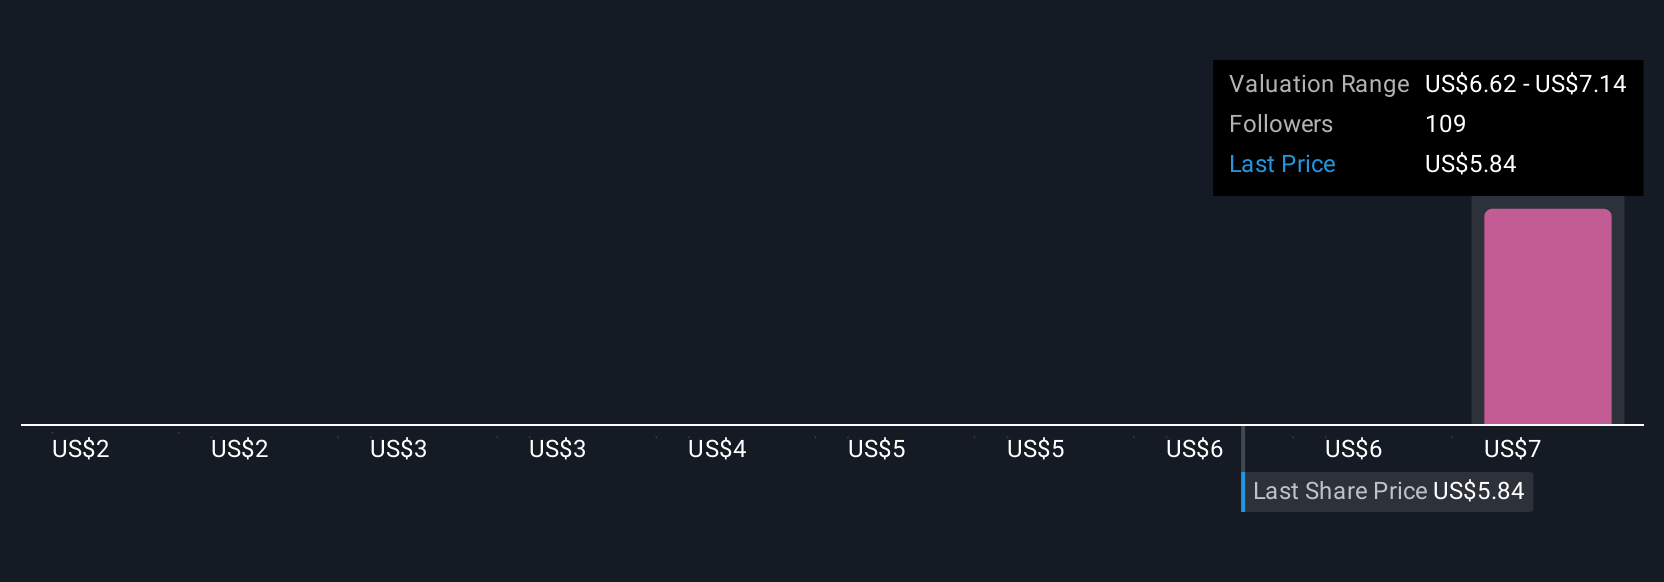
Five Simply Wall St Community fair value estimates for Recursion range from US$1.92 to US$10 per share, showing a wide spread of investor expectations. This underscores how partnership revenue concentration and evolving collaboration terms may continue to play an outsized role in shaping near term valuations, be sure to compare these viewpoints for a fuller picture.
Explore 5 other fair value estimates on Recursion Pharmaceuticals - why the stock might be worth over 2x more than the current price!
Build Your Own Recursion Pharmaceuticals Narrative
Disagree with existing narratives? Create your own in under 3 minutes - extraordinary investment returns rarely come from following the herd.
- A great starting point for your Recursion Pharmaceuticals research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- Our free Recursion Pharmaceuticals research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Recursion Pharmaceuticals' overall financial health at a glance.
Seeking Other Investments?
Our daily scans reveal stocks with breakout potential. Don't miss this chance:
- Explore 28 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
- Outshine the giants: these 25 early-stage AI stocks could fund your retirement.
- These 13 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Is Nvidia actually expensive at 32 times earnings? I think that number can melt faster than people realise.
77
MA
marcus_l38oa
Why would I fret over Nvidia results now? I think it's moment has gone. I will invert and see what companies can be the next Nvidia.
SE
sean_3pk06
Multiple has already melted 50 percent in the last year. It can melt another 50 percent from here in the next year?
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?

Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
42
About NasdaqGS:RXRX
Recursion Pharmaceuticals
A clinical-stage biotechnology company, engages in the decoding biology and chemistry by integrating technological innovations across biology, chemistry, automation, data science, and engineering to industrialize drug discovery in the United States and the United Kingdom.
Excellent balance sheet and slightly overvalued.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
69 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
51 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
45 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
11 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
AS


AstrisCorporateAdvisory on Restar ·
Monitoring next steps
Fair Value:JP¥2.59k96.7% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
PR


prajeeshprathap on Medpace Holdings ·
Why Medpace Outperforms Competitors in the Mid-Sized Biotech Niche
Fair Value:US$53614.6% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AS

AstrisCorporateAdvisory on Polaris Holdings ·
Share gains to fuel earnings momentum
Fair Value:JP¥211.168.6% undervalued
4 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
360 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
207 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
231 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


