
Advertisement
- Brazil
- /
- Consumer Durables
- /
- BOVESPA:EVEN3
These Metrics Don't Make Even Construtora e Incorporadora (BVMF:EVEN3) Look Too Strong
Ignoring the stock price of a company, what are the underlying trends that tell us a business is past the growth phase? A business that's potentially in decline often shows two trends, a return on capital employed (ROCE) that's declining, and a base of capital employed that's also declining. This indicates the company is producing less profit from its investments and its total assets are decreasing. And from a first read, things don't look too good at Even Construtora e Incorporadora (BVMF:EVEN3), so let's see why.
Understanding Return On Capital Employed (ROCE)
Just to clarify if you're unsure, ROCE is a metric for evaluating how much pre-tax income (in percentage terms) a company earns on the capital invested in its business. Analysts use this formula to calculate it for Even Construtora e Incorporadora:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.042 = R$153m ÷ (R$4.9b - R$1.2b) (Based on the trailing twelve months to June 2020).
Therefore, Even Construtora e Incorporadora has an ROCE of 4.2%. In absolute terms, that's a low return but it's around the Consumer Durables industry average of 5.0%.
View our latest analysis for Even Construtora e Incorporadora
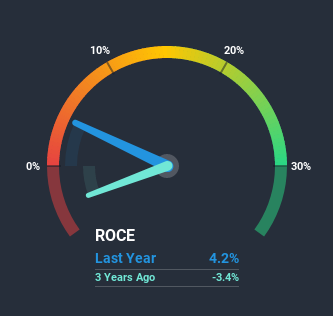
Above you can see how the current ROCE for Even Construtora e Incorporadora compares to its prior returns on capital, but there's only so much you can tell from the past. If you're interested, you can view the analysts predictions in our free report on analyst forecasts for the company.
What Does the ROCE Trend For Even Construtora e Incorporadora Tell Us?
There is reason to be cautious about Even Construtora e Incorporadora, given the returns are trending downwards. Unfortunately the returns on capital have diminished from the 5.4% that they were earning five years ago. On top of that, it's worth noting that the amount of capital employed within the business has remained relatively steady. Since returns are falling and the business has the same amount of assets employed, this can suggest it's a mature business that hasn't had much growth in the last five years. If these trends continue, we wouldn't expect Even Construtora e Incorporadora to turn into a multi-bagger.
The Bottom Line
In summary, it's unfortunate that Even Construtora e Incorporadora is generating lower returns from the same amount of capital. Yet despite these poor fundamentals, the stock has gained a huge 385% over the last five years, so investors appear very optimistic. In any case, the current underlying trends don't bode well for long term performance so unless they reverse, we'd start looking elsewhere.
One more thing to note, we've identified 2 warning signs with Even Construtora e Incorporadora and understanding them should be part of your investment process.
While Even Construtora e Incorporadora isn't earning the highest return, check out this free list of companies that are earning high returns on equity with solid balance sheets.
When trading Even Construtora e Incorporadora or any other investment, use the platform considered by many to be the Professional's Gateway to the Worlds Market, Interactive Brokers. You get the lowest-cost* trading on stocks, options, futures, forex, bonds and funds worldwide from a single integrated account. Promoted
Valuation is complex, but we're here to simplify it.
Discover if Even Construtora e Incorporadora might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisThis article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
*Interactive Brokers Rated Lowest Cost Broker by StockBrokers.com Annual Online Review 2020
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com.
MI

The Foxhole
Nvidia's (NVDA) record profit had a US$7.8 billion catch. That chunk came from betting on its own customers, not from selling its chips.
137
JA

Jake_Merritt
The circularity worth examining is not the mark-to-market line. A large and growing share of Nvidia's revenue comes from companies funded by venture capital, and Nvidia participates in some of those rounds. That is the loop. The paper gains are just an accounting reflection of it, so focusing on them means arguing about the mirror rather than the room.
NA
nadia_y3d8i
Hyperscalers grew 13% sequentially, the other AI segment grew 25% and 138% year on year. The faster half is the funded half. AI venture funding was over 400 billion in the first half with about 70% spent on compute. That is an interesting composition shift like I mentioned yesterday.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
00
About BOVESPA:EVEN3
Even Construtora e Incorporadora
Operates as a real estate developer and builder in Brazil.
Reasonable growth potential with adequate balance sheet and pays a dividend.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.5% undervalued
57 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
55 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11633.7% undervalued
12 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
QU


QuanD on UiPath ·
One of the first real AI-native winners
Fair Value:US$21.5414.9% undervalued
42 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
MA

martyw on Capcom ·
Insert Coin to Continue: The Investment Case for Capcom
Fair Value:JP¥4.3k3.3% undervalued
10 followersusers have followed this narrative
2 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TI


TickerTickle on Airbnb ·
Airbnb (ABNB): Still one of the most interesting bets in travel
Fair Value:US$181.841.4% overvalued
72 followersusers have followed this narrative
8 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.6% undervalued
366 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9120.3% overvalued
213 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0946.1% undervalued
236 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


