
Last Update 09 Aug 26
Fair value Decreased 20%INUV: AI Monetization And Restructuring Will Support Future Upside Potential
Analysts have reduced the Inuvo price target by about $0.93 to reflect lower fair value estimates, weaker near term revenue and margin assumptions, and a higher implied future P/E, citing recent price target cuts and rating changes that focus on traffic headwinds and the timing of IntentKey monetization.
Analyst Commentary
Recent research on Inuvo highlights a mix of optimism around the IntentKey platform and concern about current execution, especially following weak Q1 results and business restructuring. Price targets have generally moved lower, and ratings have shifted as analysts reassess the balance between long term potential and near term financial pressure.
Bullish Takeaways
- Bullish analysts still see IntentKey as well positioned to gain share within its market, which they view as a core driver for Inuvo's longer term growth case.
- Some research points to a clearer path to sustainable growth and profitability despite the company now operating at a smaller scale.
- Where Buy ratings are maintained, analysts are effectively signaling that current valuation already reflects near term headwinds and that successful IntentKey monetization could support higher value over time.
- Supportive views emphasize that recent restructuring is intended to improve the business model and margin profile once execution stabilizes.
Bearish Takeaways
- Bearish analysts have cut ratings to Hold and reduced price targets, citing weak Q1 performance and misses across most tracked metrics, which weighs on confidence in near term execution.
- Traffic issues tied to Platform revenues are flagged as a key risk that could limit revenue and margin recovery even if IntentKey grows as expected.
- The investment case beyond 2026 is described as heavily dependent on management's ability to monetize IntentKey and stabilize margins, which introduces execution risk to the equity story.
- Lower price targets that now sit in the US$2.50 to US$4 range reflect concern that current financial weakness and business restructuring may continue to pressure Inuvo's valuation until clearer signs of improvement appear.
What’s in the News for Inuvo
- Inuvo reported a successful IntentKey pilot with a large U.S. health insurer that helped target net new consumers earlier in the enrollment cycle and was associated with improved year over year enrollment during the most recent open enrollment period. Source: Company product related announcement.
- The same health plan pilot identified four distinct consumer need states, including active plan shoppers and cost sensitive shoppers. Inuvo highlights these need states as a basis for more tailored messaging and advertising strategies. Source: Company product related announcement.
- Inuvo announced the expansion of IntentKey signal intelligence into workforce recruitment marketing. The company is positioning recruitment as a dedicated use case that applies its AI audience insights to help employers reach specialized and hard to find talent. Source: Company product related announcement.
- The recruitment initiative is framed against U.S. employer spending of an estimated US$7.5b to US$9.5b each year on recruitment marketing, with larger enterprises alone estimated at US$1.2m to US$3.2m per year. It is presented as a way to identify candidates earlier than traditional job board driven methods. Source: Company product related announcement citing industry data.
- Inuvo filed a follow on equity offering totaling approximately US$2.97m, including 1,631,121 shares of common stock priced at about US$1 per share and 1,337,693 pre funded warrants priced at about US$0.999 per warrant, each with a stated discount of US$0.06 per security. Source: Follow on equity offering filing.
Valuation Changes for Inuvo
- Fair Value has been lowered from $4.55 to $3.63, which represents a significant cut to the underlying valuation estimate for Inuvo.
- Discount Rate has moved slightly lower from 9.12% to about 9.02%, indicating only a very small change in the required rate of return used in the model.
- Revenue Growth assumptions have fallen from a decline of 22.26% to a deeper decline of 24.88%, pointing to softer expectations for dollar revenue trends.
- Net Profit Margin has been reduced from 12.04% to 2.91%, which meaningfully lowers the profitability assumed in future dollar earnings.
- Future P/E has risen sharply from 18.18x to about 84.74x, implying that the updated valuation framework now uses a much higher multiple on projected earnings.
Key Takeaways
- Accelerating adoption of Inuvo's privacy-focused, AI-driven platform positions the company for scalable, high-margin, and sustainable revenue growth in a shifting digital advertising landscape.
- Investments in compliance, direct client relationships, and omnichannel solutions enhance operational efficiency, client retention, and profitability amid expanding industry demand.
- Sustained unprofitability, heavy reliance on few partners, margin compression, competitive threats, and rapid industry changes all undermine Inuvo's revenue stability and long-term prospects.
Catalysts
About Inuvo- An advertising technology and services company, develops and commercializes large language generative artificial intelligence that discovers and targets digital audiences in the United States.
- Accelerating adoption of the self-serve IntentKey platform-evidenced by a 300% quarter-over-quarter increase in new deals-positions Inuvo to drive high-margin, scalable revenue growth as more clients expand their spend and mature on the platform.
- Inuvo's privacy-compliant, concept-based AI targeting receives strong validation from both independent AI assessments and client feedback, establishing the platform as a differentiated solution in a market increasingly prioritizing privacy-first digital advertising, which should support both revenue growth and enhanced net margins.
- Structural investments in compliance, transparent reporting, and content scalability (including rapid, AI-powered content creation and vertically specialized sites) prepare Inuvo to capitalize on industry trends favoring quality, compliant suppliers, likely translating to increased client acquisition, retention, and higher gross profits.
- Expansion of direct client relationships and new demand-side platform integrations reduce reliance on third-party intermediaries, set the stage for international growth, and improve operating leverage, which collectively should boost gross margins and earnings stability.
- The rapid growth in digital advertising budgets and ongoing industry transition to programmatic, omnichannel, and CTV channels (where Inuvo is seeing increasing success and higher margins) expands the company's addressable market and supports long-term, compounding revenue growth.
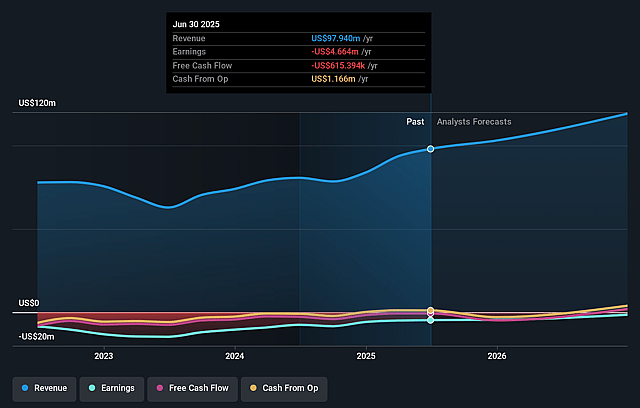
Inuvo Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Inuvo's revenue will decrease by 24.9% annually over the next 3 years.
- Analysts assume that profit margins will increase from -2.9% today to 2.9% in 3 years time.
- Analysts expect earnings to reach $831.4 thousand (and earnings per share of -$0.06) by about August 2029, up from -$1.9 million today.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 87.7x on those 2029 earnings, up from -7.9x today. This future PE is greater than the current PE for the US Software industry at 32.5x.
- Analysts expect the number of shares outstanding to grow by 1.54% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 9.02%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Despite robust top-line growth, Inuvo remains unprofitable with persistent operating and net losses; ongoing high operating costs, compressed gross margins from shifts in product mix, and limited liquidity reserves may continue to impact future earnings and restrict reinvestment, reducing long-term profitability.
- The company's growth is heavily reliant on a small number of large platform partners and a nascent, unproven self-serve client base, which exposes it to significant revenue volatility in the event of partner churn or slow adoption of new services, threatening revenue stability.
- Gross margin declined notably year-over-year (from 84% to 75.4%) due to increased cost of revenue and scaling of new campaigns with lower margin structures, indicating pressure on profitability even as revenues rise; continued downward pricing or unfavorable product mix could further compress net margins.
- Competition from tech giants with deeper resources (Google, Meta, Amazon) and industry consolidation pose long-term risks; barriers to scaling brand awareness and limited sales capacity restrict Inuvo's ability to capture market share, pressuring both revenue growth and margin expansion.
- The rapid evolution of the adtech industry, including further privacy regulation, browser changes (e.g., cookie deprecation), and shifts to new AI-driven or LLM-based search platforms, presents uncertainty; slow adaptation or loss of technical relevance could diminish the effectiveness of Inuvo's technology, directly impacting future revenues and earnings.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of $3.62 for Inuvo based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $4.0, and the most bearish reporting a price target of just $2.5.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $28.6 million, earnings will come to $831.4 thousand, and it would be trading on a PE ratio of 87.7x, assuming you use a discount rate of 9.0%.
- Given the current share price of $1.03, the analyst price target of $3.62 is 71.6% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Inuvo?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

AI Contextual Targeting Will Expand Global Digital Markets
View narrative
Tight Privacy Rules Will Hinder Progress Yet AI Offers Hope
View narrative
Inuvo, Inc. – AI-Powered Programmatic Advertising Integration with FreeWheel
View narrative