
Advertisement
- United States
- /
- Electric Utilities
- /
- NYSE:ES
Is Eversource Energy (ES) Fairly Valued As Its Electrification Growth Story Plays Out?
Eversource Energy (ES) drew fresh attention after its recent share move, with the stock down about 1.5% on the day and modestly lower over the past month.
At around US$70.44 per share, Eversource Energy has seen short term momentum cool after a recent 1 day share price decline. However, a modest 90 day share price gain and double digit 1 year total shareholder return suggest sentiment has improved over a longer stretch.
Compare Eversource Energy's recent swing with a curated group of utilities and infrastructure players by scanning the 39 power grid technology and infrastructure stocks for ideas that follow similar grid and energy themes.
Bulls view Eversource Energy’s recent 1-year gain as evidence that the reset is largely complete. Bears, however, focus on the latest dip and potential valuation risk. Which side does the current pricing appear to support next?
Most Popular Narrative: 4.9% Undervalued
Eversource Energy's most followed narrative pegs fair value at about $74.08, a touch above the recent $70.44 close. This frames the current debate neatly.
Rising electricity demand from the rapid electrification of transportation and heating is expected to drive consistent long-term load growth for Eversource, directly supporting sustained revenue increases as regulatory-approved investments expand the company's rate base.
Want to understand why this narrative still sees upside in Eversource Energy at today's price? It leans heavily on carefully paced revenue growth, a gradual rebuild in margins, and a future earnings multiple that sits below what many peers trade on. The real twist is how those ingredients combine with a specific discount rate to land on that $74.08 fair value.
Result: Fair Value of $74.08 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative around Eversource Energy can crack if regulators squeeze allowed returns in Connecticut, or if planned asset sales and storm cost securitization stall.
Find out about the key risks to this Eversource Energy narrative.
Another Take On Eversource Energy’s Value
The earlier narrative leans on analyst forecasts and a P/E framework that suggests Eversource Energy looks about 4.9% undervalued around $70.44. Our DCF model presents a stricter comparison, with an estimated future cash flow value of $58.79, which implies the shares appear overvalued on that basis.
This gap matters. A P/E view focuses on earnings and relative pricing, while a discounted cash flow view emphasizes long run cash generation and the discount rate. When those two tools disagree, it raises a straightforward question for investors: Which set of assumptions feels more realistic for Eversource Energy right now?
Look into how the SWS DCF model arrives at its fair value.
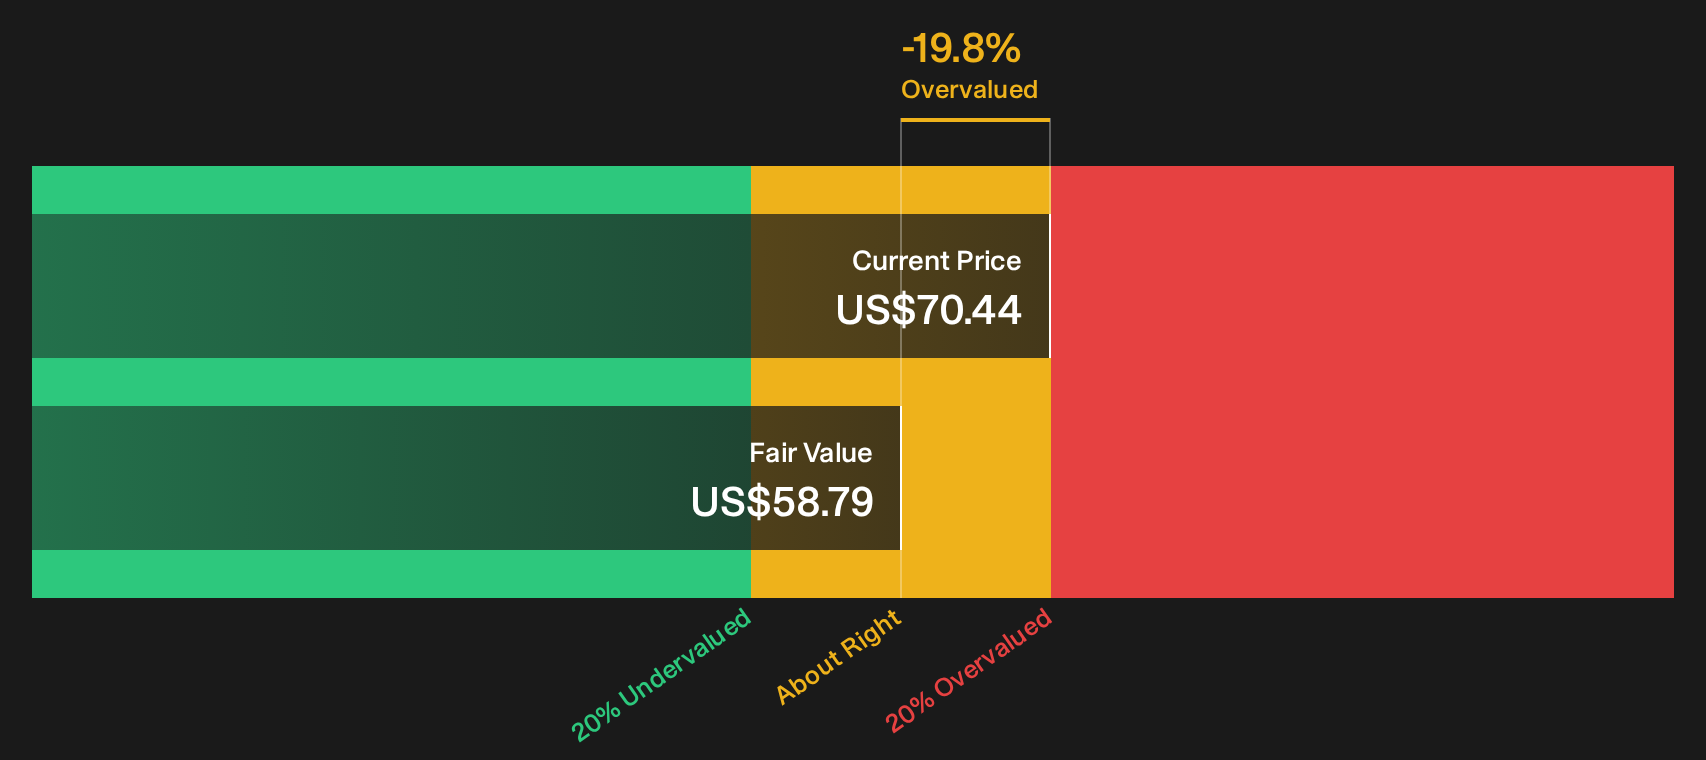
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eversource Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 49 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Eversource Energy is clearly split. Move quickly, stress test the assumptions that matter most to you, and then weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Eversource Energy?
If you stop here, you only see part of the opportunity set. Put Eversource Energy in context by scanning other ideas with the Simply Wall Street Screener.
- Target resilience by checking companies that prioritise financial strength and consistent fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a reasonable price by reviewing the 49 high quality undervalued stocks that pair strong fundamentals with appealing valuations.
- Focus on stability and income potential by scanning the 6 dividend fortresses that combine higher yields with robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Eversource Energy might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Razors, glasses, mattresses, all toppled by direct-to-consumer upstarts. Beer wasn't. A 90-year-old law is why.
1010
s
sarah_c5otv
Forget beer. Wine volume is down the drain and it has direct-to-consumer shipping in most states. The category with the freest distribution is falling fastest.
artoflosing
Funny. Beer sales aren't growing anymore. A toll booth in a shrinking market may not be a great choice to invest.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NYSE:ES
Eversource Energy
A public utility holding company, engages in the energy delivery business.
Established dividend payer with proven track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2536.2% undervalued
186 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4934.6% undervalued
33 followersusers have followed this narrative
2 commentsusers have commented on this narrative
9 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.9% undervalued
25 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
ES

Esteban on ExlService Holdings ·
Five years of mix shift into AI-led work has produced no gross margin expansion, and contracts are terminable without cause.
Fair Value:US$18.489.9% overvalued
3 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on AeroVironment ·
AVAV | AeroVironment: What They Said vs. What They Did
Fair Value:US$103.9435.5% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FU


FundamentalFlow on Vistra ·
US Energy Giant: PowerHouse Of The Future Of AI
Fair Value:US$299.9849.6% undervalued
23 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.1% undervalued
1403 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.8% undervalued
1620 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.7% undervalued
1595 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
