
Advertisement
- United States
- /
- Wireless Telecom
- /
- NYSE:AD
A Look At Array Digital Infrastructure (AD) Valuation After Special Dividend And Spectrum Sale To AT&T
Special dividend and spectrum sale set the stage
Array Digital Infrastructure (AD) is back on investors’ radar after closing a US$1.018b sale of spectrum licenses to AT&T and declaring a US$10.25 per share special cash dividend tied to that deal.
See our latest analysis for Array Digital Infrastructure.
Despite the special dividend news, Array Digital Infrastructure’s share price has come under pressure, with a 1-day share price return showing a 20.5% decline and a 7-day share price return showing a 17.09% decline. Longer term, total shareholder returns of 31.84% over one year and about 2.4x over three years indicate earlier momentum that has recently cooled.
If this type of corporate action has you reconsidering where growth could come from next, it may be a good moment to check out fast growing stocks with high insider ownership as potential new ideas.
With a US$10.25 per share special dividend, a recent share price drop, and a US$47.92 last close, the key question is whether Array Digital Infrastructure now offers value or if the market is already pricing in future growth.
Most Popular Narrative: 17% Undervalued
With Array Digital Infrastructure last closing at $47.92 against a widely followed fair value estimate of about $57.71, the main narrative sees meaningful upside still on the table under its modeled assumptions.
The analysts have a consensus price target of $80.75 for United States Cellular based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $85.0, and the most bearish reporting a price target of just $72.0.
Curious what kind of revenue reset, margin profile and future earnings multiple are being baked in to reach that fair value line? The narrative leans on a sharp shift in profitability and a premium earnings valuation that is usually reserved for faster growing names. If you want to see exactly how those assumptions stack up year by year, the full story lays out the math behind that $57.71 figure.
Result: Fair Value of $57.71 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, the whole story could shift if regulatory approvals on spectrum transactions take longer than expected or if competition from larger carriers continues to pressure service revenues.
Find out about the key risks to this Array Digital Infrastructure narrative.
Build Your Own Array Digital Infrastructure Narrative
If you look at the numbers and come to a different conclusion, or prefer building your own view from scratch, you can create a tailored thesis in a few minutes with Do it your way.
A great starting point for your Array Digital Infrastructure research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
Looking for more investment ideas?
If you stop with one stock, you miss the bigger picture, so use the Simply Wall Street Screener to uncover fresh ideas that actually fit your style.
- Zero in on potential mispricings by scanning these 867 undervalued stocks based on cash flows that align with your view on cash flows and business quality.
- Explore opportunities in digital assets by filtering for companies tied to these 18 cryptocurrency and blockchain stocks and business models built around blockchain use cases.
- Investigate emerging tech themes by focusing on these 23 quantum computing stocks that are working on hardware, software, or infrastructure for quantum computing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
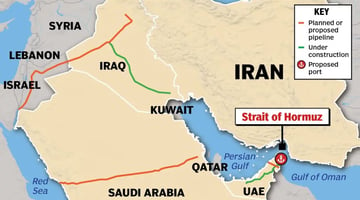
Everyone's watching the oil price. The harder problem is the gas that can't take a detour.
178
R
Rob_Curious
What I've learnt in the last six months is that fuel supply disruption is a real portfolio risk, and one of the better hedges is a small allocation to shipping. Though it's insane how much these have run up this year.
f
frank_ub3n0
Spot on. Shipping and logistics is much larger constraint for gas than oil. Sorry to break it to you. No quick fixes for that.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
63
About NYSE:AD
Array Digital Infrastructure
Owns and operates shared wireless communications infrastructure in the United States.
Good value with acceptable track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CL


Clive_Thompson on Upside Gold ·
Upside Gold - New Technical Report Expected in Q1 2027 Could Re-Rate The Stock.
Fair Value:CA$1.552.7% undervalued
2 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8829.7% undervalued
35 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.8% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8532.0% undervalued
25 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Montage Gold ·
Montage Gold, Building West Africa’s Next 300Koz Producer, First Pour Late 2026, 5.88Moz Resource
Fair Value:CA$23.510.1% undervalued
18 followersusers have followed this narrative
5 commentsusers have commented on this narrative
1 likeusers have liked this narrative
OO

OOO97 on Vistra ·
VST is a conservative way to Ride America´s Hunger for AI Energy Demand (slightly undervalued at 140, estimated 171)
Fair Value:US$17117.7% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
GE


Genious_Trades on TOYO ·
The $14 Disconnect: Why the Market is not Correctly Pricing TOYO’s U.S. Solar Expansion
Fair Value:US$1570.6% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.6% undervalued
1485 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8918.3% undervalued
1647 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.4% undervalued
1663 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


AN

anthony_x0j2w on Platform Group SE KGaA ·
Hello,(I am a shareholder).I spent the summer investigating in whatever I was able to find in the press, the trustee, or legal, and comparing it to FS Benner's declaration/transcripts:press: MM has a tendancy to use facts, modify them and turn them the way they want: 100% of their claims against TPG0 is traçable factually, 80% is flawed and interpreted. Example are numerous: 11M loans banks to be paid seems right, but it has not been an issue at all, it has been paid in full. (and it happens all the time in every business...); the previous HR becoming a financial director in the article herself being attacked by TPG on the legal side; the wrong address of curator (if truly announced by TPG).Trustee: according to my research (which can be incomplete) no communication to the Nordic trustee (hereby, bond holders) has been done on a, indebtedness (late payment) > 1M€, which is their obligation by contract (clause 14.d - https://corporate.the-platform-group.com/bond/) => this is a sign of a huge lie and fraud, or the sign that there is no indebtedness > 1M€ over the whole TPG group.Legal: still awaiting for an answer, probable that I won't get it.VALUATIONYou can spent hours working the fundamentals, if they're flawed...the thesis falls.Anyway, I always substracts the badwill (that I consider non-current - you have it in the CFS) & non-controlling interests from my valuation:Earnings ~22MFCF ~40M€The financial statements are not the issue here, we are more on an cheap option on the sincerity of the accounts that a real valuation. Unfortunately, these are unverifiable elements, hence the low price./!\ Careful:the accounts are consolidated and skip the subsidiaries issues...Careful with the business model: TPG0 is a financial holding that acquire subsidiaries, hold the debt, and has no operations. 100% of the Cash Flow comes from subs' dividends => it is a risk here, more a plumber risk than an operational one, but nevertheless...The auditor is too small, and managed by the same firm than before, with 140K€/year commission => it's too low, nobody external really reviewed what Benner and his team are doing internallycapital increase do not go through the CFS, but through change in equity AND equity in the BSIf the equity stays low too long, the WACC increase will be unbearable (I have a 30% global, with a 118% on equity): diluting is expensive => TPG machine can stay broken for a while.Most of the people I talk with never saw this, while this is ESSENTIAL to Benner's business model.SEVERAL EVENTS THAT COULD CHANGE:AEP is being audited by KPMG: if Benner plays the "we will propose KPMG to our shareholders BEOY", this can increase the trust in him significantly/KPMG (or other) to validate the 2026 IFRS accounts & having a word on HGB's: though still consolidated, at least we'll know...AEP being eventually acquired: while it carries a high integration risk due to its size, they talked about it so many times, that trust goes with it.Without this combination of event, the equity is doomed to stay at this level, IMO.Do not forget to also follow the bond: with TPG's announced safe harbor plan for buyback (25% of daily exchange), it is also interesting to check this illiquid and retail market: https://live.deutsche-boerse.com/bond/no0013256834-the-platform-group-ag-8-875-24-28?mic=XFRA
1
|0