
Advertisement
- United States
- /
- Communications
- /
- NasdaqGM:OCC
Optical Cable (OCC) Stock Flatlines Despite Sharper Earnings And Rich P E
Optical Cable stock closed flat at US$13.70, even after a quarter that materially lifted earnings power. Traders did not bid the price up, yet Q3 net income reached US$1.9 million and basic earnings per share came in at US$0.23, a clear step up from recent history. The real story now sits in the time horizon you choose. In the short term, the chart looks bruised after a 41% slide over three months. Over a longer stretch, the conversation shifts to whether this fresh profitability can justify a P/E of 47.2x.
Is Optical Cable trading on fragile momentum or on earnings power the market has not fully priced in yet? See how the P/E, margins, and cash flows line up in the valuation analysis for Optical Cable.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$24.3m vs. US$19.9m (up about 22% year over year)
- Net Income (Q3 2026 vs. Q3 2025): US$1.86m vs. US$0.30m (moved from modest profit to materially higher profitability)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.23 per share vs. US$0.04 per share (earnings per share increased several times year over year)
- Gross Margin (Q3 2026 vs. Q3 2025): 37.4% vs. 31.7% (margin improved by roughly 5.7 percentage points)
Prefer clean charts over another dense wall of financial text? See a full visual breakdown of Optical Cable’s valuation story at a glance in the company report for Optical Cable.
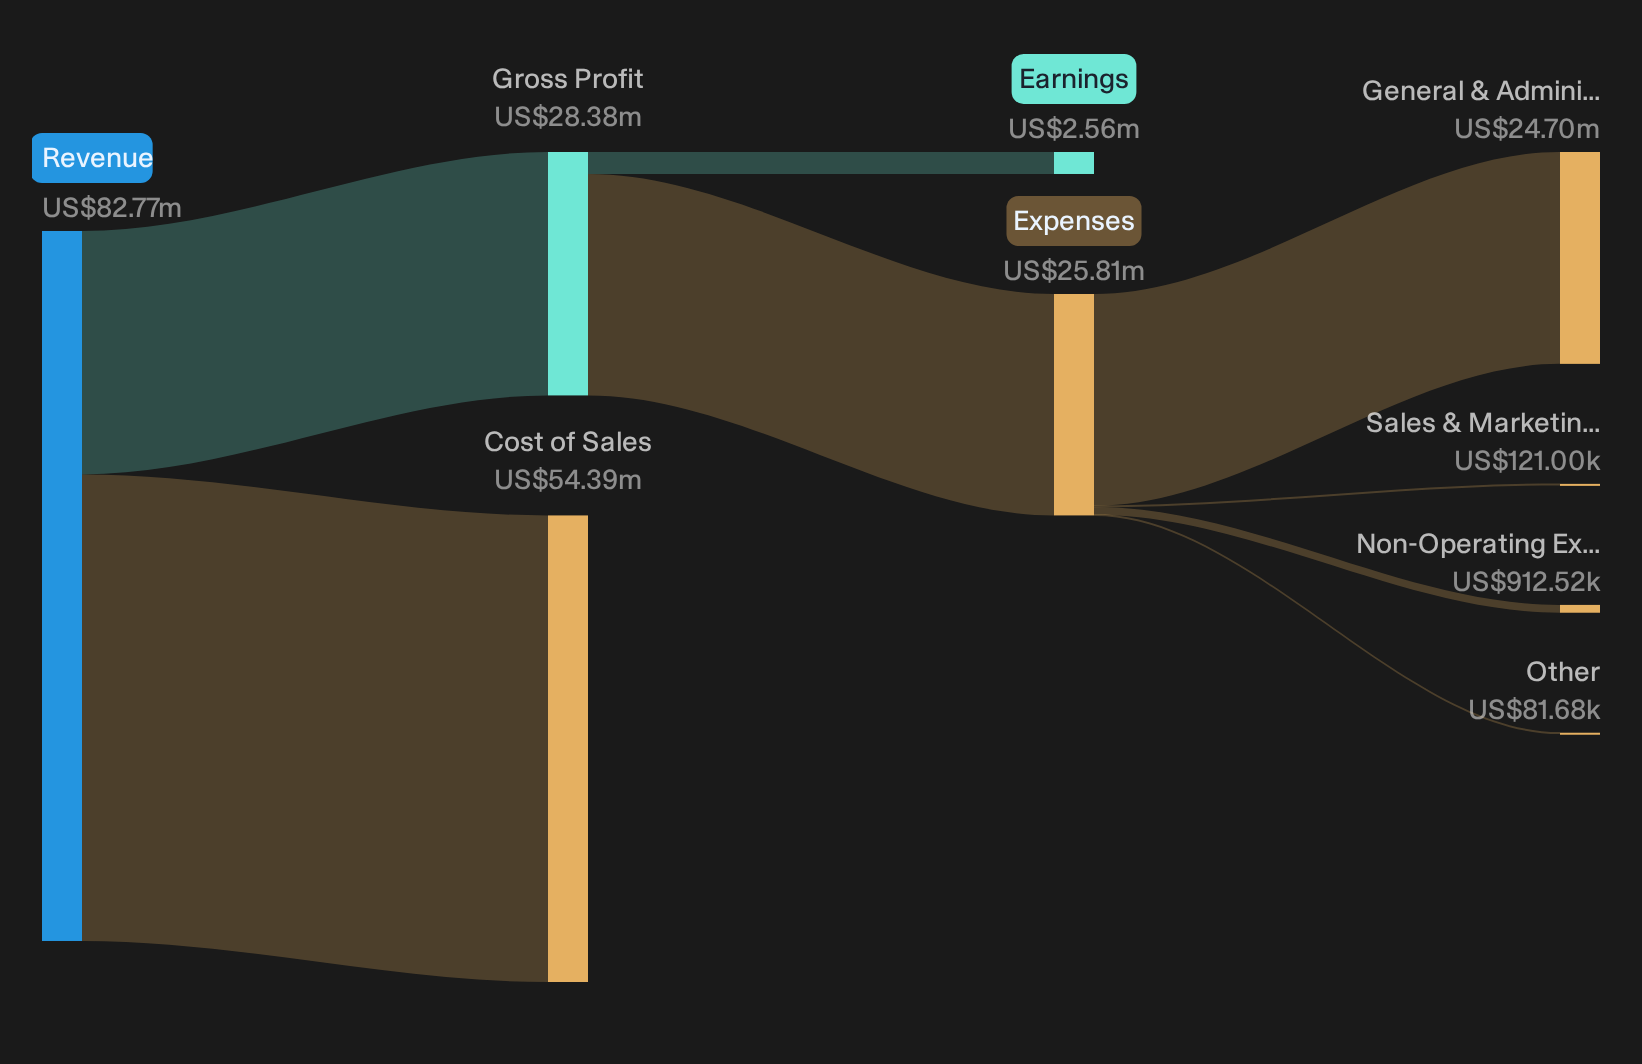
Optical Cable bullish story gains some backing
For a cautiously optimistic view on Optical Cable, the earnings tape helps. Revenue for Q3 and the first nine months moved higher at a double digit pace, and gross margin stepped up from roughly 31% to the mid 30s. That shift pushed the business from a year to date loss to a profit. A larger backlog and forward load, spread across enterprise, data center and specialty demand, also fits the idea of a physical infrastructure supplier with reasonably broad end markets.
Bear case still flags real but narrower risks
Bears focus on small scale, competitive pressure and operational bottlenecks. Recent results soften some of that argument. Higher volumes, better manufacturing leverage and a year to date move into the black reduce immediate concern around basic profitability. The risk list is not short though. Fiber shortages, longer data center qualification cycles and heavier SG&A as a share of sales all keep execution risk live, especially after a 41% share price decline over 90 days.
Review Optical Cable’s recent volatility and insider selling in context. Expose potential structural weak points through the detailed risk analysis for Optical Cable which shows 2 important warning signs.Stay Ahead Of Your Next Move
Q3’s stronger earnings and a 41% share price slide make Optical Cable a candidate you may want to track closely, so register for free with Simply Wall St and add it to a Watchlist to follow price versus fair value and watch for a preferred entry point. After you buy or if you already hold it, use the Portfolio Command Center to cut through noise and focus on the key updates that matter for your thesis. For a longer view, tap into crowd sentiment and different angles on Optical Cable through the Community to see what other investors are watching. By surfacing potential catalysts and risks early, you put yourself in a stronger position to act before the market fully reacts.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Once a theme breaks out, the best entry points get caught and prices start flying. Check these under the radar lists while it matters and act now.
- Spot resilient opportunities before volatility bites by scanning 80 resilient stocks with low risk scores, built to surface companies where balance sheets and risk scores point to staying power while others are still dropping.
- Track the AI build out from the shovel side by using 56 AI infrastructure stocks to follow suppliers and enablers that could catch momentum as demand accelerates.
- Review income ideas that work harder by using 6 dividend fortresses, curated for higher yielding payers that may keep cash returns central to the investment story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Razors, glasses, mattresses, all toppled by direct-to-consumer upstarts. Beer wasn't. A 90-year-old law is why.
910
s
sarah_c5otv
Forget beer. Wine volume is down the drain and it has direct-to-consumer shipping in most states. The category with the freest distribution is falling fastest.
artoflosing
Funny. Beer sales aren't growing anymore. A toll booth in a shrinking market may not be a great choice to invest.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NasdaqGM:OCC
Optical Cable
Manufactures and sells fiber optic and copper data communications cabling and connectivity solutions primarily for the enterprise market in the United States and internationally.
Flawless balance sheet with acceptable track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2536.2% undervalued
187 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4934.6% undervalued
32 followersusers have followed this narrative
2 commentsusers have commented on this narrative
9 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.9% undervalued
24 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
FU


FundamentalFlow on Vistra ·
US Energy Giant: PowerHouse Of The Future Of AI
Fair Value:US$299.9849.6% undervalued
23 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
MA


MarkoVT on ANYCOLOR ·
Near zero debt, Japan centric focus provides future growth
Fair Value:JP¥4.05k29.6% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TH

The_Dutch_Investors on ASML Holding ·
ASML is Perhaps Europe’s Best Business, But Not at Any Price.
Fair Value:€1.01k48.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.1% undervalued
1402 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.8% undervalued
1618 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.7% undervalued
1593 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
