
Advertisement
- United States
- /
- Communications
- /
- NasdaqGS:CSCO
Assessing Cisco Systems (CSCO) Valuation After Recent Share Price Pullback Without Clear News Catalyst
Cisco Systems stock moves without a clear news catalyst
Cisco Systems (CSCO) shares have been moving without a clear single event driving sentiment, which can prompt investors to look more closely at the company’s recent returns and financial profile.
See our latest analysis for Cisco Systems.
Cisco’s recent share price pullback, including a 5.55% 1 month share price return and 3.09% year to date share price return, contrasts with a stronger 21.29% 1 year total shareholder return and 65.98% 3 year total shareholder return. This hints at cooling short term momentum against a broader record of gains.
If this kind of shift in sentiment has you rethinking your watchlist, it could be a good moment to widen your radar with high growth tech and AI stocks.
With Cisco trading at $73.69 and sitting at an estimated 12.09% intrinsic discount and 16.70% below its US$85.999 price target, you have to ask: is this a genuine entry point, or is the market already factoring in future growth?
Price-to-Earnings of 28.2x: Is it justified?
At a last close of US$73.69, Cisco is trading on a P/E of 28.2x, which screens as good value both against its own fair ratio and its peers.
The P/E multiple compares Cisco’s share price to its earnings per share, so it is a quick way to see how much investors are paying for each dollar of profit.
CSCO is flagged as good value based on its P/E of 28.2x versus an estimated fair P/E of 29.8x, which suggests the market price is slightly below the level the fair ratio model points to. Cisco also has high quality earnings and a Return on Equity of 22%, which can help explain why the earnings multiple is not at a steep discount.
Against the broader US Communications industry, Cisco’s 28.2x P/E is described as good value both versus the industry average and the peer average of 35.6x, so the stock changes hands at a lower earnings multiple than many comparable companies even after a strong multi year total return profile.
Explore the SWS fair ratio for Cisco Systems
Result: Price-to-Earnings of 28.2x (UNDERVALUED)
However, you also have to weigh risks such as slower revenue growth at 5.25% annually, as well as the possibility that tech hardware spending cycles cool sentiment further.
Find out about the key risks to this Cisco Systems narrative.
Another View: What Our DCF Model Suggests
Cisco screens as good value on its 28.2x P/E, and our DCF model also points to undervaluation, with the shares at US$73.69 versus an estimated future cash flow value of US$83.82. That is roughly a 12% gap, which raises a simple question: is the market being too cautious about Cisco’s cash generation?
Look into how the SWS DCF model arrives at its fair value.
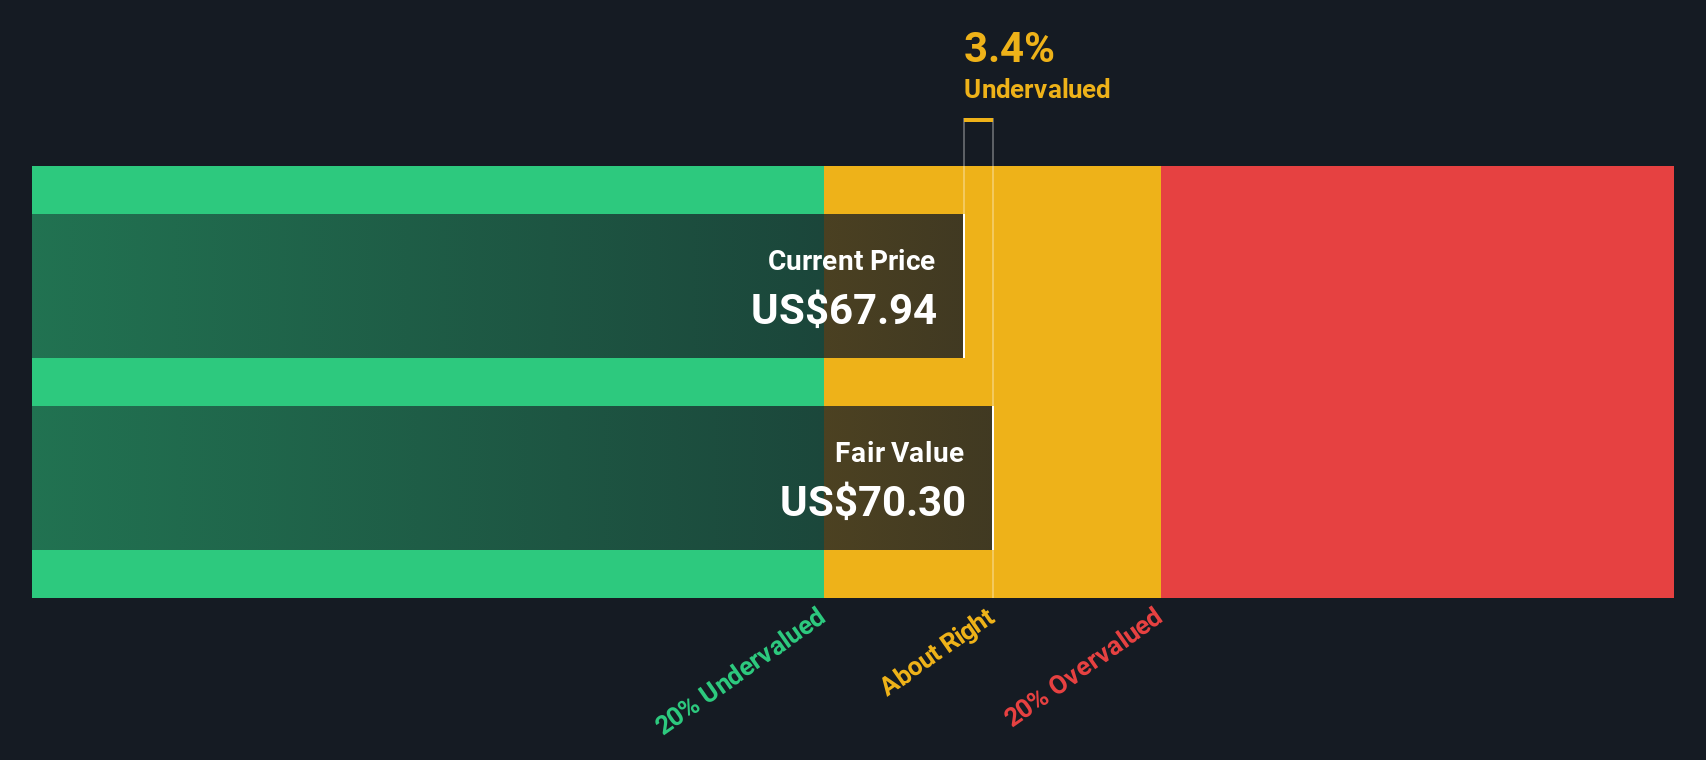
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cisco Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 883 undervalued stocks based on their cash flows. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Build Your Own Cisco Systems Narrative
If you see the numbers differently or want to rely on your own view of Cisco, you can build a complete story in just a few minutes with Do it your way.
A great starting point for your Cisco Systems research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
Looking for more investment ideas?
If you are serious about building a stronger portfolio, do not stop at one company. Use the Simply Wall St Screener to spot fresh ideas before others notice them.
- Target growth potential early by reviewing these 3528 penny stocks with strong financials that already show stronger financials than many expect at this end of the market.
- Tap into long term tech themes by scanning these 24 AI penny stocks that are tied to artificial intelligence trends across multiple sectors.
- Focus on price and quality together by sifting through these 883 undervalued stocks based on cash flows that our models flag as trading below their estimated cash flow value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
What's Uber worth in a world where nobody drives for it? Possibly more, not less.

1211
f
frank_ub3n0
The aggregator argument works when supply is fragmented and interchangeable. Uber's driver-side power comes from millions of individuals with no coordination and no bargaining position. With autonomous fleet, the inverse. It will be a nightmare for Uber,
a
alberto_gztam
Car manufactoring and rides are two very different bussinesses. Uber can choose the best car make, that not necesarily would be tesla. Also, most countries and cities are not keen on just letring driverless taxis around... regulations block this for now.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About NasdaqGS:CSCO
Cisco Systems
Designs, develops, and sells technologies to power, help, secure, and draw insights from the internet in the Americas, Europe, the Middle East, Africa, the Asia Pacific, Japan, and China.
Very undervalued with solid track record and pays a dividend.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
59 followersusers have followed this narrative
1 commentusers have commented on this narrative
13 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17014.4% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.6% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
16 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.9% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on Smith & Wesson Brands ·
SWBI | Smith & Wesson Brands, Inc.: What They Said vs. What They Did
Fair Value:US$9.2233.1% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
NI

nitram on First Interstate BancSystem ·
Solid, rationally run company will provide consistent results, stable dividend, and moderate growth
Fair Value:US$406.3% undervalued
12 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
DU

duarte_EM on Taiwan Semiconductor Manufacturing ·
TSMC — The Factory the AI World Runs On (Fair Value ~$400, sized for Taiwan risk)
Fair Value:US$116.49258.0% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.4% undervalued
373 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k72.8% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9121.5% overvalued
220 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
