
Advertisement
- United States
- /
- Professional Services
- /
- NasdaqGS:TASK
TaskUs (NASDAQ:TASK) Shareholders Will Want The ROCE Trajectory To Continue
If we want to find a stock that could multiply over the long term, what are the underlying trends we should look for? Firstly, we'd want to identify a growing return on capital employed (ROCE) and then alongside that, an ever-increasing base of capital employed. Put simply, these types of businesses are compounding machines, meaning they are continually reinvesting their earnings at ever-higher rates of return. Speaking of which, we noticed some great changes in TaskUs' (NASDAQ:TASK) returns on capital, so let's have a look.
Return On Capital Employed (ROCE): What Is It?
If you haven't worked with ROCE before, it measures the 'return' (pre-tax profit) a company generates from capital employed in its business. To calculate this metric for TaskUs, this is the formula:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.13 = US$99m ÷ (US$887m - US$109m) (Based on the trailing twelve months to September 2022).
So, TaskUs has an ROCE of 13%. That's a relatively normal return on capital, and it's around the 12% generated by the IT industry.
Check out the opportunities and risks within the US IT industry.
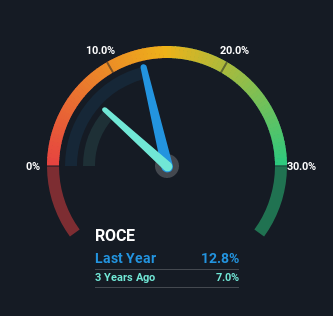
Above you can see how the current ROCE for TaskUs compares to its prior returns on capital, but there's only so much you can tell from the past. If you'd like, you can check out the forecasts from the analysts covering TaskUs here for free.
What Can We Tell From TaskUs' ROCE Trend?
Investors would be pleased with what's happening at TaskUs. The numbers show that in the last three years, the returns generated on capital employed have grown considerably to 13%. The amount of capital employed has increased too, by 39%. This can indicate that there's plenty of opportunities to invest capital internally and at ever higher rates, a combination that's common among multi-baggers.
Our Take On TaskUs' ROCE
In summary, it's great to see that TaskUs can compound returns by consistently reinvesting capital at increasing rates of return, because these are some of the key ingredients of those highly sought after multi-baggers. And since the stock has fallen 58% over the last year, there might be an opportunity here. So researching this company further and determining whether or not these trends will continue seems justified.
If you want to continue researching TaskUs, you might be interested to know about the 2 warning signs that our analysis has discovered.
If you want to search for solid companies with great earnings, check out this free list of companies with good balance sheets and impressive returns on equity.
Valuation is complex, but we're here to simplify it.
Discover if TaskUs might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
912
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
84
About NasdaqGS:TASK
TaskUs
Provides outsourced digital services for companies in Philippines, the United States, India, and internationally.
Undervalued with solid track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CL


Clive_Thompson on Upside Gold ·
Upside Gold - New Technical Report Expected in Q1 2027 Could Re-Rate The Stock.
Fair Value:CA$1.552.0% undervalued
3 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.5% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8528.7% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0625.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TI

TimLee on 3REN Berhad ·
3REN Berhad Is Powering the Semiconductor Ecosystem and Smart Manufacturing
Fair Value:RM 0.6843.4% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
KA

KASHIF_RIAZ_ on MCB Bank ·
MCB Bank: high-quality income anchor — 9% yield, cheap earnings, modest upside
Fair Value:PK₨45011.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.9% undervalued
1494 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.0% undervalued
1652 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.0% undervalued
1669 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative


