
Advertisement
- United States
- /
- Software
- /
- NasdaqGS:SNPS
Is Synopsys (SNPS) Undervalued As Morgan Stanley Turns More Bullish?
Morgan Stanley’s upgrade of Synopsys (SNPS) to Overweight has pulled fresh attention to the stock after a pullback, with the firm highlighting Ansys integration prospects and AI driven demand in semiconductor design.
Synopsys shares trade at US$397.17 after a 1-day share price return of 1.0%. However, the 90-day share price return has declined 12.5% and the year-to-date share price return is down 17.3%, while the 5-year total shareholder return of 18.42% points to momentum that has cooled recently rather than steadily building.
Scan beyond Synopsys and see how other AI focused chip design players are setting up right now using our hand picked 89 AI infrastructure stocks
Synopsys now sits well below recent highs yet still carries a premium multiple and a bullish broker call. Does that mix still skew the risk reward toward buyers, or has the easy upside already been claimed?
Most Popular Narrative: 27.1% Undervalued
Against Synopsys' last close at $397.17, the most widely followed valuation narrative pegs fair value higher, framing the recent pullback as a discount story rather than a momentum one.
The accelerating complexity and proliferation of AI, high-performance computing, and multi-die/chiplet-based architectures are increasing customer demand for Synopsys' advanced design, verification, and simulation solutions, solidifying its role as a mission-critical partner in next-generation chip and system development, supporting both revenue growth and opportunities for higher-margin recurring licensing.
Read the complete narrative. Read the complete narrative.
Want to see what is baked into that premium EDA view on Synopsys? The story focuses on compounding earnings, sturdier margins and a higher future profit multiple that assumes the market maintains strong demand for this kind of software. Curious which specific growth and profitability swing factors sit at the core of that fair value gap?
Result: Fair Value of $544.97 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Synopsys faces real pressure points, with weaker China demand and higher integration and restructuring costs both capable of quickly challenging that undervalued narrative.
Find out about the key risks to this Synopsys narrative.
Another View: Synopsys Through The P/E Lens
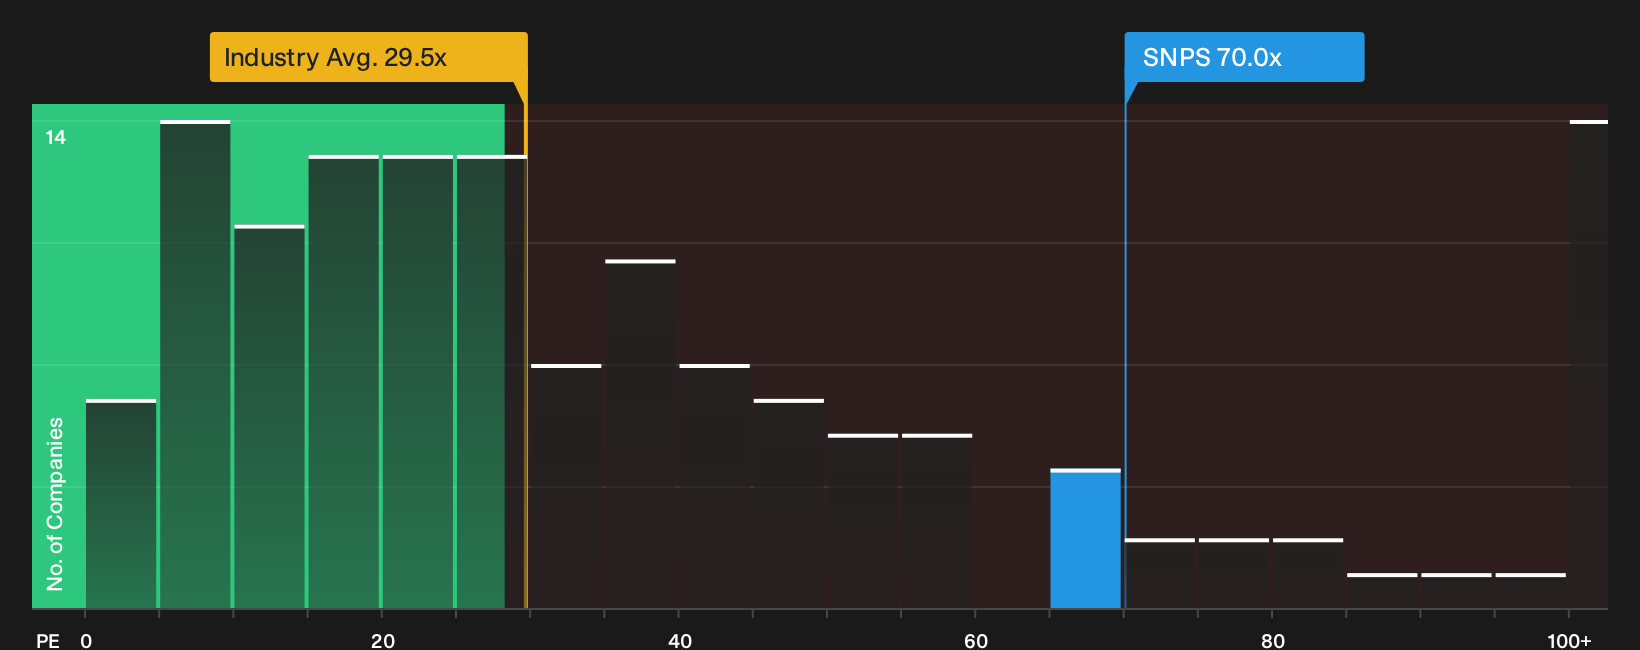
The DCF workup values Synopsys as 22.7% undervalued at $397.17, yet the P/E suggests a different picture. The stock trades around 70.7x earnings compared with about 29.5x for the wider US Software group and 31.1x for direct peers, while the fair ratio is closer to 45.5x. That gap points to notable valuation risk if sentiment cools, even if the cash flow model indicates potential upside. Which signal should serve as the anchor when the next headline hits?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages on Synopsys have you torn, act promptly and compare the potential upside with the concerns using the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Synopsys?
Do not stop at Synopsys when there are plenty of other opportunities on the table. Use the tools available and let the data do the heavy lifting for you.
- Spot potential bargains early by scanning a curated set of quality opportunities through the 17 high quality undiscovered gems.
- Prioritize resilience by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Zero in on companies that balance return potential with calmer price action through the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Oracle has $638 billion of orders it can't fill yet. Tonight tells us how much it's costing to get ready.
107
s
sean_3pk06
Sixty-eight percent gross margin business is buying its way into a thirty-five percent gross margin business, and revenue growth is the metric everyone is watching.
d
devon_jd150
This is important about Oracle. Nvidia went to six of the biggest asset managers on earth to make sure someone else held this risk. Oracle just borrowed the money and held it itself.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NasdaqGS:SNPS
Synopsys
Provides design IP solutions in the semiconductor and electronics industries.
Fair value with moderate growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2540.0% undervalued
186 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4937.2% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k17.2% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.7% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
IS

isidrohg on Micron Technology ·
Sold-Out HBM And Multi-Year Contracts Turn Micron From A Cycle Into A Contract
Fair Value:US$1.96k50.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AN


andrei9868 on Oracle ·
Oracle: The backlog is starting to show up in the P&L
Fair Value:US$22030.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
PR


prajeeshprathap on Clean Harbors ·
The Environmental Infrastructure Compounder Built for Decades of Growth
Fair Value:US$3508.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1408 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.0% undervalued
1624 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.3% undervalued
1597 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative

