
Advertisement
- United States
- /
- IT
- /
- NasdaqGM:MDB
What You Can Learn From MongoDB, Inc.'s (NASDAQ:MDB) P/S
When you see that almost half of the companies in the IT industry in the United States have price-to-sales ratios (or "P/S") below 2x, MongoDB, Inc. (NASDAQ:MDB) looks to be giving off strong sell signals with its 19x P/S ratio. Nonetheless, we'd need to dig a little deeper to determine if there is a rational basis for the highly elevated P/S.
View our latest analysis for MongoDB
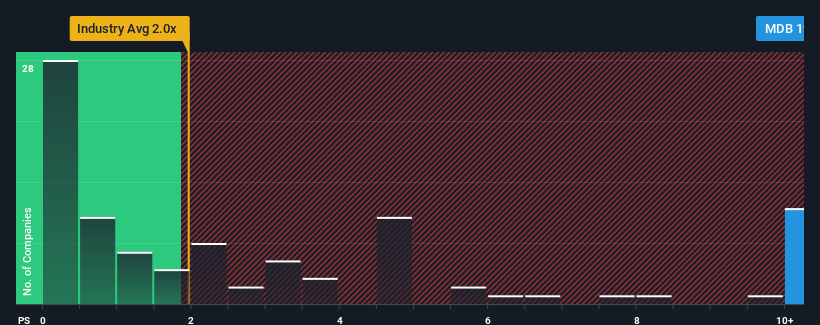
How MongoDB Has Been Performing
Recent times have been advantageous for MongoDB as its revenues have been rising faster than most other companies. The P/S is probably high because investors think this strong revenue performance will continue. If not, then existing shareholders might be a little nervous about the viability of the share price.
Keen to find out how analysts think MongoDB's future stacks up against the industry? In that case, our free report is a great place to start.How Is MongoDB's Revenue Growth Trending?
MongoDB's P/S ratio would be typical for a company that's expected to deliver very strong growth, and importantly, perform much better than the industry.
If we review the last year of revenue growth, the company posted a terrific increase of 33%. The latest three year period has also seen an excellent 192% overall rise in revenue, aided by its short-term performance. So we can start by confirming that the company has done a great job of growing revenue over that time.
Shifting to the future, estimates from the analysts covering the company suggest revenue should grow by 24% per annum over the next three years. That's shaping up to be materially higher than the 14% each year growth forecast for the broader industry.
With this in mind, it's not hard to understand why MongoDB's P/S is high relative to its industry peers. It seems most investors are expecting this strong future growth and are willing to pay more for the stock.
What Does MongoDB's P/S Mean For Investors?
It's argued the price-to-sales ratio is an inferior measure of value within certain industries, but it can be a powerful business sentiment indicator.
We've established that MongoDB maintains its high P/S on the strength of its forecasted revenue growth being higher than the the rest of the IT industry, as expected. Right now shareholders are comfortable with the P/S as they are quite confident future revenues aren't under threat. It's hard to see the share price falling strongly in the near future under these circumstances.
Having said that, be aware MongoDB is showing 2 warning signs in our investment analysis, you should know about.
If companies with solid past earnings growth is up your alley, you may wish to see this free collection of other companies with strong earnings growth and low P/E ratios.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
MI

The Foxhole
A landmark settlement is meant to punish Meta (META). If the 1998 tobacco deal is any guide, it might protect it.
179
ZO
zoe_vi5fn
Any moat with an opt-out clause for your competitors is just a fence around your own garden.
CO
connor_iwn1g
Worth looking at what previous legal action actually did to Meta rather than reaching for tobacco. The FTC's record five billion dollar privacy fine in 2019 was met with the stock rising, because it came in below fears and removed an open question. GDPR was designed to constrain large platforms and increased their share of the European ad market, because compliance cost fell hardest on small intermediaries. The FTC's antitrust case, the one that could genuinely have broken the company up, was decided in Meta's favour last November. The only thing that ever meaningfully hurt the business was Apple changing a tracking default, and Meta out-spent that too, while the ad-tech firms that could not afford to rebuild disappeared. The pattern is not that Meta survives regulation. It is that regulation keeps costing its smaller competitors more.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
10
About NasdaqGM:MDB
MongoDB
Provides general purpose database platform worldwide.
Flawless balance sheet with reasonable growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
31 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5861.4% undervalued
63 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.1% undervalued
65 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11632.1% undervalued
13 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
JO


John_Eric on Betterware de MéxicoP.I. de ·
Only Two Analysts Cover This Stock.
Fair Value:US$54.6571.1% undervalued
2 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
RO


RockeTeller on Kuya Silver ·
Kuya Silver, The High-Octane Rocket With 15,372 g/t Silver + $12 AISC
Fair Value:CA$10.8493.3% undervalued
10 followersusers have followed this narrative
1 commentusers have commented on this narrative
1 likeusers have liked this narrative
RO


Robbo on Unilever ·
Unilever (LSE:ULVR), changes in the wind.
Fair Value:UK£42.2813.0% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28022.3% undervalued
363 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9122.3% overvalued
211 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k73.1% undervalued
125 followersusers have followed this narrative
3 commentsusers have commented on this narrative
17 likesusers have liked this narrative
Trending Discussion

BL


Blagget on BP Silver ·
Yes, it is for sure. When I first published my narrative on BP Silver back in January, it gave me strong Santacruz Silver vibes. But now I know this is the next SCZ.I'd like to ask you to take a look at Terra Balcanica (CSE:TERA).I'd be REALLY surprised if it doesn't interest you. I'd even challenge you to find a more undervalued miner than TERA. I'm serious. You'd earn a loyal follower and reader for the rest of my life.Let me point you to three stocks, without further context or explanation of how they're related, to quickly show how unreasonably low Terra Balcanica's market cap is. You'll obviously figure out the connection pretty quickly yourself.Military Metals - license revokedRegener8 Resources - zero-drill neighborAdriatic Metals - neighbor that DPM boughtI promise you, you can dig as deep as you want here, count in every negative aspect and even things that aren't negative but that someone might read as negative, and the current market cap still makes no sense. I strongly believe that will change rather soon though, judging by the level 2 market depth over the last couple of days.I also suggest you take a look at DPM documents/reports regarding Vareš. They seem pleased with the purchase? 😁Anyway, I agree on BP, 100% correct. Enjoyed the read.
0
|0
