
Advertisement
- Japan
- /
- Entertainment
- /
- TSE:3672
AltPlus Inc. (TSE:3672) Looks Inexpensive After Falling 35% But Perhaps Not Attractive Enough
AltPlus Inc. (TSE:3672) shareholders that were waiting for something to happen have been dealt a blow with a 35% share price drop in the last month. The recent drop completes a disastrous twelve months for shareholders, who are sitting on a 60% loss during that time.
Following the heavy fall in price, when close to half the companies operating in Japan's Entertainment industry have price-to-sales ratios (or "P/S") above 1.3x, you may consider AltPlus as an enticing stock to check out with its 0.4x P/S ratio. Although, it's not wise to just take the P/S at face value as there may be an explanation why it's limited.
See our latest analysis for AltPlus
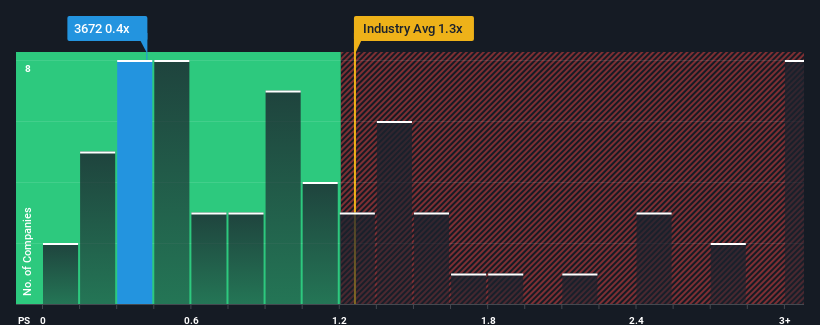
How AltPlus Has Been Performing
For instance, AltPlus' receding revenue in recent times would have to be some food for thought. One possibility is that the P/S is low because investors think the company won't do enough to avoid underperforming the broader industry in the near future. If you like the company, you'd be hoping this isn't the case so that you could potentially pick up some stock while it's out of favour.
Although there are no analyst estimates available for AltPlus, take a look at this free data-rich visualisation to see how the company stacks up on earnings, revenue and cash flow.Do Revenue Forecasts Match The Low P/S Ratio?
There's an inherent assumption that a company should underperform the industry for P/S ratios like AltPlus' to be considered reasonable.
Retrospectively, the last year delivered a frustrating 16% decrease to the company's top line. This means it has also seen a slide in revenue over the longer-term as revenue is down 46% in total over the last three years. Accordingly, shareholders would have felt downbeat about the medium-term rates of revenue growth.
This is in contrast to the rest of the industry, which is expected to decline by 2.2% over the next year, or less than the company's recent medium-term annualised revenue decline.
In light of this, it's understandable that AltPlus' P/S sits below the majority of other companies. However, when revenue shrink rapidly P/S often shrinks too, which could set up shareholders for future disappointment regardless. Even just maintaining these prices will be difficult to achieve as recent revenue trends are already weighing down the shares heavily.
The Final Word
The southerly movements of AltPlus' shares means its P/S is now sitting at a pretty low level. Using the price-to-sales ratio alone to determine if you should sell your stock isn't sensible, however it can be a practical guide to the company's future prospects.
It's clear that AltPlus trades at a low P/S relative to the wider industry on the weakness of its recent three-year revenue being even worse than the forecasts for a struggling industry, as expected. At this stage investors feel the potential for an improvement in revenue isn't great enough to justify a higher P/S ratio. Although, we would be concerned whether the company can even maintain its medium-term level of performance under these tough industry conditions. In the meantime, unless the company's relative performance improves, the share price will hit a barrier around these levels.
Before you settle on your opinion, we've discovered 3 warning signs for AltPlus (1 is a bit unpleasant!) that you should be aware of.
If strong companies turning a profit tickle your fancy, then you'll want to check out this free list of interesting companies that trade on a low P/E (but have proven they can grow earnings).
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

1214
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
31
About TSE:3672
AltPlus
Plans, develops, and operates online games for smartphone applications in Japan.
Flawless balance sheet with low risk.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
66 followersusers have followed this narrative
1 commentusers have commented on this narrative
17 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17016.9% undervalued
47 followersusers have followed this narrative
3 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8748.8% undervalued
48 followersusers have followed this narrative
2 commentsusers have commented on this narrative
19 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.0% undervalued
12 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
CL


Clive_Thompson on Novogenia ·
Novogenia: A High-Risk, Asset-Backed Micro-Cap With Significant Optionality
Fair Value:€16.762.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RO


RockeTeller on Meeka Metals ·
Meeka Metals: 1.2 Moz High-Grade Gold Producer – Open Pit Failure to Underground Transition?
Fair Value:AU$1.3991.0% undervalued
2 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RO

RogueEP on Quanex Building Products ·
The Market Is Pricing a Housing Cyclical. We See a Self-Funding Consolidator
Fair Value:US$33.3331.2% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28017.7% undervalued
372 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
130 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
AN

AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8323.9% undervalued
1378 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
Trending Discussion
DA
daniel_uvswg on Oncolytics Biotech ·
Thank you for the detailed backdown regarding this company and its stock. I think given the data and looking to be optimistic I would likely believe that it's no unbelievable to assume that the stock price could go to the ~$3 mark. Even at that level it's not a bad deal especially coming from sub $1 stock at the moment.
1
|0