
Advertisement
- United Kingdom
- /
- Professional Services
- /
- AIM:LTG
Should You Be Adding Learning Technologies Group (LON:LTG) To Your Watchlist Today?
It's only natural that many investors, especially those who are new to the game, prefer to buy shares in 'sexy' stocks with a good story, even if those businesses lose money. But as Warren Buffett has mused, 'If you've been playing poker for half an hour and you still don't know who the patsy is, you're the patsy.' When they buy such story stocks, investors are all too often the patsy.
If, on the other hand, you like companies that have revenue, and even earn profits, then you may well be interested in Learning Technologies Group (LON:LTG). While that doesn't make the shares worth buying at any price, you can't deny that successful capitalism requires profit, eventually. While a well funded company may sustain losses for years, unless its owners have an endless appetite for subsidizing the customer, it will need to generate a profit eventually, or else breathe its last breath.
View our latest analysis for Learning Technologies Group
Learning Technologies Group's Earnings Per Share Are Growing.
As one of my mentors once told me, share price follows earnings per share (EPS). Therefore, there are plenty of investors who like to buy shares in companies that are growing EPS. I, for one, am blown away by the fact that Learning Technologies Group has grown EPS by 40% per year, over the last three years. Growth that fast may well be fleeting, but like a lotus blooming from a murky pond, it sparks joy for the wary stock pickers.
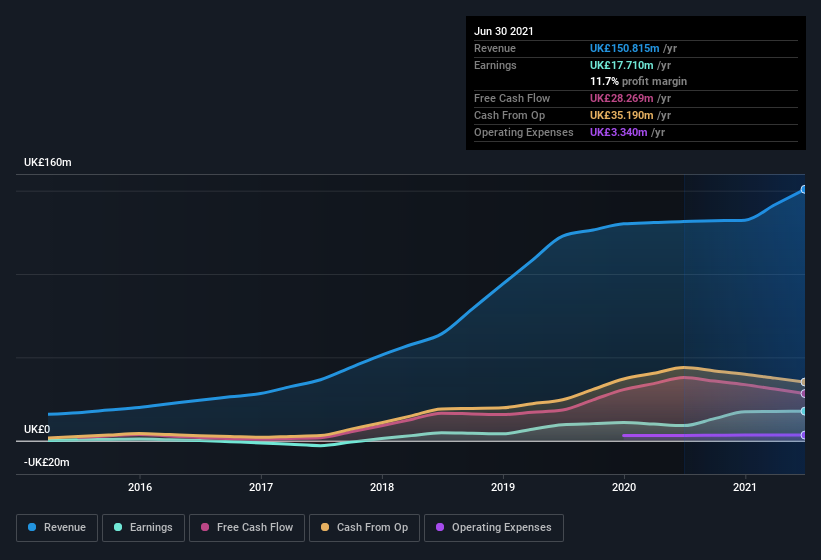
I like to take a look at earnings before interest and (EBIT) tax margins, as well as revenue growth, to get another take on the quality of the company's growth. While we note Learning Technologies Group's EBIT margins were flat over the last year, revenue grew by a solid 15% to UK£151m. That's a real positive.
In the chart below, you can see how the company has grown earnings, and revenue, over time. To see the actual numbers, click on the chart.
While we live in the present moment at all times, there's no doubt in my mind that the future matters more than the past. So why not check this interactive chart depicting future EPS estimates, for Learning Technologies Group?
Are Learning Technologies Group Insiders Aligned With All Shareholders?
I like company leaders to have some skin in the game, so to speak, because it increases alignment of incentives between the people running the business, and its true owners. As a result, I'm encouraged by the fact that insiders own Learning Technologies Group shares worth a considerable sum. Notably, they have an enormous stake in the company, worth UK£329m. That equates to 26% of the company, making insiders powerful and aligned with other shareholders. So it might be my imagination, but I do sense the glimmer of an opportunity.
It's good to see that insiders are invested in the company, but are remuneration levels reasonable? A brief analysis of the CEO compensation suggests they are. I discovered that the median total compensation for the CEOs of companies like Learning Technologies Group with market caps between UK£728m and UK£2.3b is about UK£1.2m.
The Learning Technologies Group CEO received total compensation of just UK£361k in the year to . That looks like modest pay to me, and may hint at a certain respect for the interests of shareholders. CEO compensation is hardly the most important aspect of a company to consider, but when its reasonable that does give me a little more confidence that leadership are looking out for shareholder interests. It can also be a sign of a culture of integrity, in a broader sense.
Is Learning Technologies Group Worth Keeping An Eye On?
Learning Technologies Group's earnings per share growth have been levitating higher, like a mountain goat scaling the Alps. The cherry on top is that insiders own a bucket-load of shares, and the CEO pay seems really quite reasonable. The sharp increase in earnings could signal good business momentum. Big growth can make big winners, so I do think Learning Technologies Group is worth considering carefully. Still, you should learn about the 3 warning signs we've spotted with Learning Technologies Group .
You can invest in any company you want. But if you prefer to focus on stocks that have demonstrated insider buying, here is a list of companies with insider buying in the last three months.
Please note the insider transactions discussed in this article refer to reportable transactions in the relevant jurisdiction.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
The rate hike just raised the bar every company you own has to clear before spending.
46
s
sean_3pk06
If inflation is coming from an energy shock and a supply squeeze, what does an overnight rate do about it? You cannot raise rates at a pipeline.
d
devon_jd150
Constellation Software is one of my favorite capital allocators.
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
14
About AIM:LTG
Learning Technologies Group
Provides talent and learning solutions, content, services, and digital platforms to corporate and government clients.
Solid track record with excellent balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2537.3% undervalued
199 followersusers have followed this narrative
0 commentsusers have commented on this narrative
30 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8830.8% undervalued
23 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8655.6% undervalued
13 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8536.5% undervalued
20 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
AS


AstrisCorporateAdvisory on INTLOOP ·
Renewed focus on business investment
Fair Value:JP¥4.17k43.8% undervalued
3 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
ON

Ontological on Lineage ·
Lineage Inc, International Cold-Storage Giant Building its REIT
Fair Value:US$128.4570.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on Aeluma ·
ALMU | Aeluma, Inc.: What They Said vs. What They Did
Fair Value:US$7.6475.8% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8329.4% undervalued
1463 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8919.9% undervalued
1636 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32724.8% undervalued
1649 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion
AN

anthony_x0j2w on Platform Group SE KGaA ·
Hello,(I am a shareholder).I spent the summer investigating in whatever I was able to find in the press, the trustee, or legal, and comparing it to FS Benner's declaration/transcripts:press: MM has a tendancy to use facts, modify them and turn them the way they want: 100% of their claims against TPG0 is traçable factually, 80% is flawed and interpreted. Example are numerous: 11M loans banks to be paid seems right, but it has not been an issue at all, it has been paid in full. (and it happens all the time in every business...); the previous HR becoming a financial director in the article herself being attacked by TPG on the legal side; the wrong address of curator (if truly announced by TPG).Trustee: according to my research (which can be incomplete) no communication to the Nordic trustee (hereby, bond holders) has been done on a, indebtedness (late payment) > 1M€, which is their obligation by contract (clause 14.d - https://corporate.the-platform-group.com/bond/) => this is a sign of a huge lie and fraud, or the sign that there is no indebtedness > 1M€ over the whole TPG group.Legal: still awaiting for an answer, probable that I won't get it.VALUATIONYou can spent hours working the fundamentals, if they're flawed...the thesis falls.Anyway, I always substracts the badwill (that I consider non-current - you have it in the CFS) & non-controlling interests from my valuation:Earnings ~22MFCF ~40M€The financial statements are not the issue here, we are more on an cheap option on the sincerity of the accounts that a real valuation. Unfortunately, these are unverifiable elements, hence the low price./!\ Careful:the accounts are consolidated and skip the subsidiaries issues...Careful with the business model: TPG0 is a financial holding that acquire subsidiaries, hold the debt, and has no operations. 100% of the Cash Flow comes from subs' dividends => it is a risk here, more a plumber risk than an operational one, but nevertheless...The auditor is too small, and managed by the same firm than before, with 140K€/year commission => it's too low, nobody external really reviewed what Benner and his team are doing internallycapital increase do not go through the CFS, but through change in equity AND equity in the BSIf the equity stays low too long, the WACC increase will be unbearable (I have a 30% global, with a 118% on equity): diluting is expensive => TPG machine can stay broken for a while.Most of the people I talk with never saw this, while this is ESSENTIAL to Benner's business model.SEVERAL EVENTS THAT COULD CHANGE:AEP is being audited by KPMG: if Benner plays the "we will propose KPMG to our shareholders BEOY", this can increase the trust in him significantly/KPMG (or other) to validate the 2026 IFRS accounts & having a word on HGB's: though still consolidated, at least we'll know...AEP being eventually acquired: while it carries a high integration risk due to its size, they talked about it so many times, that trust goes with it.Without this combination of event, the equity is doomed to stay at this level, IMO.Do not forget to also follow the bond: with TPG's announced safe harbor plan for buyback (25% of daily exchange), it is also interesting to check this illiquid and retail market: https://live.deutsche-boerse.com/bond/no0013256834-the-platform-group-ag-8-875-24-28?mic=XFRA
1
|0
CO

Constantin_Mar on Platform Group SE KGaA ·
Quite a lot of speculation presented as if it were evidence.You are combining alleged payment disputes, alleged bank actions, legal disputes with journalists and other unverified claims to imply that TPG’s financial reporting is somehow unreliable or that the company is approaching insolvency. That’s a very serious conclusion, but the evidence you’ve presented doesn’t establish it.TPG’s financial statements, share count, debt, cash flow and acquisitions can all be checked against official filings and corporate documents. That’s called due diligence. Repeating allegations and then pointing to a low P/E doesn’t prove anything.In fact, the P/E below 1 is precisely the reason the underlying numbers need to be investigated rather than dismissed. If you have documentary evidence that TPG’s reported figures are false, that banks actually cancelled the alleged facilities, or that the company is insolvent, publish the documents and numbers.Otherwise, this reads less like analysis and more like an attempt to create fear and selling pressure around a micro-cap stock.Claims require evidence. Allegations are not evidence.
1
|1
