Advertisement
- Australia
- /
- Metals and Mining
- /
- ASX:EVN
Evolution Mining (ASX:EVN) Is Down 9.5% After Record Profit And Dividend Amid Gold Price Pressures
SI

Reviewed by Sasha Jovanovic
- In recent days, Evolution Mining reported a record statutory profit for the first half of FY26 and declared a fully franked interim dividend, while also highlighting growth projects such as the Cowal underground and Mungari discoveries ahead of its June-quarter update.
- However, renewed inflation concerns and the prospect of further U.S. interest rate hikes have weighed on gold prices, raising fresh questions about how resilient Evolution's cash flow expectations will be if bullion remains under pressure.
- We’ll now examine how pressure on gold prices, amid interest rate uncertainty, could reshape Evolution Mining’s existing investment narrative and assumptions.
Uncover the next big thing with 62 elite penny stocks that balance risk and reward.
Evolution Mining Investment Narrative Recap
To own Evolution Mining, you generally need to believe its portfolio of long-life, low-cost gold assets and disciplined capital management can underpin solid cash generation. The recent gold price pullback, driven by renewed rate fears, directly tests that view by putting near term pressure on margins, making cash flow resilience into the June quarter the key catalyst and exposing downside risk if bullion weakness persists.
The record first half FY26 statutory profit and fully franked A$0.20 interim dividend are central to this story. They show Evolution entering this weaker gold patch with strong recent earnings and balance sheet flexibility, which matters for funding growth projects such as Cowal underground and the expanded Mungari operation if softer prices stretch cash flows.
Yet, against this backdrop, investors should also be aware that rising capital intensity and cost inflation could compound any prolonged gold price weakness...
Read the full narrative on Evolution Mining (it's free!)
Evolution Mining's narrative projects A$6.7 billion revenue and A$2.3 billion earnings by 2029.
Uncover how Evolution Mining's forecasts yield a A$13.91 fair value, a 27% upside to its current price.
Exploring Other Perspectives
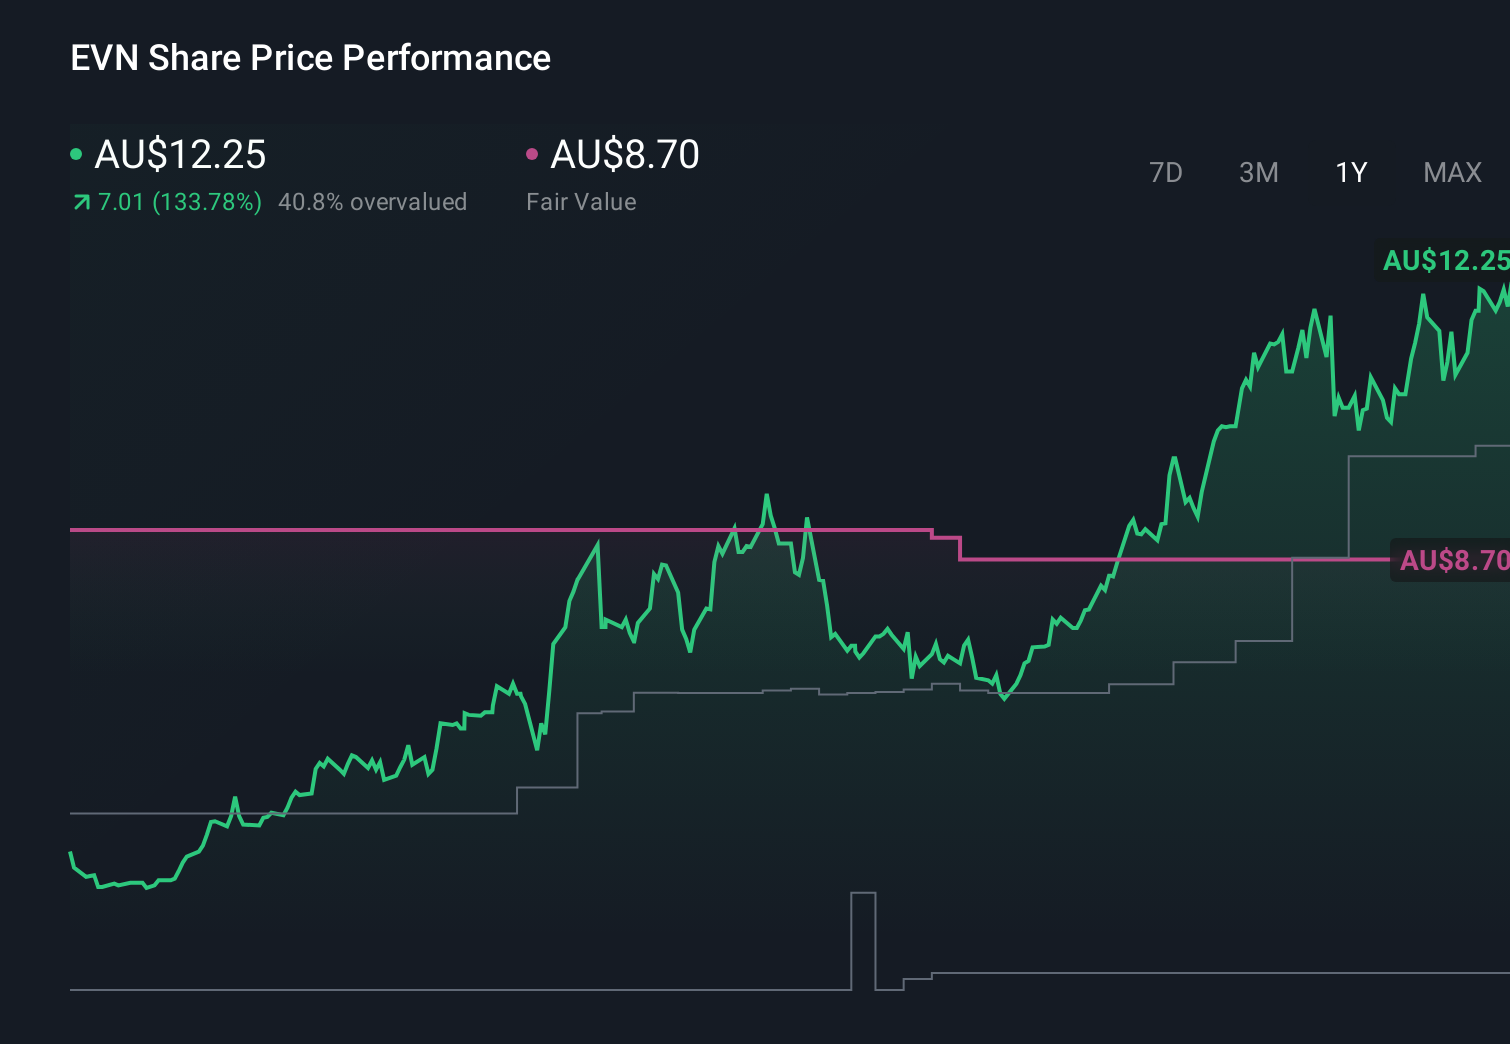
Compared with consensus, the most pessimistic analysts were already cautious, assuming revenue of about A$5.3 billion and earnings of A$1.7 billion by 2029, and the latest gold price shock may make you question whether those tougher views on rising costs and weaker demand are really too harsh or closer to the mark.
Explore 5 other fair value estimates on Evolution Mining - why the stock might be worth 46% less than the current price!
Decide For Yourself
Don't just follow the ticker - dig into the data and build a conviction that's truly your own.
- A great starting point for your Evolution Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- Our free Evolution Mining research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Evolution Mining's overall financial health at a glance.
Want Some Alternatives?
Every day counts. These free picks are already gaining attention. See them before the crowd does:
- We've uncovered the 7 dividend fortresses yielding 5%+ that don't just survive market storms, but thrive in them.
- Invest in the nuclear renaissance through our list of 88 elite nuclear energy infrastructure plays powering the global AI revolution.
- Outshine the giants: these 14 early-stage AI stocks could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Evolution Mining might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Oil routes are being dismantled one by one. The durable winner could be the North American energy left standing.
136
R
Rob_Curious
The durable premium you describe does not really exist for crude in a liquid market. This scenario, in almost a similar form, is happening thrice this year.
marcus_reid
Persistent volatility raises the hurdle rate on every long-lived energy investment, which suppresses the supply response that would eventually fix the problem. The instability is self-perpetuating in a way the price level is not.
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
14
About ASX:EVN
Evolution Mining
Engages in the exploration, mine development and operation, and sale of gold and gold-copper concentrates in Australia and Canada.
Solid track record with adequate balance sheet and pays a dividend.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2541.1% undervalued
194 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.9% undervalued
3 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8655.9% undervalued
5 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8536.1% undervalued
3 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
Recently Updated Narratives
FR


FRAGMENTS on SITE Centers ·
SITE Centers Trades Around $2.90. It Had $238.9 Million of Cash. One $129.6 Million Decision Changes the Outcome.
Fair Value:US$3.313.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
WA

waioa on UUE Holdings Berhad ·
UUE Holdings Expands Into High-Voltage Power Infrastructure Through Strategic JV
Fair Value:RM 1.559.7% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RO


RockeTeller on Honey Badger Silver ·
Honey Badger: 766g/t AgEq, 5km of Tunnels, Mill Already There, Why September’s PEA Matters
Fair Value:CA$9.3393.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8329.9% undervalued
1450 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8919.4% undervalued
1628 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32724.0% undervalued
1644 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion
AN

anthony_x0j2w on Platform Group SE KGaA ·
Hello,(I am a shareholder).I spent the summer investigating in whatever I was able to find in the press, the trustee, or legal, and comparing it to FS Benner's declaration/transcripts:press: MM has a tendancy to use facts, modify them and turn them the way they want: 100% of their claims against TPG0 is traçable factually, 80% is flawed and interpreted. Example are numerous: 11M loans banks to be paid seems right, but it has not been an issue at all, it has been paid in full. (and it happens all the time in every business...); the previous HR becoming a financial director in the article herself being attacked by TPG on the legal side; the wrong address of curator (if truly announced by TPG).Trustee: according to my research (which can be incomplete) no communication to the Nordic trustee (hereby, bond holders) has been done on a, indebtedness (late payment) > 1M€, which is their obligation by contract (clause 14.d - https://corporate.the-platform-group.com/bond/) => this is a sign of a huge lie and fraud, or the sign that there is no indebtedness > 1M€ over the whole TPG group.Legal: still awaiting for an answer, probable that I won't get it.VALUATIONYou can spent hours working the fundamentals, if they're flawed...the thesis falls.Anyway, I always substracts the badwill (that I consider non-current - you have it in the CFS) & non-controlling interests from my valuation:Earnings ~22MFCF ~40M€The financial statements are not the issue here, we are more on an cheap option on the sincerity of the accounts that a real valuation. Unfortunately, these are unverifiable elements, hence the low price./!\ Careful:the accounts are consolidated and skip the subsidiaries issues...Careful with the business model: TPG0 is a financial holding that acquire subsidiaries, hold the debt, and has no operations. 100% of the Cash Flow comes from subs' dividends => it is a risk here, more a plumber risk than an operational one, but nevertheless...The auditor is too small, and managed by the same firm than before, with 140K€/year commission => it's too low, nobody external really reviewed what Benner and his team are doing internallycapital increase do not go through the CFS, but through change in equity AND equity in the BSIf the equity stays low too long, the WACC increase will be unbearable (I have a 30% global, with a 118% on equity): diluting is expensive => TPG machine can stay broken for a while.Most of the people I talk with never saw this, while this is ESSENTIAL to Benner's business model.SEVERAL EVENTS THAT COULD CHANGE:AEP is being audited by KPMG: if Benner plays the "we will propose KPMG to our shareholders BEOY", this can increase the trust in him significantly/KPMG (or other) to validate the 2026 IFRS accounts & having a word on HGB's: though still consolidated, at least we'll know...AEP being eventually acquired: while it carries a high integration risk due to its size, they talked about it so many times, that trust goes with it.Without this combination of event, the equity is doomed to stay at this level, IMO.Do not forget to also follow the bond: with TPG's announced safe harbor plan for buyback (25% of daily exchange), it is also interesting to check this illiquid and retail market: https://live.deutsche-boerse.com/bond/no0013256834-the-platform-group-ag-8-875-24-28?mic=XFRA
1
|0
CO

Constantin_Mar on Platform Group SE KGaA ·
Quite a lot of speculation presented as if it were evidence.You are combining alleged payment disputes, alleged bank actions, legal disputes with journalists and other unverified claims to imply that TPG’s financial reporting is somehow unreliable or that the company is approaching insolvency. That’s a very serious conclusion, but the evidence you’ve presented doesn’t establish it.TPG’s financial statements, share count, debt, cash flow and acquisitions can all be checked against official filings and corporate documents. That’s called due diligence. Repeating allegations and then pointing to a low P/E doesn’t prove anything.In fact, the P/E below 1 is precisely the reason the underlying numbers need to be investigated rather than dismissed. If you have documentary evidence that TPG’s reported figures are false, that banks actually cancelled the alleged facilities, or that the company is insolvent, publish the documents and numbers.Otherwise, this reads less like analysis and more like an attempt to create fear and selling pressure around a micro-cap stock.Claims require evidence. Allegations are not evidence.
1
|1
