
Advertisement
- United States
- /
- Chemicals
- /
- NYSEAM:FSI
Flexible Solutions International Inc.'s (NYSEMKT:FSI) Analyst Just Slashed Next Year's Estimates
Today is shaping up negative for Flexible Solutions International Inc. (NYSEMKT:FSI) shareholders, with the covering analyst delivering a substantial negative revision to next year's forecasts. Both revenue and earnings per share (EPS) forecasts went under the knife, suggesting the analyst has soured majorly on the business.
After the downgrade, the solitary analyst covering Flexible Solutions International is now predicting revenues of US$30m in 2020. If met, this would reflect a modest 6.0% improvement in sales compared to the last 12 months. Statutory earnings per share are presumed to leap 98% to US$0.20. Previously, the analyst had been modelling revenues of US$34m and earnings per share (EPS) of US$0.27 in 2020. It looks like analyst sentiment has declined substantially, with a substantial drop in revenue estimates and a large cut to earnings per share numbers as well.
View our latest analysis for Flexible Solutions International
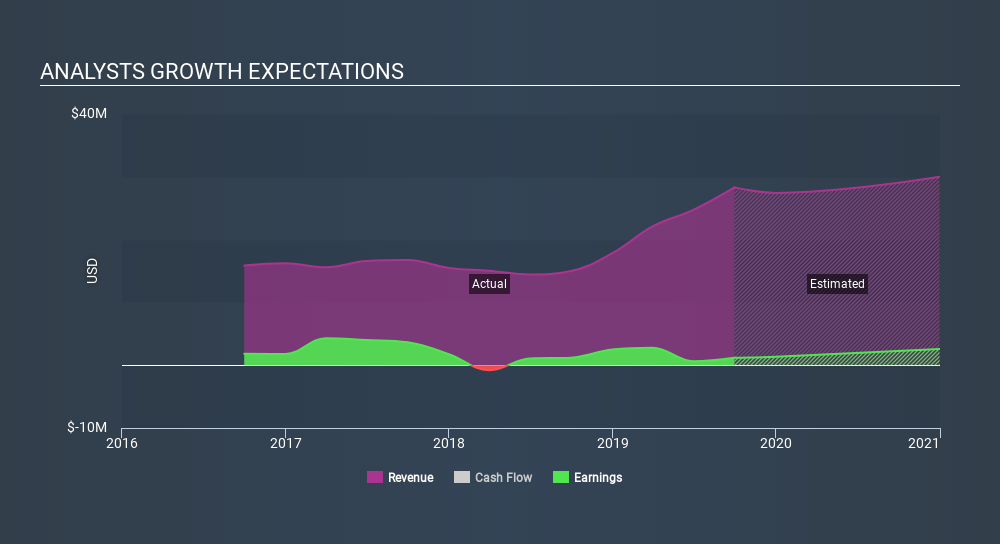
It'll come as no surprise then, to learn that the analyst has cut their price target 23% to US$2.50.
Another way we can view these estimates is in the context of the bigger picture, such as how the forecasts stack up against past performance, and whether forecasts are more or less bullish relative to other companies in the industry. We can infer from the latest estimates that forecasts expect a continuation of Flexible Solutions International's historical trends, as next year's 6.0% revenue growth is roughly in line with 7.2% annual revenue growth over the past five years. Compare this with the wider industry, which analyst estimates (in aggregate) suggest will see revenues grow 3.6% next year. So it's pretty clear that Flexible Solutions International is forecast to grow substantially faster than its industry.
The Bottom Line
The biggest issue in the new estimates is that the analyst has reduced their earnings per share estimates, suggesting business headwinds lay ahead for Flexible Solutions International. While the analyst did downgrade their revenue estimates, these forecasts still imply revenues will perform better than the wider market. After such a stark change in sentiment from the analyst, we'd understand if readers now felt a bit wary of Flexible Solutions International.
Even so, the longer term trajectory of the business is much more important for the value creation of shareholders. At least one analyst has provided forecasts out to 2020, which can be seen for free on our platform here.
Of course, seeing company management invest large sums of money in a stock can be just as useful as knowing whether analysts are downgrading their estimates. So you may also wish to search this free list of stocks that insiders are buying.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned.
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Thank you for reading.
M

The Foxhole
Three rival AI bosses just backed slowing AI down for safety. But who would a slowdown actually protect?
0
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
13
About NYSEAM:FSI
Flexible Solutions International
Develops, manufactures, and markets specialty chemicals that slow the evaporation of water in Canada, the United States, and internationally.
High growth potential with excellent balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2541.0% undervalued
190 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4938.9% undervalued
42 followersusers have followed this narrative
2 commentsusers have commented on this narrative
13 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k16.9% undervalued
31 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2537.2% undervalued
11 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
ZE

Zer0 on B&M European Value Retail ·
BME.L - My first writing on the stock :)
Fair Value:UK£1.549.9% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
BR

Brenin on Tristel ·
Tristel's US Expansion Could Spark a 286% Revenue Surge
Fair Value:UK£4.7316.0% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
RO


RockeTeller on Honey Badger Silver ·
Honey Badger: 766g/t AgEq, 5km of Tunnels, Mill Already There, Why September’s PEA Matters
Fair Value:CA$9.3393.2% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1434 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8920.9% undervalued
1617 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.5% undervalued
1636 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion
CO


Constantin_Mar on Platform Group SE KGaA ·
Quite a lot of speculation presented as if it were evidence.You are combining alleged payment disputes, alleged bank actions, legal disputes with journalists and other unverified claims to imply that TPG’s financial reporting is somehow unreliable or that the company is approaching insolvency. That’s a very serious conclusion, but the evidence you’ve presented doesn’t establish it.TPG’s financial statements, share count, debt, cash flow and acquisitions can all be checked against official filings and corporate documents. That’s called due diligence. Repeating allegations and then pointing to a low P/E doesn’t prove anything.In fact, the P/E below 1 is precisely the reason the underlying numbers need to be investigated rather than dismissed. If you have documentary evidence that TPG’s reported figures are false, that banks actually cancelled the alleged facilities, or that the company is insolvent, publish the documents and numbers.Otherwise, this reads less like analysis and more like an attempt to create fear and selling pressure around a micro-cap stock.Claims require evidence. Allegations are not evidence.
1
|1

