
Advertisement
- United Kingdom
- /
- Capital Markets
- /
- LSE:RAT
Don't Sell Rathbone Brothers Plc (LON:RAT) Before You Read This
Today, we'll introduce the concept of the P/E ratio for those who are learning about investing. We'll look at Rathbone Brothers Plc's (LON:RAT) P/E ratio and reflect on what it tells us about the company's share price. What is Rathbone Brothers's P/E ratio? Well, based on the last twelve months it is 45.59. In other words, at today's prices, investors are paying £45.59 for every £1 in prior year profit.
View our latest analysis for Rathbone Brothers
How Do I Calculate A Price To Earnings Ratio?
The formula for price to earnings is:
Price to Earnings Ratio = Price per Share ÷ Earnings per Share (EPS)
Or for Rathbone Brothers:
P/E of 45.59 = £21.55 ÷ £0.47 (Based on the trailing twelve months to June 2019.)
Is A High Price-to-Earnings Ratio Good?
A higher P/E ratio implies that investors pay a higher price for the earning power of the business. All else being equal, it's better to pay a low price -- but as Warren Buffett said, 'It's far better to buy a wonderful company at a fair price than a fair company at a wonderful price.'
How Does Rathbone Brothers's P/E Ratio Compare To Its Peers?
One good way to get a quick read on what market participants expect of a company is to look at its P/E ratio. As you can see below, Rathbone Brothers has a higher P/E than the average company (16.4) in the capital markets industry.
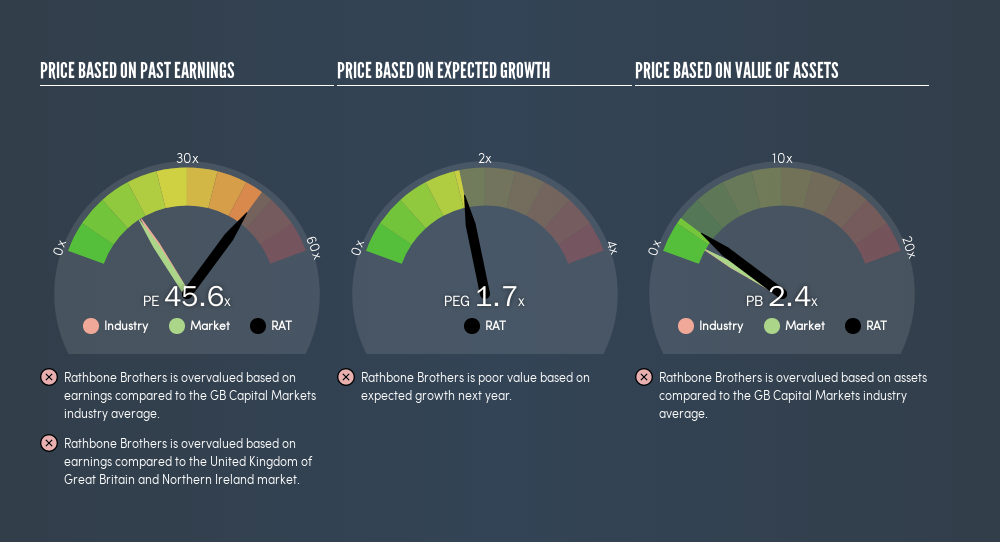
That means that the market expects Rathbone Brothers will outperform other companies in its industry.
How Growth Rates Impact P/E Ratios
When earnings fall, the 'E' decreases, over time. Therefore, even if you pay a low multiple of earnings now, that multiple will become higher in the future. Then, a higher P/E might scare off shareholders, pushing the share price down.
Rathbone Brothers saw earnings per share decrease by 60% last year. And it has shrunk its earnings per share by 12% per year over the last five years. This might lead to muted expectations.
A Limitation: P/E Ratios Ignore Debt and Cash In The Bank
It's important to note that the P/E ratio considers the market capitalization, not the enterprise value. Thus, the metric does not reflect cash or debt held by the company. Theoretically, a business can improve its earnings (and produce a lower P/E in the future) by investing in growth. That means taking on debt (or spending its cash).
While growth expenditure doesn't always pay off, the point is that it is a good option to have; but one that the P/E ratio ignores.
Rathbone Brothers's Balance Sheet
Rathbone Brothers's net debt is 1.3% of its market cap. The market might award it a higher P/E ratio if it had net cash, but its unlikely this low level of net borrowing is having a big impact on the P/E multiple.
The Verdict On Rathbone Brothers's P/E Ratio
Rathbone Brothers has a P/E of 45.6. That's higher than the average in its market, which is 16. With some debt but no EPS growth last year, the market has high expectations of future profits.
Investors should be looking to buy stocks that the market is wrong about. If the reality for a company is better than it expects, you can make money by buying and holding for the long term. So this free visualization of the analyst consensus on future earnings could help you make the right decision about whether to buy, sell, or hold.
But note: Rathbone Brothers may not be the best stock to buy. So take a peek at this free list of interesting companies with strong recent earnings growth (and a P/E ratio below 20).
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned. Thank you for reading.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
912
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
84
About LSE:RAT
Rathbones Group
Provides wealth management, asset management, and related services in the United Kingdom and Channel Islands.
Proven track record with adequate balance sheet and pays a dividend.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0625.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.5% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8528.7% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
ON

Ontological on Hinge Health ·
Scaling Digital Musculoskeletal Care With Strong Growth and Margins, Hinge Health (HNGE)
Fair Value:US$145.0434.9% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HO

hongjuan_p6tor on DSC Holdings ·
DSC is not a second car dealer like Carvana but a used car dealer enabler
Fair Value:US$3.32103.9% overvalued
1 followerusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
TI

TimLee on 3REN Berhad ·
3REN Berhad Is Powering the Semiconductor Ecosystem and Smart Manufacturing
Fair Value:RM 0.6843.4% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.9% undervalued
1493 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.0% undervalued
1652 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.0% undervalued
1669 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


PE
peng_i7fl6 on DSC Holdings ·
What stood out to me in this piece is how Zou draws a clear line between DSC and platforms like Carvana. DSC doesn't sell cars itself — it sits behind dealers and provides the operating system and transaction services. Once you frame it that way, the 90% market share starts to mean something real. Dealers run their daily work on the system: listings, pricing, inventory. The data accumulates bit by bit, and that's not something a competitor can buy its way into. You can't just throw money at it and get tens of thousands of dealers to switch systems.Her point about EVs was practical too. More brands, more models, more trim levels — dealer SKU management has gotten a lot messier, and pricing moves fast. Relying on gut feel from the old days doesn't cut it anymore. That demand isn't something the company invented; the industry just got to this point on its own.On the stock, her answer was honest. Management can't control short-term price action after listing, so they focus on running the business and delivering results. That reads more credible than pumping a narrative.The things I'd watch: whether dealer retention holds up, and whether the data and AI tools eventually show up as real revenue. A good story still has to pass the financials.
0
|0