
Advertisement
- United States
- /
- Specialty Stores
- /
- NasdaqGS:FLWS
Does 1-800-FLOWERS.COM (NASDAQ:FLWS) Have A Healthy Balance Sheet?
Howard Marks put it nicely when he said that, rather than worrying about share price volatility, 'The possibility of permanent loss is the risk I worry about... and every practical investor I know worries about. So it might be obvious that you need to consider debt, when you think about how risky any given stock is, because too much debt can sink a company. As with many other companies 1-800-FLOWERS.COM, Inc. (NASDAQ:FLWS) makes use of debt. But should shareholders be worried about its use of debt?
When Is Debt Dangerous?
Debt is a tool to help businesses grow, but if a business is incapable of paying off its lenders, then it exists at their mercy. Part and parcel of capitalism is the process of 'creative destruction' where failed businesses are mercilessly liquidated by their bankers. However, a more common (but still painful) scenario is that it has to raise new equity capital at a low price, thus permanently diluting shareholders. Of course, plenty of companies use debt to fund growth, without any negative consequences. The first thing to do when considering how much debt a business uses is to look at its cash and debt together.
Check out our latest analysis for 1-800-FLOWERS.COM
What Is 1-800-FLOWERS.COM's Net Debt?
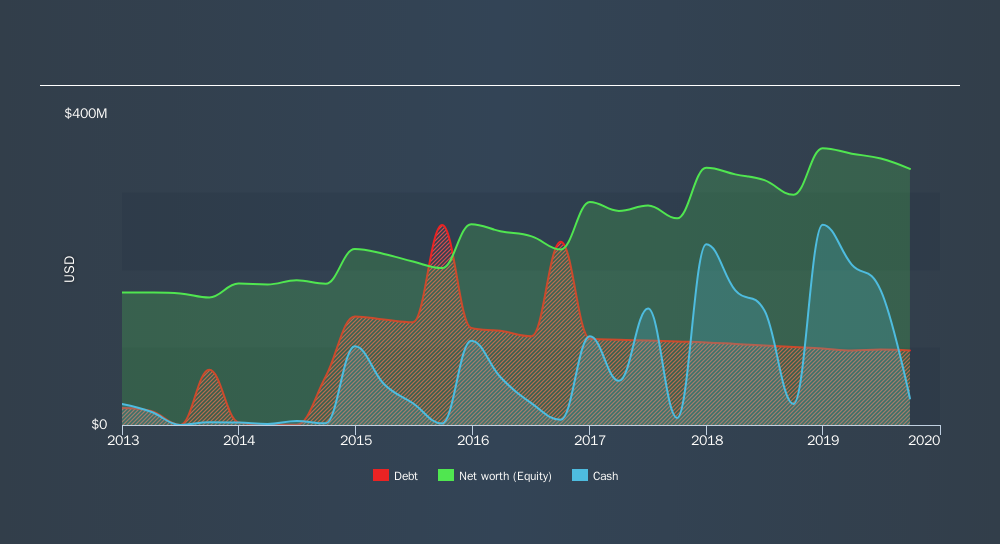
The image below, which you can click on for greater detail, shows that 1-800-FLOWERS.COM had debt of US$95.8m at the end of September 2019, a reduction from US$100.4m over a year. On the flip side, it has US$34.2m in cash leading to net debt of about US$61.6m.
How Healthy Is 1-800-FLOWERS.COM's Balance Sheet?
We can see from the most recent balance sheet that 1-800-FLOWERS.COM had liabilities of US$135.4m falling due within a year, and liabilities of US$200.1m due beyond that. On the other hand, it had cash of US$34.2m and US$36.1m worth of receivables due within a year. So its liabilities total US$265.3m more than the combination of its cash and short-term receivables.
This deficit isn't so bad because 1-800-FLOWERS.COM is worth US$838.7m, and thus could probably raise enough capital to shore up its balance sheet, if the need arose. But it's clear that we should definitely closely examine whether it can manage its debt without dilution.
We measure a company's debt load relative to its earnings power by looking at its net debt divided by its earnings before interest, tax, depreciation, and amortization (EBITDA) and by calculating how easily its earnings before interest and tax (EBIT) cover its interest expense (interest cover). This way, we consider both the absolute quantum of the debt, as well as the interest rates paid on it.
1-800-FLOWERS.COM's net debt is only 0.79 times its EBITDA. And its EBIT easily covers its interest expense, being 20.3 times the size. So you could argue it is no more threatened by its debt than an elephant is by a mouse. Another good sign is that 1-800-FLOWERS.COM has been able to increase its EBIT by 25% in twelve months, making it easier to pay down debt. There's no doubt that we learn most about debt from the balance sheet. But it is future earnings, more than anything, that will determine 1-800-FLOWERS.COM's ability to maintain a healthy balance sheet going forward. So if you want to see what the professionals think, you might find this free report on analyst profit forecasts to be interesting.
Finally, a company can only pay off debt with cold hard cash, not accounting profits. So the logical step is to look at the proportion of that EBIT that is matched by actual free cash flow. Over the last three years, 1-800-FLOWERS.COM recorded free cash flow worth a fulsome 87% of its EBIT, which is stronger than we'd usually expect. That positions it well to pay down debt if desirable to do so.
Our View
Happily, 1-800-FLOWERS.COM's impressive interest cover implies it has the upper hand on its debt. And the good news does not stop there, as its conversion of EBIT to free cash flow also supports that impression! Looking at the bigger picture, we think 1-800-FLOWERS.COM's use of debt seems quite reasonable and we're not concerned about it. After all, sensible leverage can boost returns on equity. Over time, share prices tend to follow earnings per share, so if you're interested in 1-800-FLOWERS.COM, you may well want to click here to check an interactive graph of its earnings per share history.
At the end of the day, it's often better to focus on companies that are free from net debt. You can access our special list of such companies (all with a track record of profit growth). It's free.
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned. Thank you for reading.
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

710
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
10
About NasdaqGS:FLWS
1-800-FLOWERS.COM
Provides gifts for various occasions in the United States and internationally.
Undervalued with moderate growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
61 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17014.4% undervalued
43 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.6% undervalued
44 followersusers have followed this narrative
2 commentsusers have commented on this narrative
17 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.9% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on KNOT Offshore Partners ·
KNOP | KNOT Offshore Partners LP: What They Said vs. What They Did
Fair Value:US$10.774.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AS


AstrisCorporateAdvisory on Ryobi ·
Entering a year of earnings consolidation
Fair Value:JP¥2.37k15.9% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
BL


Blagget on Terra Balcanica Resources ·
The C$4M Explorer Positioned to Become Europe's First Antimony Mine
Fair Value:CA$0.490.0% undervalued
6 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.4% undervalued
375 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k45.8% undervalued
129 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9121.5% overvalued
223 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
