
Last Update 03 Sep 26
Fair value Decreased 8.03%BILI: AI Advertising And Buybacks Will Support Future Upside
Analysts have trimmed their fair value estimate for Bilibili to about $27, down from roughly $30, citing slightly higher discount assumptions, a lower projected profit margin, and a more conservative future P/E multiple, even as they reference recent Street research that highlights the new $300m share repurchase program as a potential short term support for the stock.
What's in the News for Bilibili
- Bilibili reported Q2 2026 revenue of ¥7.94b and adjusted EPS of ¥1.58, which were above analyst estimates. The update highlighted AI supported advertising and user activity trends. Source: Q2 2026 earnings coverage.
- Advertising revenue for Bilibili was reported up 28% year over year in Q2 2026, with management linking this to AI tools that refine content targeting, increase engagement, and widen ad categories. Source: Q2 2026 earnings coverage.
- Daily active users were reported up 7% in Q2 2026, while daily video submissions were up 28%. The company recorded its 16th consecutive quarter of gross margin improvement, supported by AI powered advertising. Source: Q2 2026 earnings coverage.
- Bilibili relaunched its global app and removed passport verification for international users, opened content sharing between Chinese and international platforms, and started hiring community managers in multiple cities. Android access is live and iOS access is expected. Source: international app relaunch reports.
- The company has an approved share repurchase program of up to US$300m, announced on June 24, 2026. It reported buying back 2,897,300 shares for US$49.11m, equal to about 0.69% of shares, between June 24 and August 27, 2026, completing this tranche. Source: company buyback announcements.
Valuation Changes for Bilibili
- The fair value estimate has been reduced from about $29.65 to about $27.27, representing a modest decline in the projected valuation range for Bilibili.
- The discount rate has risen slightly from 10.04% to about 10.09%, reflecting a marginally higher return hurdle in the updated model.
- Revenue growth has been set slightly higher, from about 10.10% to about 10.21%, indicating a small uplift in the long term CN¥ revenue growth assumption.
- The net profit margin has been trimmed from about 9.30% to about 8.64%, representing a meaningful reduction in the assumed long term profitability level.
- The future P/E multiple has been reduced from about 30.72x to about 28.31x, implying a more conservative valuation multiple applied to Bilibili in the new model.
Key Takeaways
- Enhanced user engagement and creator monetization are fueling sustained revenue and margin growth, supported by a vibrant Gen Z+ user base and expanding value-added services.
- Strengthening proprietary content, rapid AI adoption, and disciplined cost control are driving operational efficiency, higher margins, and improving overall profitability.
- Heavy reliance on a shrinking youth audience, escalating costs, regulatory risks, and tough competition may constrain growth, compress margins, and threaten long-term profitability.
Catalysts
About Bilibili- Provides online entertainment services for the young generations in the People’s Republic of China.
- Bilibili is benefitting from the accelerating shift among young consumers toward interactive digital entertainment, with user engagement metrics such as DAU/MAU, paying users, and daily time spent all reaching record highs-this stronger engagement is likely to convert into sustained top-line revenue growth as the platform captures a larger share of wallet from Gen Z+ users.
- The expansion and monetization of Bilibili's creator ecosystem is creating new revenue streams through value-added services (memberships, fan charging, e-commerce), tapping into the rising demand for user-generated content and the growth of the creator economy; this supports higher ARPU and margin improvement.
- The company's strengthening of its proprietary IP ecosystem through the success of in-house animation and gaming, particularly with long-life cycle titles like San Mou (with international expansion planned), is likely to support higher content-driven revenues and reduced content cost pressures, positively impacting gross and operating margins.
- Rapid adoption of AI technologies-such as recommendation algorithms, content discovery, and AIGC-generated ad creatives-is improving operational efficiency and advertising effectiveness (as evidenced by a 10% lift in eCPM and 20%+ ad revenue growth), which should drive further margin expansion and positive earnings surprises.
- Ongoing improvements in operational efficiency and disciplined cost control, underpinned by economies of scale and AI-driven automation, are resulting in stable or declining operating expenses and a path toward mid-to-high teens operating margins, positioning Bilibili to deliver expanding net margins and growing adjusted net profit.
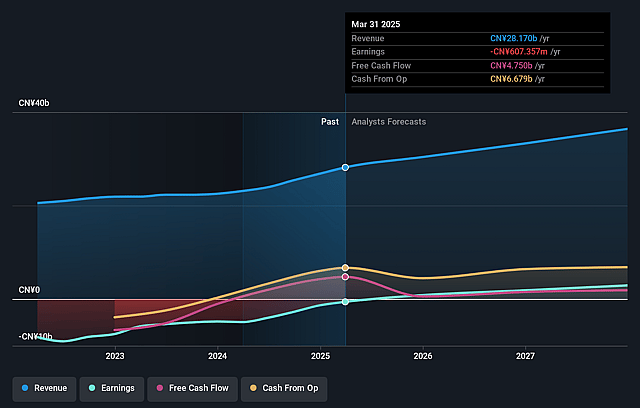
Bilibili Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Bilibili's revenue will grow by 10.2% annually over the next 3 years.
- Analysts assume that profit margins will increase from 4.9% today to 8.6% in 3 years time.
- Analysts expect earnings to reach CN¥3.6 billion (and earnings per share of CN¥8.63) by about September 2029, up from CN¥1.5 billion today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting CN¥5.0 billion in earnings, and the most bearish expecting CN¥3.2 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 28.3x on those 2029 earnings, which is the same as it is today today. This future PE is greater than the current PE for the US Interactive Media and Services industry at 13.3x.
- Analysts expect the number of shares outstanding to grow by 0.25% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 10.09%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- As Bilibili's growth remains highly concentrated in China and focused on Gen Z+ audiences, demographic shifts such as a declining youth population or evolving content preferences could shrink its core addressable market over time, constraining user and revenue growth.
- There is significant execution risk tied to dependence on blockbuster titles like San Mou and a limited upcoming game pipeline subject to regulatory approvals, which may create volatility and concentration risk in games revenue and delay growth in this segment.
- Continued rapid expansion in content costs, including investments in exclusive content and creator monetization tools, alongside only incremental improvements in ARPU, may threaten sustained margin expansion and delay consistent profitability.
- Bilibili operates in a highly competitive digital media landscape, facing intensifying competition from diversified domestic giants such as Tencent Video, Kuaishou, and Douyin, which could drive up user acquisition costs, erode market share, and put downward pressure on net margins and long-term earnings.
- Persistent regulatory uncertainty in China, including heightened scrutiny of online content, licensing delays for games, and evolving standards for user-generated content, exposes Bilibili to risks of content takedowns, fines, or even platform restrictions, leading to unpredictable impacts on revenue and net profit.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of $27.27 for Bilibili based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $36.0, and the most bearish reporting a price target of just $18.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be CN¥42.1 billion, earnings will come to CN¥3.6 billion, and it would be trading on a PE ratio of 28.3x, assuming you use a discount rate of 10.1%.
- Given the current share price of $15.45, the analyst price target of $27.27 is 43.3% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Bilibili?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Rising Digital Consumption And Gaming Will Power Interactive Media Experiences
View narrative
China's Shrinking Youth And Heightened Regulation Will Restrict Future Engagement
View narrative