
Last Update 12 Aug 26
Fair value Decreased 10%AVAV: Counter Drone And Laser Contracts Will Support Post SCAR Reset
AeroVironment's analyst price target has been reset lower to around $225 from about $252, as analysts adjust valuation multiples and profit expectations while still pointing to contract wins, backlog trends, and new Army laser and counter drone programs as key supports for the long-term story.
Analyst Commentary
Recent Street research on AeroVironment highlights a mix of optimism about contract momentum and market positioning, alongside concerns about execution risks and valuation after a sharp reset in expectations.
Bullish Takeaways
- Bullish analysts see the potential Army Enduring High Energy Laser contract and the Titan counter drone award as important proof points for AeroVironment's laser and C UAS offerings. They view these as supportive for revenue visibility through at least FY27.
- Several reports describe AeroVironment's recent investor day as reinforcing confidence in its long term growth strategy. They point to a targeted FY30 serviceable obtainable market of US$50b and a US$37b active opportunity pipeline as context for future contract wins.
- Some bullish analysts argue that consensus estimates have been reset to more conservative levels after lower EBITDA guidance and updated models. They see this as reducing downside surprise risk if the company executes on its backlog and pipeline.
- There is a recurring view that AeroVironment is well positioned in counter drone and broader defense technology markets. Bookings trends and backlog expectations are cited as support for longer term growth ambitions, even as near term estimates are trimmed.
Bearish Takeaways
- Bearish analysts highlight reduced price targets across the Street, reflecting lower valuation multiples and updated profitability assumptions after guidance pointed to EBITDA margins around the mid teens. They see this as less supportive for premium P/E or EV EBITDA multiples.
- Concerns are raised about slower award cadence, including delays in certain space related and SCDE contracts. Some analysts say this limits visibility and could cap upside to management's FY27 to FY30 outlook until contract timing becomes clearer.
- There is caution around AeroVironment's heavier investment cycle, with comments that increased spending, capacity expansion, and a more gradual recovery in some programs may weigh on margins. This is seen as creating execution risk if contract flow does not track management expectations.
- Some bearish analysts point to uncertainties around large programs such as the SCAR replacement and Space Force related work, along with flat broader defense spending. They cite these factors as reasons for more neutral ratings until there is firmer evidence that AeroVironment can sustain its longer term growth and margin ambitions.
What’s in the News for AeroVironment
- Securities class action lawsuits have been filed against AeroVironment related to its BADGER phased array antenna systems work on the U.S. Space Force SCAR program, following a stop work order, contract termination, an $89 million goodwill impairment in the Space reporting unit, operating loss disclosure, restated financial results, and identified material weaknesses in internal controls, with multiple law firms seeking lead plaintiffs before a July 27, 2026 deadline. Source: securities class action filings.
- Law firm Bernstein Liebhard is running a separate shareholder investigation into potential breaches of fiduciary duty by AeroVironment directors and officers, encouraging current shareholders to seek information on their legal rights. Source: Bernstein Liebhard alert.
- AeroVironment announced a teaming agreement with Applied Intuition to integrate Acuity ISR/Strike autonomy software into its Mayhem 10 launched effects system. The agreement aims to deliver autonomous swarm and hunter killer operations that support the U.S. Army’s Launched Effects program and highlight the company’s open architecture approach. Source: company announcement and primary news coverage.
- The Italian Ministry of Defence granted AeroVironment’s JUMP 20 unmanned aircraft system the MQ-31A military designation, confirming it as an official capability for the Italian Army under an April 2025 contract and supporting NATO interoperability for medium UAS missions. Source: company and regulatory announcements.
- AeroVironment reported a class period operating loss of $179.0 million for the third quarter of fiscal 2026, driven in part by a $151.3 million goodwill impairment tied to its SCAR related space business, alongside sizeable single day stock price declines following SCAR related disclosures as described in the class action complaint. Source: company filings and lawsuit summary.
Valuation Changes for AeroVironment
- Fair Value has fallen moderately, with the estimate moving from about $251.93 to roughly $225.77 per share.
- Discount Rate is slightly lower, moving from about 8.20% to roughly 8.14%, which indicates only a small adjustment to the risk input.
- Revenue Growth assumption is higher, shifting from about 13.38% to roughly 14.32% in the updated model.
- Net Profit Margin expectation has risen, moving from about 4.48% to roughly 5.44% in the latest forecast.
- Future P/E has fallen significantly, with the assumed multiple moving from about 131.1x to roughly 92.4x, which points to a lower valuation multiple applied to AeroVironment's earnings outlook.
Key Takeaways
- Expansion into advanced defense technologies and international markets is driving sustained revenue growth, backlog visibility, and long-term earnings stability.
- Modular, AI-powered platforms and recent acquisitions enable margin expansion, diversification, and operational leverage as defense demands accelerate.
- Heavy reliance on U.S. defense contracts, intensifying competition, margin pressures from acquisitions, underdeveloped international markets, and rapid tech shifts threaten future growth and profitability.
Catalysts
About AeroVironment- Designs, develops, produces, delivers, and supports a portfolio of robotic systems and related services for government agencies and businesses in the United States and internationally.
- AeroVironment's recent contract wins and rapid expansion into advanced areas like space-based laser communications and directed energy weapons position the company to capitalize on the persistent global shift toward defense modernization, addressing urgent demands among the U.S. and allied militaries-likely supporting sustained top-line revenue growth and backlog visibility over multiple years.
- The company's strategic focus on developing modular, interoperable, and software-defined platforms-including the newly launched AV Halo open software ecosystem-directly aligns with the accelerating adoption of AI-powered autonomy and network-centric warfare, enabling future premium pricing, increased service revenues, and gross margin expansion as these high-value platforms are deployed at scale.
- Successful integration of the BlueHalo acquisition materially expands AeroVironment's addressable markets, diversifies its competitive portfolio, and enables operational leverage as the company increases manufacturing capacity, which should support bottom-line EBITDA and net margin improvement as production volumes ramp.
- AeroVironment's growing list of large, multi-year government contracts (funded and unfunded backlog), as well as its positioning as a sole-source or leading provider in next-generation missile defense, Counter-UAS, and space comms, offers long-term revenue visibility and reduces downside risk associated with individual program delays-further enhancing future earnings stability.
- Driven by rising geopolitical tensions, cross-border threats, and persistent ISR needs, AeroVironment is successfully expanding internationally through key partnerships and certifications, which should drive both revenue growth and higher-margin international sales beyond its historical domestic concentration, positively impacting both top-line and profit growth trajectories.
AeroVironment Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
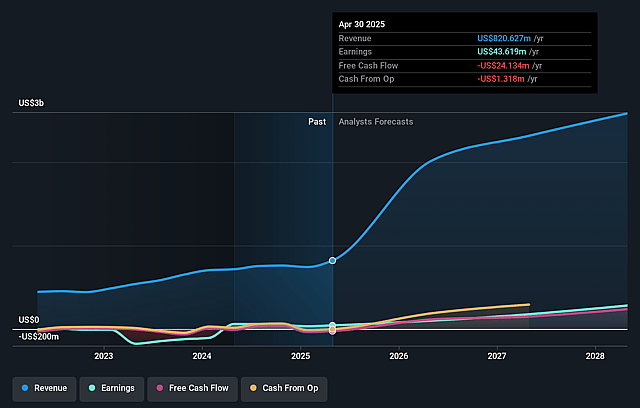
- Analysts are assuming AeroVironment's revenue will grow by 14.3% annually over the next 3 years.
- Analysts assume that profit margins will increase from -13.4% today to 5.4% in 3 years time.
- Analysts expect earnings to reach $160.6 million (and earnings per share of $3.12) by about August 2029, up from -$265.1 million today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting $270.4 million in earnings, and the most bearish expecting $144.3 million.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 93.5x on those 2029 earnings, up from -37.3x today. This future PE is greater than the current PE for the US Aerospace & Defense industry at 39.0x.
- Analysts expect the number of shares outstanding to grow by 1.43% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 8.14%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- AeroVironment's substantial dependence on U.S. government and DoD contracts (with 78% of revenue domestic and only 22% international) makes it highly vulnerable to U.S. budget cycles, congressional delays, or shifting defense priorities, increasing the risk of revenue volatility if funding or priorities change.
- Long-term competitive risks are amplified by the increasing number of entrants and established players in the UAS and Counter-UAS markets, raising the likelihood of price competition, margin compression, and potentially lower long-term net earnings on flagship products like Switchblade.
- The company's gross margin profile has seen a significant decline post-BlueHalo acquisition (from 43% GAAP/45% adjusted to 21% GAAP/29% adjusted), driven by a higher services mix and costs associated with integration, which may persist or worsen, pressuring long-term net margins and profitability.
- While AeroVironment highlights international opportunities, underinvestment or limited traction in expanding international sales and after-sales support could restrain revenue diversification and long-term growth, leaving the business exposed to regional policy changes or geopolitical headwinds.
- Accelerating technological advances in AI, large-scale drone autonomy, and counter-UAS solutions pose a risk that AeroVironment's current platforms could be leapfrogged if R&D investment or innovation pace lags behind larger or more nimble competitors, threatening future contract wins and eroding revenue and margins over time.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of $225.77 for AeroVironment based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $326.0, and the most bearish reporting a price target of just $148.57.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $3.0 billion, earnings will come to $160.6 million, and it would be trading on a PE ratio of 93.5x, assuming you use a discount rate of 8.1%.
- Given the current share price of $196.02, the analyst price target of $225.77 is 13.2% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on AeroVironment?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

AVAV | AeroVironment: What They Said vs. What They Did
View narrative
Global Defense Spending Will Fuel Autonomous Drone Expansion
View narrative
Rising Regulation And Export Limits Will Shrink Drone Markets
View narrative
The U.S. government's massive push for thousands of low-cost drones provides a massive floor for AVAV's valuation
View narrative