
Advertisement
- United States
- /
- IT
- /
- NasdaqGM:MDB
Does MongoDB (NASDAQ:MDB) Have A Healthy Balance Sheet?
Howard Marks put it nicely when he said that, rather than worrying about share price volatility, 'The possibility of permanent loss is the risk I worry about... and every practical investor I know worries about.' When we think about how risky a company is, we always like to look at its use of debt, since debt overload can lead to ruin. Importantly, MongoDB, Inc. (NASDAQ:MDB) does carry debt. But should shareholders be worried about its use of debt?
When Is Debt A Problem?
Debt and other liabilities become risky for a business when it cannot easily fulfill those obligations, either with free cash flow or by raising capital at an attractive price. If things get really bad, the lenders can take control of the business. While that is not too common, we often do see indebted companies permanently diluting shareholders because lenders force them to raise capital at a distressed price. By replacing dilution, though, debt can be an extremely good tool for businesses that need capital to invest in growth at high rates of return. When we think about a company's use of debt, we first look at cash and debt together.
View our latest analysis for MongoDB
What Is MongoDB's Net Debt?
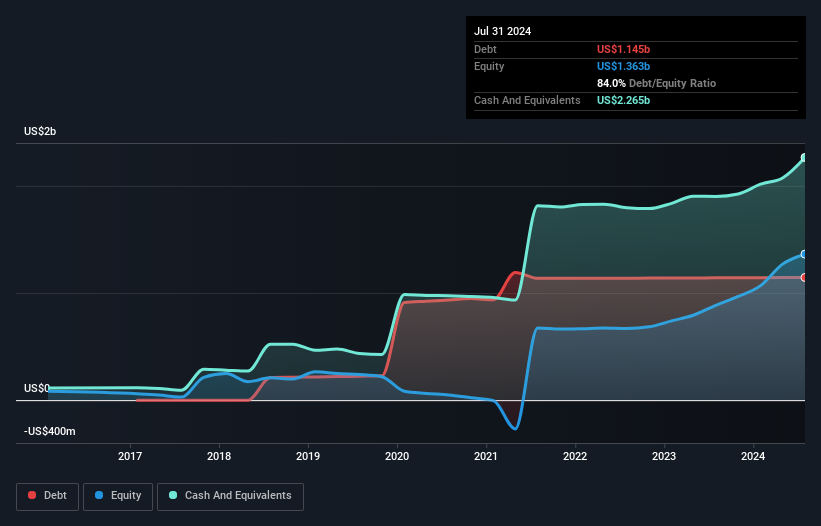
The chart below, which you can click on for greater detail, shows that MongoDB had US$1.14b in debt in July 2024; about the same as the year before. However, it does have US$2.26b in cash offsetting this, leading to net cash of US$1.12b.
A Look At MongoDB's Liabilities
Zooming in on the latest balance sheet data, we can see that MongoDB had liabilities of US$541.2m due within 12 months and liabilities of US$1.23b due beyond that. On the other hand, it had cash of US$2.26b and US$311.2m worth of receivables due within a year. So it can boast US$807.8m more liquid assets than total liabilities.
This surplus suggests that MongoDB has a conservative balance sheet, and could probably eliminate its debt without much difficulty. Simply put, the fact that MongoDB has more cash than debt is arguably a good indication that it can manage its debt safely. The balance sheet is clearly the area to focus on when you are analysing debt. But it is future earnings, more than anything, that will determine MongoDB's ability to maintain a healthy balance sheet going forward. So if you're focused on the future you can check out this free report showing analyst profit forecasts.
Over 12 months, MongoDB reported revenue of US$1.8b, which is a gain of 22%, although it did not report any earnings before interest and tax. Shareholders probably have their fingers crossed that it can grow its way to profits.
So How Risky Is MongoDB?
While MongoDB lost money on an earnings before interest and tax (EBIT) level, it actually generated positive free cash flow US$149m. So taking that on face value, and considering the net cash situation, we don't think that the stock is too risky in the near term. Keeping in mind its 22% revenue growth over the last year, we think there's a decent chance the company is on track. There's no doubt fast top line growth can cure all manner of ills, for a stock. There's no doubt that we learn most about debt from the balance sheet. However, not all investment risk resides within the balance sheet - far from it. For instance, we've identified 2 warning signs for MongoDB that you should be aware of.
Of course, if you're the type of investor who prefers buying stocks without the burden of debt, then don't hesitate to discover our exclusive list of net cash growth stocks, today.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
910
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
84
About NasdaqGM:MDB
MongoDB
Provides general purpose database platform worldwide.
Flawless balance sheet with reasonable growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CL


Clive_Thompson on Upside Gold ·
Upside Gold - New Technical Report Expected in Q1 2027 Could Re-Rate The Stock.
Fair Value:CA$1.552.0% undervalued
3 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.5% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8528.7% undervalued
25 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
KA

KASHIF_RIAZ_ on MCB Bank ·
MCB Bank: high-quality income anchor — 9% yield, cheap earnings, modest upside
Fair Value:PK₨45011.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
EP

Epstein_Research on Honey Badger Silver ·
Honey Badger Silver Delivers strong PEA, market likes it!
Fair Value:CA$255.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
KA

KASHIF_RIAZ_ on Service Long March Tyres ·
SLM: Pakistan's radial-tyre import-substitution play, fairly valued near listing price
Fair Value:PK₨258.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.9% undervalued
1495 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.0% undervalued
1652 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.0% undervalued
1667 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative


