Advertisement
- United States
- /
- Software
- /
- NasdaqGS:ADBE
Adobe (ADBE) Is Down 7.8% After CEO Exit And AI Shift - Has The Bull Case Changed?
SI

Reviewed by Sasha Jovanovic
- In early April 2026, Adobe reported record first-quarter revenue of US$6.40 billion, disclosed a US$150 million settlement over subscription practices, and confirmed longtime CEO Shantanu Narayen plans to step down amid intensifying AI competition and regulatory scrutiny.
- At the same time, Adobe highlighted rapidly growing AI-related recurring revenue and new products like Firefly and Acrobat AI Assistant, underscoring a tension between disruption fears and evidence that AI is already becoming a meaningful part of its business model.
- We’ll now examine how Narayen’s planned exit at a critical AI transition could reshape Adobe’s investment narrative built around AI monetization.
Outshine the giants: these 21 early-stage AI stocks could fund your retirement.
Adobe Investment Narrative Recap
To own Adobe today, you need to believe its creative and document ecosystem can stay essential even as AI reshapes how content is produced. The key near term catalyst is whether AI products like Firefly and Acrobat AI Assistant keep converting into recurring revenue, while the biggest current risk is that fast moving AI competitors and regulatory actions around subscriptions chip away at that high value ecosystem. The latest news directly touches both the AI story and the regulatory overhang.
The most relevant recent announcement here is Adobe’s disclosure that AI related recurring revenue has doubled and that AI first annual recurring revenue has more than tripled year over year. Against a backdrop of a sharp share price pullback, this growth matters because it offers concrete evidence that AI is already contributing financially, not just as a product story. How durable that contribution proves to be could shape how investors weigh the CEO transition and legal scrutiny.
Yet even with the progress in AI monetization, investors should be aware that...
Read the full narrative on Adobe (it's free!)
Adobe's narrative projects $31.2 billion revenue and $9.1 billion earnings by 2029. This requires 8.4% yearly revenue growth and about a $1.9 billion earnings increase from $7.2 billion today.
Uncover how Adobe's forecasts yield a $328.19 fair value, a 46% upside to its current price.
Exploring Other Perspectives
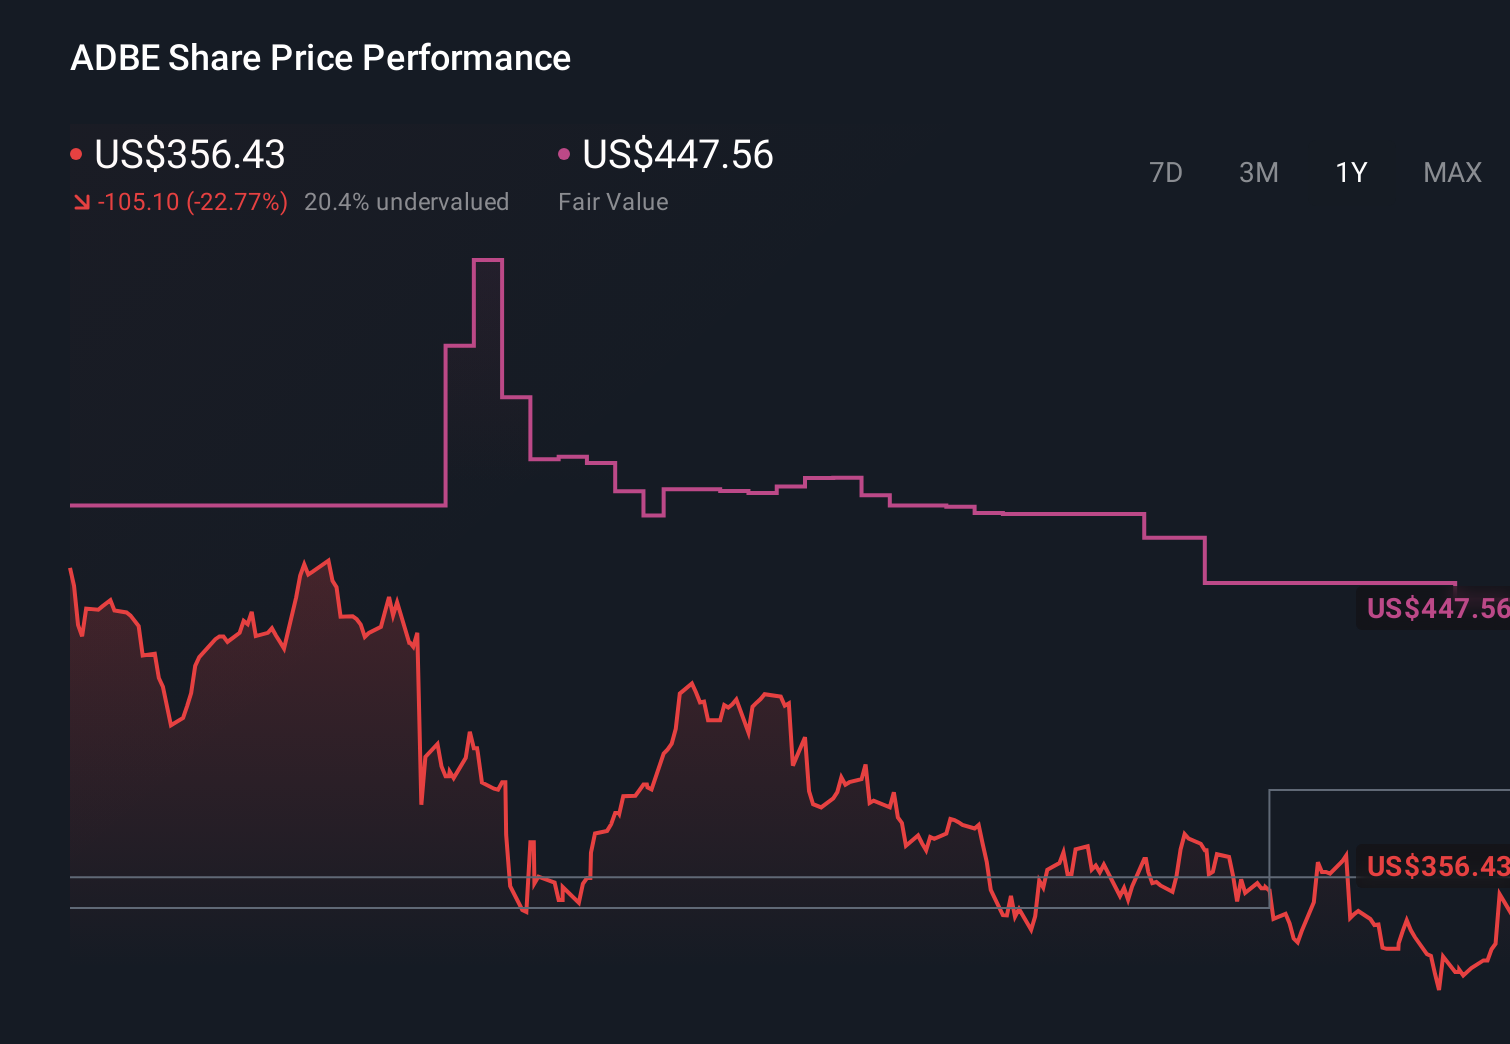
Before this selloff, the most optimistic analysts were banking on Adobe reaching about US$31.2 billion in revenue and US$11.4 billion in earnings by 2028, which assumes that AI investments and partnerships translate smoothly into faster growth. That is a far more optimistic story than the consensus view and the latest AI disruption worries may push these expectations higher or lower, so it is worth comparing these different narratives for yourself.
Explore 80 other fair value estimates on Adobe - why the stock might be worth just $220.00!
Reach Your Own Conclusion
Don't just follow the ticker - dig into the data and build a conviction that's truly your own.
- A great starting point for your Adobe research is our analysis highlighting 4 key rewards that could impact your investment decision.
- Our free Adobe research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Adobe's overall financial health at a glance.
Want Some Alternatives?
Opportunities like this don't last. These are today's most promising picks. Check them out now:
- The future of work is here. Discover the 33 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
- Uncover the next big thing with 33 elite penny stocks that balance risk and reward.
- This technology could replace computers: discover 24 stocks that are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Druckenmiller says cheap money's days are numbered. Boring, self-funding companies could be the opportunity.
1311
DE
devon_jd150
Leverage on its own is close to useless as a screen right now, because so much corporate debt was termed out at 2 to 3% and has not repriced. A business at three times leverage with nothing due until 2031 is in a completely different position from the same ratio rolling next year. Screen on weighted average maturity and the schedule behind it.
LE
LeverageIsLovely
In my view, Insurance companies are best positioned for this.
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?

Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
32
About NasdaqGS:ADBE
Adobe
Operates as a technology company worldwide.
Undervalued with adequate balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
67 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
48 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
32 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
WO


woodworthfund on Kraft Heinz ·
Kraft Heinz (KHC): Less Drama, More Ketchup
Fair Value:US$3527.7% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on DICK'S Sporting Goods ·
DKS | DICK'S Sporting Goods: What They Said vs. What They Did
Fair Value:US$112.7710.2% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
PR


prajeeshprathap on Medpace Holdings ·
Why Medpace Outperforms Competitors in the Mid-Sized Biotech Niche
Fair Value:US$53614.6% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
356 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
204 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
229 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative
Trending Discussion


JO
johnk72 on Global X AI Infrastructure ETF ·
Great picks & shovels investment. I hold 3,000 units with a plan to hold until the end of 2028
2
|0