
Advertisement
- United States
- /
- Biotech
- /
- NasdaqGS:CMPS
Is COMPASS Pathways (NASDAQ:CMPS) Weighed On By Its Debt Load?
Some say volatility, rather than debt, is the best way to think about risk as an investor, but Warren Buffett famously said that 'Volatility is far from synonymous with risk.' When we think about how risky a company is, we always like to look at its use of debt, since debt overload can lead to ruin. As with many other companies COMPASS Pathways plc (NASDAQ:CMPS) makes use of debt. But the more important question is: how much risk is that debt creating?
When Is Debt Dangerous?
Generally speaking, debt only becomes a real problem when a company can't easily pay it off, either by raising capital or with its own cash flow. Part and parcel of capitalism is the process of 'creative destruction' where failed businesses are mercilessly liquidated by their bankers. While that is not too common, we often do see indebted companies permanently diluting shareholders because lenders force them to raise capital at a distressed price. Of course, the upside of debt is that it often represents cheap capital, especially when it replaces dilution in a company with the ability to reinvest at high rates of return. When we examine debt levels, we first consider both cash and debt levels, together.
How Much Debt Does COMPASS Pathways Carry?
You can click the graphic below for the historical numbers, but it shows that as of September 2025 COMPASS Pathways had US$31.3m of debt, an increase on US$29.8m, over one year. However, it does have US$185.9m in cash offsetting this, leading to net cash of US$154.7m.
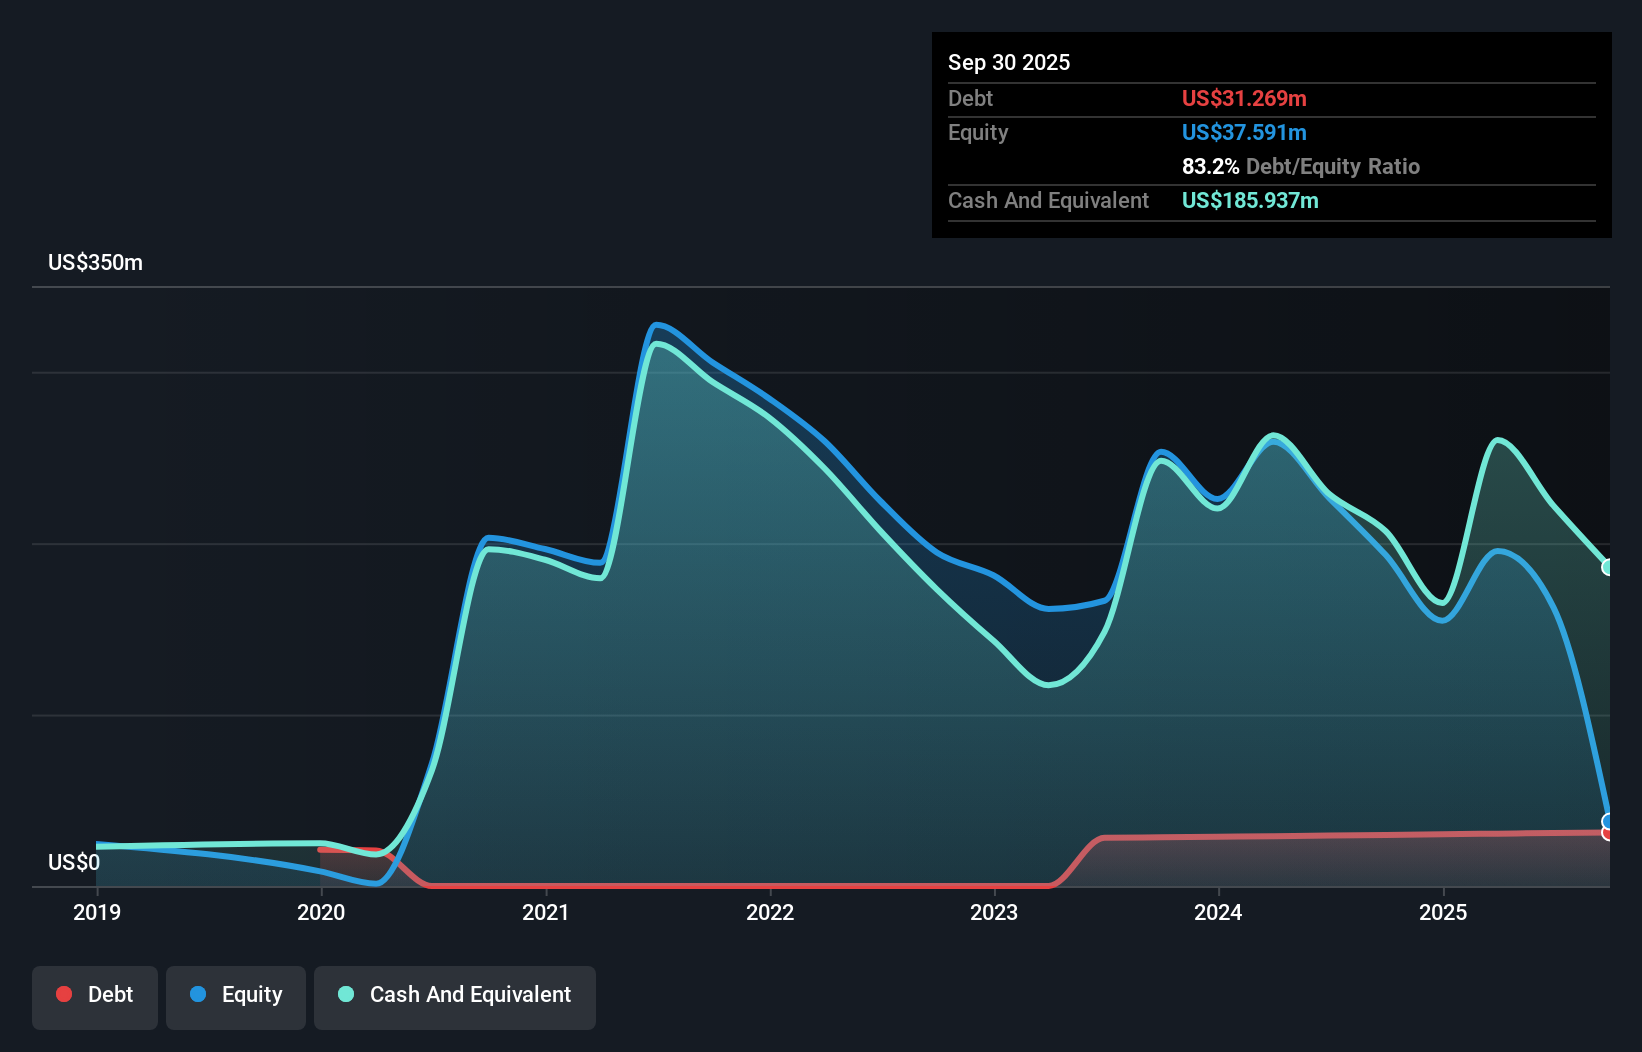
How Strong Is COMPASS Pathways' Balance Sheet?
The latest balance sheet data shows that COMPASS Pathways had liabilities of US$197.5m due within a year, and liabilities of US$20.6m falling due after that. Offsetting this, it had US$185.9m in cash and US$40.3m in receivables that were due within 12 months. So it can boast US$8.23m more liquid assets than total liabilities.
This state of affairs indicates that COMPASS Pathways' balance sheet looks quite solid, as its total liabilities are just about equal to its liquid assets. So while it's hard to imagine that the US$558.8m company is struggling for cash, we still think it's worth monitoring its balance sheet. Succinctly put, COMPASS Pathways boasts net cash, so it's fair to say it does not have a heavy debt load! There's no doubt that we learn most about debt from the balance sheet. But ultimately the future profitability of the business will decide if COMPASS Pathways can strengthen its balance sheet over time. So if you want to see what the professionals think, you might find this free report on analyst profit forecasts to be interesting.
View our latest analysis for COMPASS Pathways
Since COMPASS Pathways doesn't have significant operating revenue, shareholders may be hoping it comes up with a great new product, before it runs out of money.
So How Risky Is COMPASS Pathways?
Statistically speaking companies that lose money are riskier than those that make money. And we do note that COMPASS Pathways had an earnings before interest and tax (EBIT) loss, over the last year. And over the same period it saw negative free cash outflow of US$161m and booked a US$237m accounting loss. However, it has net cash of US$154.7m, so it has a bit of time before it will need more capital. Overall, its balance sheet doesn't seem overly risky, at the moment, but we're always cautious until we see the positive free cash flow. When analysing debt levels, the balance sheet is the obvious place to start. But ultimately, every company can contain risks that exist outside of the balance sheet. These risks can be hard to spot. Every company has them, and we've spotted 3 warning signs for COMPASS Pathways (of which 2 are a bit concerning!) you should know about.
If you're interested in investing in businesses that can grow profits without the burden of debt, then check out this free list of growing businesses that have net cash on the balance sheet.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

1314
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
31
About NasdaqGS:CMPS
COMPASS Pathways
Operates as a biotechnology company that focuses on mental health in the United Kingdom and the United States.
Excellent balance sheet and fair value.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
67 followersusers have followed this narrative
1 commentusers have commented on this narrative
17 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17016.9% undervalued
49 followersusers have followed this narrative
3 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8748.8% undervalued
48 followersusers have followed this narrative
2 commentsusers have commented on this narrative
19 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.0% undervalued
12 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
MA


MarkoVT on ANYCOLOR ·
Near zero debt, Japan centric focus provides future growth
Fair Value:JP¥4.05k26.3% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
MO


MontyNorman on Platform Group SE KGaA ·
Unbelievable numbers. Be very careful!
Fair Value:€0.1915.0% overvalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CL


Clive_Thompson on Novogenia ·
Novogenia: A High-Risk, Asset-Backed Micro-Cap With Significant Optionality
Fair Value:€16.762.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28017.7% undervalued
373 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
AN

AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8323.9% undervalued
1378 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
130 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
Trending Discussion
DA
daniel_uvswg on Oncolytics Biotech ·
Thank you for the detailed backdown regarding this company and its stock. I think given the data and looking to be optimistic I would likely believe that it's no unbelievable to assume that the stock price could go to the ~$3 mark. Even at that level it's not a bad deal especially coming from sub $1 stock at the moment.
1
|0