
Advertisement
- Romania
- /
- Auto Components
- /
- BVB:CMP
Is Compa (BVB:CMP) Using Too Much Debt?
Legendary fund manager Li Lu (who Charlie Munger backed) once said, 'The biggest investment risk is not the volatility of prices, but whether you will suffer a permanent loss of capital.' So it seems the smart money knows that debt - which is usually involved in bankruptcies - is a very important factor, when you assess how risky a company is. Importantly, Compa S.A. (BVB:CMP) does carry debt. But the real question is whether this debt is making the company risky.
When Is Debt A Problem?
Generally speaking, debt only becomes a real problem when a company can't easily pay it off, either by raising capital or with its own cash flow. Ultimately, if the company can't fulfill its legal obligations to repay debt, shareholders could walk away with nothing. While that is not too common, we often do see indebted companies permanently diluting shareholders because lenders force them to raise capital at a distressed price. Of course, plenty of companies use debt to fund growth, without any negative consequences. When we examine debt levels, we first consider both cash and debt levels, together.
Check out our latest analysis for Compa
How Much Debt Does Compa Carry?
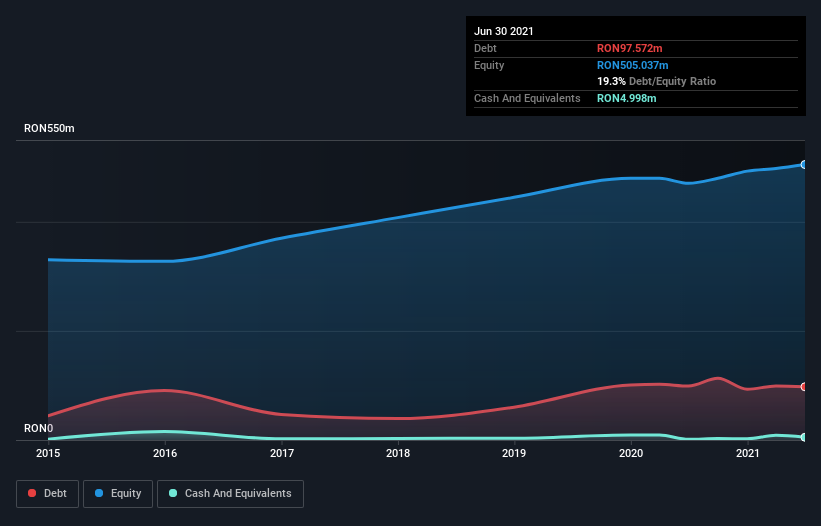
As you can see below, Compa had RON97.6m of debt, at June 2021, which is about the same as the year before. You can click the chart for greater detail. On the flip side, it has RON5.00m in cash leading to net debt of about RON92.6m.
How Healthy Is Compa's Balance Sheet?
Zooming in on the latest balance sheet data, we can see that Compa had liabilities of RON153.4m due within 12 months and liabilities of RON126.6m due beyond that. Offsetting these obligations, it had cash of RON5.00m as well as receivables valued at RON176.0m due within 12 months. So it has liabilities totalling RON98.9m more than its cash and near-term receivables, combined.
This deficit is considerable relative to its market capitalization of RON150.3m, so it does suggest shareholders should keep an eye on Compa's use of debt. Should its lenders demand that it shore up the balance sheet, shareholders would likely face severe dilution.
We measure a company's debt load relative to its earnings power by looking at its net debt divided by its earnings before interest, tax, depreciation, and amortization (EBITDA) and by calculating how easily its earnings before interest and tax (EBIT) cover its interest expense (interest cover). Thus we consider debt relative to earnings both with and without depreciation and amortization expenses.
Compa has a low net debt to EBITDA ratio of only 1.2. And its EBIT covers its interest expense a whopping 38.7 times over. So you could argue it is no more threatened by its debt than an elephant is by a mouse. Although Compa made a loss at the EBIT level, last year, it was also good to see that it generated RON33m in EBIT over the last twelve months. There's no doubt that we learn most about debt from the balance sheet. But it is Compa's earnings that will influence how the balance sheet holds up in the future. So when considering debt, it's definitely worth looking at the earnings trend. Click here for an interactive snapshot.
But our final consideration is also important, because a company cannot pay debt with paper profits; it needs cold hard cash. So it is important to check how much of its earnings before interest and tax (EBIT) converts to actual free cash flow. Over the last year, Compa reported free cash flow worth 15% of its EBIT, which is really quite low. For us, cash conversion that low sparks a little paranoia about is ability to extinguish debt.
Our View
Compa's conversion of EBIT to free cash flow and level of total liabilities definitely weigh on it, in our esteem. But the good news is it seems to be able to cover its interest expense with its EBIT with ease. Looking at all the angles mentioned above, it does seem to us that Compa is a somewhat risky investment as a result of its debt. Not all risk is bad, as it can boost share price returns if it pays off, but this debt risk is worth keeping in mind. There's no doubt that we learn most about debt from the balance sheet. But ultimately, every company can contain risks that exist outside of the balance sheet. Case in point: We've spotted 2 warning signs for Compa you should be aware of, and 1 of them is a bit unpleasant.
Of course, if you're the type of investor who prefers buying stocks without the burden of debt, then don't hesitate to discover our exclusive list of net cash growth stocks, today.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
M

The Foxhole
The US closed a loophole that helped Temu and Shein. Does that put local retailers back on a level playing field?
57
Jake_Merritt
The domestic retailers competing most directly with Temu and Shein are themselves among the largest importers in the country.
a
arjun_dyig0
Zooming out and looking at the effect of these regulatory changes last year, US manufacturing - production is at a seven year high. But employment is down. It's is interesting,
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
11
About BVB:CMP
Compa
Engages in the manufacture and sale of various parts and accessories for motor vehicles and motor vehicle engines in Romania.
Excellent balance sheet with questionable track record.
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2540.0% undervalued
188 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4937.2% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
11 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k16.9% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2537.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
JO


John_Eric on Booking Holdings ·
The Float Illusion: How Booking Holdings Almost Talked Me Into a $130-a-Share Mistake
Fair Value:US$322.3445.9% undervalued
3 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on Kroger ·
KR | The Kroger Co.: What They Said vs. What They Did
Fair Value:US$65.6513.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HU

Hunter_Z on Zenta Group ·
ZTG: Why the Short Thesis Is Becoming Harder to Ignore
Fair Value:US$0.1670.0% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1419 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.3% undervalued
1604 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.0% undervalued
1629 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative

