
Advertisement
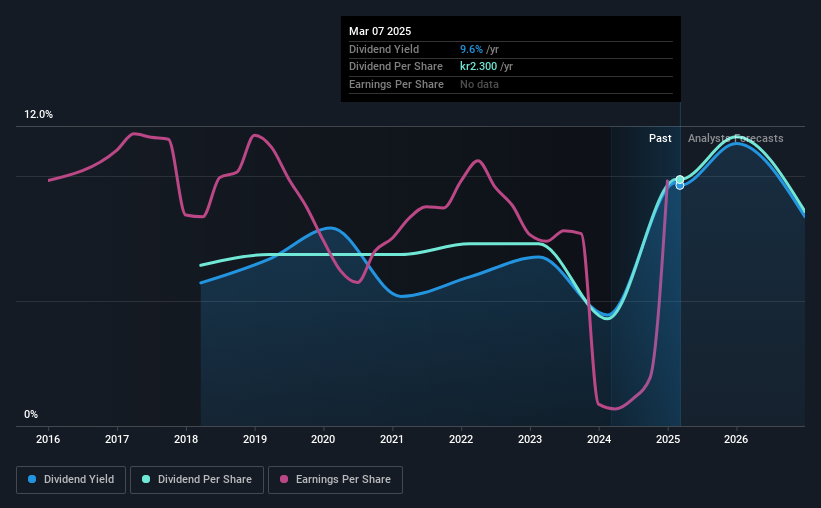
Webstep ASA (OB:WSTEP) will increase its dividend from last year's comparable payment on the 1st of January to NOK2.30. This makes the dividend yield 9.6%, which is above the industry average.
Check out our latest analysis for Webstep
Webstep's Payment Could Potentially Have Solid Earnings Coverage
While it is great to have a strong dividend yield, we should also consider whether the payment is sustainable. Prior to this announcement, the company was paying out 128% of what it was earning. Without profits and cash flows increasing, it would be difficult for the company to continue paying the dividend at this level.
Over the next year, EPS is forecast to expand by 54.7%. Under the assumption that the dividend will continue along recent trends, we think the payout ratio could be 71% which would be quite comfortable going to take the dividend forward.
Webstep's Dividend Has Lacked Consistency
It's comforting to see that Webstep has been paying a dividend for a number of years now, however it has been cut at least once in that time. This makes us cautious about the consistency of the dividend over a full economic cycle. The annual payment during the last 7 years was NOK1.50 in 2018, and the most recent fiscal year payment was NOK2.30. This implies that the company grew its distributions at a yearly rate of about 6.3% over that duration. We have seen cuts in the past, so while the growth looks promising we would be a little bit cautious about its track record.
Dividend Growth May Be Hard To Achieve
Growing earnings per share could be a mitigating factor when considering the past fluctuations in the dividend. Webstep has impressed us by growing EPS at 5.9% per year over the past five years. While EPS is growing at a decent rate, but future growth could be limited by the amount of earnings being paid out to shareholders.
Webstep's Dividend Doesn't Look Sustainable
In summary, while it's always good to see the dividend being raised, we don't think Webstep's payments are rock solid. The track record isn't great, and the payments are a bit high to be considered sustainable. We would probably look elsewhere for an income investment.
Companies possessing a stable dividend policy will likely enjoy greater investor interest than those suffering from a more inconsistent approach. However, there are other things to consider for investors when analysing stock performance. For example, we've identified 2 warning signs for Webstep (1 can't be ignored!) that you should be aware of before investing. Looking for more high-yielding dividend ideas? Try our collection of strong dividend payers.
Valuation is complex, but we're here to simplify it.
Discover if Webstep might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
Oracle has $638 billion of orders it can't fill yet. Tonight tells us how much it's costing to get ready.
117
s
sean_3pk06
Sixty-eight percent gross margin business is buying its way into a thirty-five percent gross margin business, and revenue growth is the metric everyone is watching.
d
devon_jd150
This is important about Oracle. Nvidia went to six of the biggest asset managers on earth to make sure someone else held this risk. Oracle just borrowed the money and held it itself.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About OB:WSTEP
Webstep
Provides information technology (IT) consultancy services to public and private businesses in Norway and Sweden.
Excellent balance sheet with reasonable growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2540.0% undervalued
186 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4937.2% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k17.2% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.7% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8529.7% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
IS

isidrohg on Micron Technology ·
Sold-Out HBM And Multi-Year Contracts Turn Micron From A Cycle Into A Contract
Fair Value:US$1.96k50.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AN


andrei9868 on Oracle ·
Oracle: The backlog is starting to show up in the P&L
Fair Value:US$22030.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1408 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.0% undervalued
1624 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.3% undervalued
1597 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative

