
Advertisement
- South Korea
- /
- Chemicals
- /
- KOSDAQ:A048830
NPK.Co.Ltd (KOSDAQ:048830) Shareholders Will Want The ROCE Trajectory To Continue
If we want to find a stock that could multiply over the long term, what are the underlying trends we should look for? Firstly, we'd want to identify a growing return on capital employed (ROCE) and then alongside that, an ever-increasing base of capital employed. If you see this, it typically means it's a company with a great business model and plenty of profitable reinvestment opportunities. With that in mind, we've noticed some promising trends at NPK.Co.Ltd (KOSDAQ:048830) so let's look a bit deeper.
What is Return On Capital Employed (ROCE)?
Just to clarify if you're unsure, ROCE is a metric for evaluating how much pre-tax income (in percentage terms) a company earns on the capital invested in its business. Analysts use this formula to calculate it for NPK.Co.Ltd:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.0089 = ₩509m ÷ (₩73b - ₩16b) (Based on the trailing twelve months to December 2020).
Therefore, NPK.Co.Ltd has an ROCE of 0.9%. Ultimately, that's a low return and it under-performs the Chemicals industry average of 8.3%.
See our latest analysis for NPK.Co.Ltd
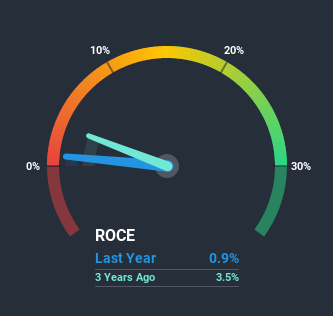
While the past is not representative of the future, it can be helpful to know how a company has performed historically, which is why we have this chart above. If you'd like to look at how NPK.Co.Ltd has performed in the past in other metrics, you can view this free graph of past earnings, revenue and cash flow.
What Can We Tell From NPK.Co.Ltd's ROCE Trend?
The fact that NPK.Co.Ltd is now generating some pre-tax profits from its prior investments is very encouraging. About five years ago the company was generating losses but things have turned around because it's now earning 0.9% on its capital. And unsurprisingly, like most companies trying to break into the black, NPK.Co.Ltd is utilizing 23% more capital than it was five years ago. This can indicate that there's plenty of opportunities to invest capital internally and at ever higher rates, both common traits of a multi-bagger.
The Bottom Line On NPK.Co.Ltd's ROCE
To the delight of most shareholders, NPK.Co.Ltd has now broken into profitability. And since the stock has fallen 34% over the last five years, there might be an opportunity here. So researching this company further and determining whether or not these trends will continue seems justified.
If you'd like to know more about NPK.Co.Ltd, we've spotted 3 warning signs, and 1 of them is potentially serious.
While NPK.Co.Ltd isn't earning the highest return, check out this free list of companies that are earning high returns on equity with solid balance sheets.
If you’re looking to trade NPK.Co.Ltd, open an account with the lowest-cost* platform trusted by professionals, Interactive Brokers. Their clients from over 200 countries and territories trade stocks, options, futures, forex, bonds and funds worldwide from a single integrated account. Promoted
Valuation is complex, but we're here to simplify it.
Discover if NPKLtd might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisThis article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
*Interactive Brokers Rated Lowest Cost Broker by StockBrokers.com Annual Online Review 2020
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

711
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
10
About KOSDAQ:A048830
NPKLtd
Engages in the manufacture and sale of plastics in South Korea and internationally.
Flawless balance sheet and slightly overvalued.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
65 followersusers have followed this narrative
1 commentusers have commented on this narrative
17 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17016.9% undervalued
44 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8748.8% undervalued
46 followersusers have followed this narrative
2 commentsusers have commented on this narrative
18 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.0% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
TI

TimLee on Gold Li Holdings Berhad ·
Gold Li IPO: Johor Property Developer Builds Its Next Growth Chapter
Fair Value:RM 0.2363.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
QU


QuanD on Shopify ·
The Default Platform for Entrepreneurs that Keeps Compounding
Fair Value:US$210.4731.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO

John_Eric on Hamilton Lane ·
Analysts Cut Their Targets. The Co-Chairman Cut a Check.
Fair Value:US$290.3164.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28017.7% undervalued
374 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
129 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9119.0% overvalued
224 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
