
Advertisement
- South Korea
- /
- Medical Equipment
- /
- KOSDAQ:A099430
Additional Considerations Required While Assessing Bio Plus' (KOSDAQ:099430) Strong Earnings
Bio Plus Co., Ltd (KOSDAQ:099430) announced strong profits, but the stock was stagnant. Our analysis suggests that this might be because shareholders have noticed some concerning underlying factors.
Check out our latest analysis for Bio Plus
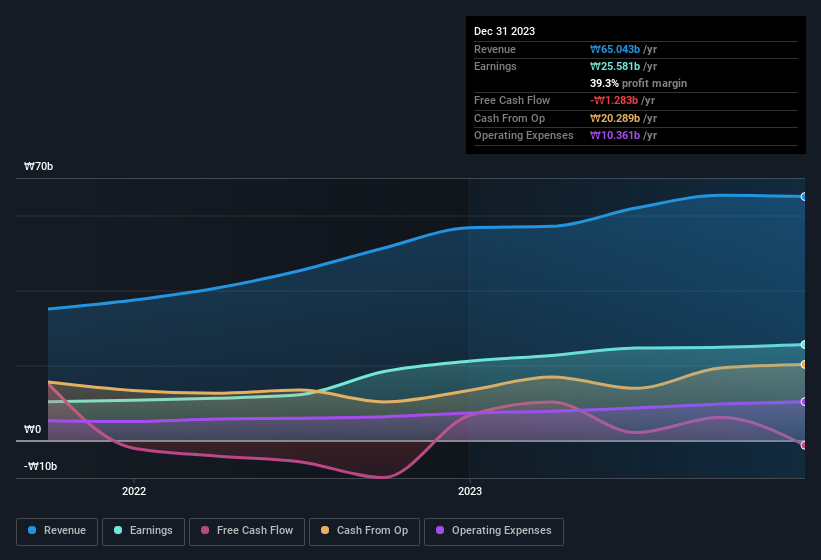
Examining Cashflow Against Bio Plus' Earnings
Many investors haven't heard of the accrual ratio from cashflow, but it is actually a useful measure of how well a company's profit is backed up by free cash flow (FCF) during a given period. To get the accrual ratio we first subtract FCF from profit for a period, and then divide that number by the average operating assets for the period. You could think of the accrual ratio from cashflow as the 'non-FCF profit ratio'.
That means a negative accrual ratio is a good thing, because it shows that the company is bringing in more free cash flow than its profit would suggest. While it's not a problem to have a positive accrual ratio, indicating a certain level of non-cash profits, a high accrual ratio is arguably a bad thing, because it indicates paper profits are not matched by cash flow. To quote a 2014 paper by Lewellen and Resutek, "firms with higher accruals tend to be less profitable in the future".
For the year to December 2023, Bio Plus had an accrual ratio of 0.43. As a general rule, that bodes poorly for future profitability. And indeed, during the period the company didn't produce any free cash flow whatsoever. Even though it reported a profit of ₩25.6b, a look at free cash flow indicates it actually burnt through ₩1.3b in the last year. It's worth noting that Bio Plus generated positive FCF of ₩6.7b a year ago, so at least they've done it in the past.
Note: we always recommend investors check balance sheet strength. Click here to be taken to our balance sheet analysis of Bio Plus.
Our Take On Bio Plus' Profit Performance
As we discussed above, we think Bio Plus' earnings were not supported by free cash flow, which might concern some investors. As a result, we think it may well be the case that Bio Plus' underlying earnings power is lower than its statutory profit. But at least holders can take some solace from the 20% EPS growth in the last year. Of course, we've only just scratched the surface when it comes to analysing its earnings; one could also consider margins, forecast growth, and return on investment, among other factors. In light of this, if you'd like to do more analysis on the company, it's vital to be informed of the risks involved. Be aware that Bio Plus is showing 2 warning signs in our investment analysis and 1 of those can't be ignored...
This note has only looked at a single factor that sheds light on the nature of Bio Plus' profit. But there is always more to discover if you are capable of focussing your mind on minutiae. For example, many people consider a high return on equity as an indication of favorable business economics, while others like to 'follow the money' and search out stocks that insiders are buying. While it might take a little research on your behalf, you may find this free collection of companies boasting high return on equity, or this list of stocks that insiders are buying to be useful.
Valuation is complex, but we're here to simplify it.
Discover if Bio Plus might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
Berkshire sold Visa and Mastercard. Ackman just bought both. So whose "smart money" are you actually following?
137
m
marcus_l38oa
American Express is the bigger bet of Buffet than Mastercard and Visa. They are still holding it.
z
zoe_vi5fn
lol. what we should be discussing is Berkshire's cash pile. Close to 400 billion now.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About KOSDAQ:A099430
Bio Plus
Engages in the research and development, production, and sale of bio products in South Korea.
Adequate balance sheet with questionable track record.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.576.0% undervalued
45 followersusers have followed this narrative
0 commentsusers have commented on this narrative
12 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17015.9% undervalued
14 followersusers have followed this narrative
2 commentsusers have commented on this narrative
2 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8752.7% undervalued
7 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.2% undervalued
4 followersusers have followed this narrative
1 commentusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
JO

John_Eric on American Express ·
The Mail Company That Became a Bank, Survived a Vat of Seawater, and Just Talked Its Way Into Another Scandal
Fair Value:US$444.1127.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO

John_Eric on Visa ·
Visa on Trial: The Berkshire Verdict, and Why I'm Overruling It
Fair Value:US$381.552.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
WO


Womble on AppLovin ·
AppLovin's Future Looks Bright with 19% Revenue Growth
Fair Value:US$331.946.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28022.3% undervalued
374 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k73.2% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9119.3% overvalued
217 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
Trending Discussion

BL


Blagget on BP Silver ·
Yes, it is for sure. When I first published my narrative on BP Silver back in January, it gave me strong Santacruz Silver vibes. But now I know this is the next SCZ.I'd like to ask you to take a look at Terra Balcanica (CSE:TERA).I'd be REALLY surprised if it doesn't interest you. I'd even challenge you to find a more undervalued miner than TERA. I'm serious. You'd earn a loyal follower and reader for the rest of my life.Let me point you to three stocks, without further context or explanation of how they're related, to quickly show how unreasonably low Terra Balcanica's market cap is. You'll obviously figure out the connection pretty quickly yourself.Military Metals - license revokedRegener8 Resources - zero-drill neighborAdriatic Metals - neighbor that DPM boughtI promise you, you can dig as deep as you want here, count in every negative aspect and even things that aren't negative but that someone might read as negative, and the current market cap still makes no sense. I strongly believe that will change rather soon though, judging by the level 2 market depth over the last couple of days.I also suggest you take a look at DPM documents/reports regarding Vareš. They seem pleased with the purchase? 😁Anyway, I agree on BP, 100% correct. Enjoyed the read.
1
|0
