Advertisement
- Japan
- /
- Consumer Durables
- /
- TSE:6752
Panasonic (TSE:6752) Valuation: Assessing the Impact of Technics’ New Turntable Launch on Future Growth
KS

Reviewed by Simply Wall St
If you’ve been watching Panasonic Holdings (TSE:6752) lately, the launch of the new Technics SL-40CBT and SL-50C Direct Drive Turntables at the CEDIA convention may have caught your eye for good reason. These innovative models blend Technics’ renowned audio quality with modern flair, including wireless connectivity and sleek design, aiming to capture the imagination of both seasoned Hi-Fi users and newcomers eager to upgrade. Anytime a legacy brand doubles down on a resurgent category like vinyl, it’s a move bound to attract attention from both music lovers and investors wondering what comes next for the company’s broader portfolio.
The timing of this product reveal adds another intriguing dimension, as shares in Panasonic Holdings have seen some swings this year. After a solid 7% gain over the past month and a 29% total return in the past year, the long-term trend looks positive, even if momentum has cooled in recent weeks. Combined with recent dividend stability and upbeat annual net income growth, these releases signal a company that’s leaning into product innovation amid a shifting consumer landscape.
But after the excitement over new product momentum and a year of strong share appreciation, is Panasonic Holdings undervalued, or is all that future growth already reflected in today’s price?
Most Popular Narrative: 24.4% Undervalued
According to the most widely followed valuation narrative, Panasonic Holdings currently trades at a significant discount to its estimated fair value. This suggests strong potential upside based on present assumptions.
Demand for industrial energy storage systems is accelerating beyond initial expectations due to large-scale data center investment driven by generative AI adoption. This is likely to support revenue growth and improve recurring earnings quality in the Energy segment.
Curious about what’s fueling this bold fair value call? Here’s a hint: this narrative counts on a mix of accelerating profit margins, long-term growth in new energy technologies, and ambitious assumptions about future earnings. Want to discover exactly how Panasonic's future potential is quantified? The full narrative breaks down the numbers in detail and highlights the most surprising drivers.
Result: Fair Value of ¥2,035.87 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.However, risks remain. Slower electric vehicle demand and ongoing restructuring delays could challenge Panasonic’s ability to deliver on optimistic growth forecasts.
Find out about the key risks to this Panasonic Holdings narrative.Another View: What Does Our DCF Say?
Some investors turn to our SWS DCF model for a different lens on value. This approach also suggests Panasonic Holdings is undervalued. This reinforces the earlier fair value narrative and raises a new question: which assumptions matter most for the future?
Look into how the SWS DCF model arrives at its fair value.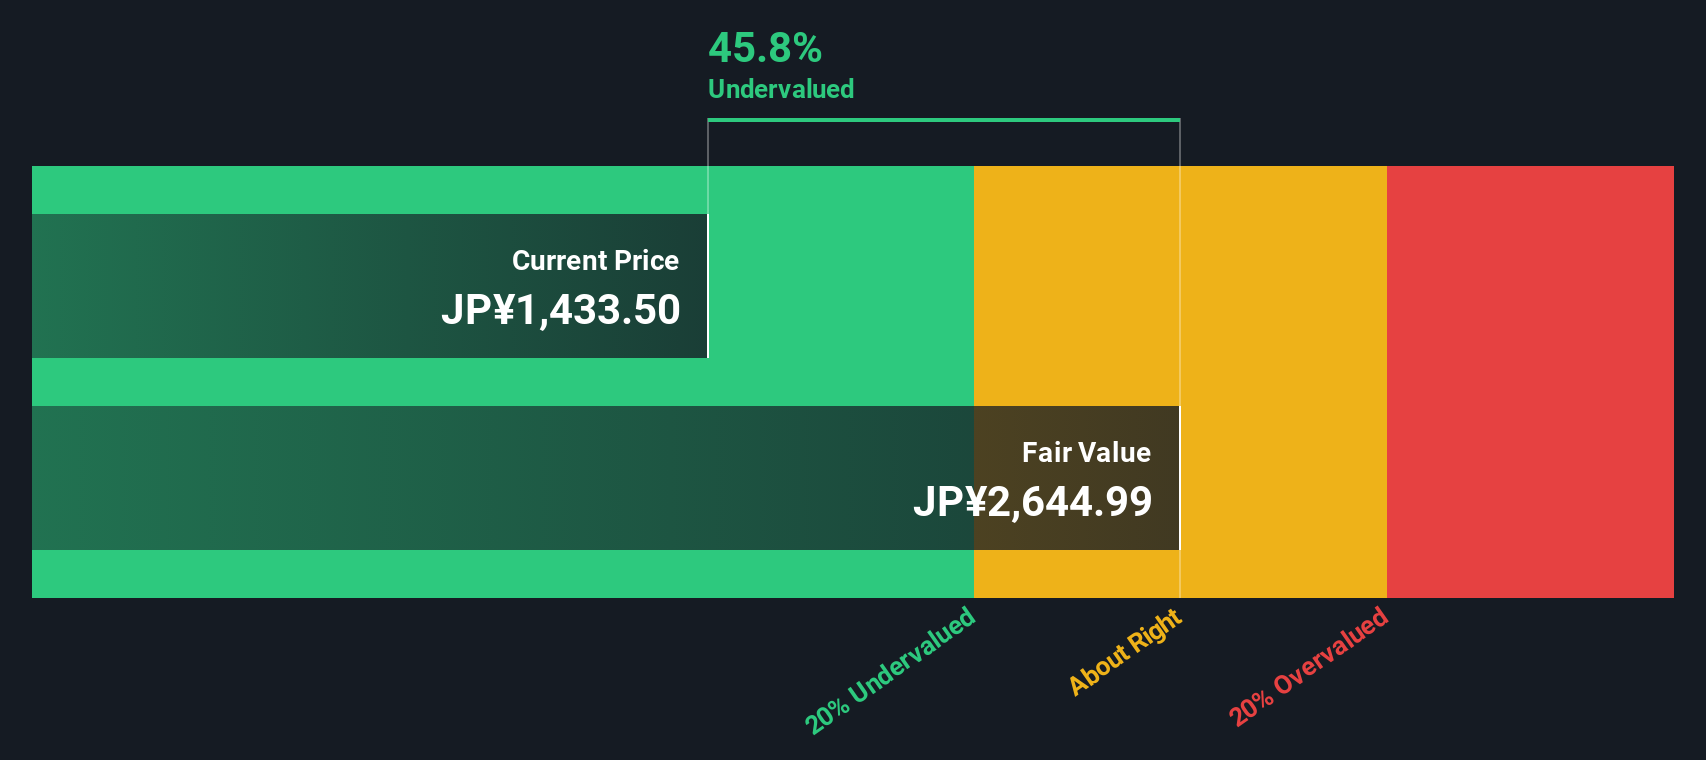
Build Your Own Panasonic Holdings Narrative
If you see things differently or want to dive into the numbers yourself, you can put together your own narrative in just a few minutes. Do it your way.
A great starting point for your Panasonic Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
Looking for more investment ideas?
Smart investing means being open to new opportunities. Don’t miss out on exciting trends and potential winners. Start your next search with the Simply Wall Street Screener:
- Capture high yields for your portfolio by tapping into dividend stocks with yields > 3% and finding companies consistently paying over 3%.
- Get ahead of the curve in artificial intelligence by scanning the market for tomorrow’s leaders among AI penny stocks.
- Boost your returns by targeting stocks that look undervalued based on their cash flows using the power of undervalued stocks based on cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
Druckenmiller says cheap money's days are numbered. Boring, self-funding companies could be the opportunity.
1311
DE
devon_jd150
Leverage on its own is close to useless as a screen right now, because so much corporate debt was termed out at 2 to 3% and has not repriced. A business at three times leverage with nothing due until 2031 is in a completely different position from the same ratio rolling next year. Screen on weighted average maturity and the schedule behind it.
LE
LeverageIsLovely
In my view, Insurance companies are best positioned for this.
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?
Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
32
KS

Kshitija Bhandaru
Kshitija (or Keisha) Bhandaru is an Equity Analyst at Simply Wall St and has over 6 years of experience in the finance industry and describes herself as a lifelong learner driven by her intellectual curiosity. She previously worked with Market Realist for 5 years as an Equity Analyst.
About TSE:6752
Panasonic Holdings
Develops, manufactures, sells, services, and supplies various electrical and electronic equipment and related products in Japan, the Americas, the United States, Europe, Asia, China, and internationally.
Flawless balance sheet with moderate growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
67 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
48 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
31 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
7 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
WO


woodworthfund on Kraft Heinz ·
Kraft Heinz (KHC): Less Drama, More Ketchup
Fair Value:US$3527.7% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on DICK'S Sporting Goods ·
DKS | DICK'S Sporting Goods: What They Said vs. What They Did
Fair Value:US$112.7710.2% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
PR


prajeeshprathap on Medpace Holdings ·
Why Medpace Outperforms Competitors in the Mid-Sized Biotech Niche
Fair Value:US$53614.6% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
355 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
203 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
228 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative
Trending Discussion


JO
johnk72 on Global X AI Infrastructure ETF ·
Great picks & shovels investment. I hold 3,000 units with a plan to hold until the end of 2028
2
|0