
Advertisement
We Think That There Are Issues Underlying Aurionpro Solutions' (NSE:AURIONPRO) Earnings
Despite announcing strong earnings, Aurionpro Solutions Limited's (NSE:AURIONPRO) stock was sluggish. Our analysis uncovered some concerning factors that we believe the market might be paying attention to.
View our latest analysis for Aurionpro Solutions
A Closer Look At Aurionpro Solutions' Earnings
As finance nerds would already know, the accrual ratio from cashflow is a key measure for assessing how well a company's free cash flow (FCF) matches its profit. The accrual ratio subtracts the FCF from the profit for a given period, and divides the result by the average operating assets of the company over that time. You could think of the accrual ratio from cashflow as the 'non-FCF profit ratio'.
That means a negative accrual ratio is a good thing, because it shows that the company is bringing in more free cash flow than its profit would suggest. While having an accrual ratio above zero is of little concern, we do think it's worth noting when a company has a relatively high accrual ratio. To quote a 2014 paper by Lewellen and Resutek, "firms with higher accruals tend to be less profitable in the future".
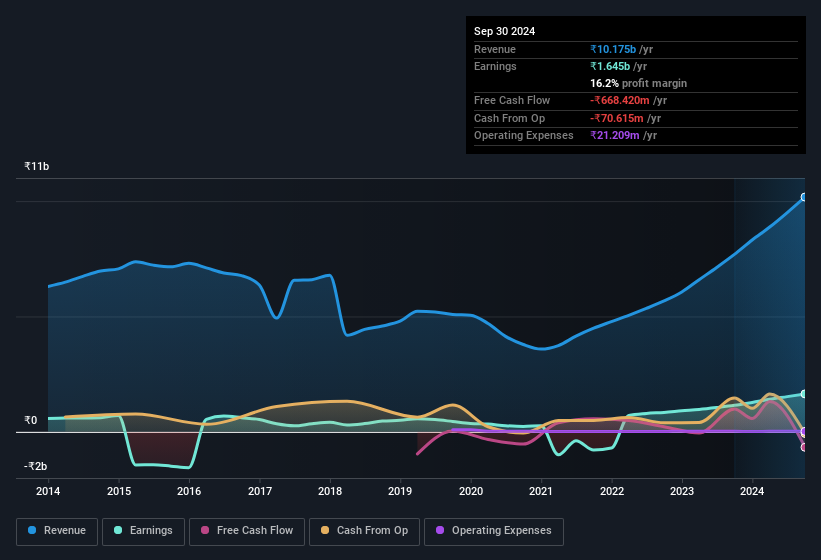
For the year to September 2024, Aurionpro Solutions had an accrual ratio of 0.27. Therefore, we know that it's free cashflow was significantly lower than its statutory profit, which is hardly a good thing. Even though it reported a profit of ₹1.65b, a look at free cash flow indicates it actually burnt through ₹668m in the last year. It's worth noting that Aurionpro Solutions generated positive FCF of ₹991m a year ago, so at least they've done it in the past. Notably, the company has issued new shares, thus diluting existing shareholders and reducing their share of future earnings.
Note: we always recommend investors check balance sheet strength. Click here to be taken to our balance sheet analysis of Aurionpro Solutions.
In order to understand the potential for per share returns, it is essential to consider how much a company is diluting shareholders. Aurionpro Solutions expanded the number of shares on issue by 8.5% over the last year. That means its earnings are split among a greater number of shares. To talk about net income, without noticing earnings per share, is to be distracted by the big numbers while ignoring the smaller numbers that talk to per share value. Check out Aurionpro Solutions' historical EPS growth by clicking on this link.
A Look At The Impact Of Aurionpro Solutions' Dilution On Its Earnings Per Share (EPS)
Aurionpro Solutions was losing money three years ago. The good news is that profit was up 43% in the last twelve months. But EPS was less impressive, up only 35% in that time. Therefore, the dilution is having a noteworthy influence on shareholder returns.
In the long term, earnings per share growth should beget share price growth. So it will certainly be a positive for shareholders if Aurionpro Solutions can grow EPS persistently. However, if its profit increases while its earnings per share stay flat (or even fall) then shareholders might not see much benefit. For that reason, you could say that EPS is more important that net income in the long run, assuming the goal is to assess whether a company's share price might grow.
Our Take On Aurionpro Solutions' Profit Performance
In conclusion, Aurionpro Solutions has weak cashflow relative to earnings, which indicates lower quality earnings, and the dilution means its earnings per share growth is weaker than its profit growth. Considering all this we'd argue Aurionpro Solutions' profits probably give an overly generous impression of its sustainable level of profitability. If you want to do dive deeper into Aurionpro Solutions, you'd also look into what risks it is currently facing. For example, Aurionpro Solutions has 2 warning signs (and 1 which doesn't sit too well with us) we think you should know about.
In this article we've looked at a number of factors that can impair the utility of profit numbers, and we've come away cautious. But there is always more to discover if you are capable of focussing your mind on minutiae. For example, many people consider a high return on equity as an indication of favorable business economics, while others like to 'follow the money' and search out stocks that insiders are buying. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
MI

The Foxhole
The world's in stitches over robots sprinting into walls. I still think they're the answer to our productivity problem.
87
DE
devon_jd150
What you have missed is that this event happened last year too. Last year the number was 21 seconds. This year it beat Bolt. That's 60% improvement in an year. Now extrapolate this in many axes of work that Robots can come and fill in. The physical productivity and AI boom is just starting.
LE
LeverageIsLovely
I can't pick a company. But I can pick a person. With no doubt that's Musk. Optimus for blue collar productivity increase and xAI for white collar productivity increase. Did anyone dabble with GrokBot here?
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
75
About NSEI:AURIONPRO
Aurionpro Solutions
Provides technology solutions in India, Asia-Pacific, and internationally.
Flawless balance sheet and fair value.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
42 followersusers have followed this narrative
0 commentsusers have commented on this narrative
12 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.4% undervalued
63 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.1% undervalued
68 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11634.8% undervalued
14 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on Science Applications International ·
SAIC | Science Applications International: What They Said vs. What They Did
Fair Value:US$119.247.5% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AN

Anthony_Lee on Lotus Technology ·
Tech and Tradition: Lotus Technology’s Compound Formula in Luxury EVs
Fair Value:US$2.5354.2% undervalued
2 followersusers have followed this narrative
5 commentsusers have commented on this narrative
1 likeusers have liked this narrative
EP

Epstein_Research on Dryden Gold ·
Dryden Gold continues to expand & de-risk its flagship Gold Rock project!
Fair Value:CA$173.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28022.3% undervalued
369 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9122.3% overvalued
214 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
JO


John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k73.1% undervalued
125 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative

