
Advertisement
For beginners, it can seem like a good idea (and an exciting prospect) to buy a company that tells a good story to investors, even if it completely lacks a track record of revenue and profit. Unfortunately, high risk investments often have little probability of ever paying off, and many investors pay a price to learn their lesson.
If, on the other hand, you like companies that have revenue, and even earn profits, then you may well be interested in Korvest (ASX:KOV). While profit is not necessarily a social good, it's easy to admire a business that can consistently produce it. Conversely, a loss-making company is yet to prove itself with profit, and eventually the sweet milk of external capital may run sour.
Check out our latest analysis for Korvest
Korvest's Improving Profits
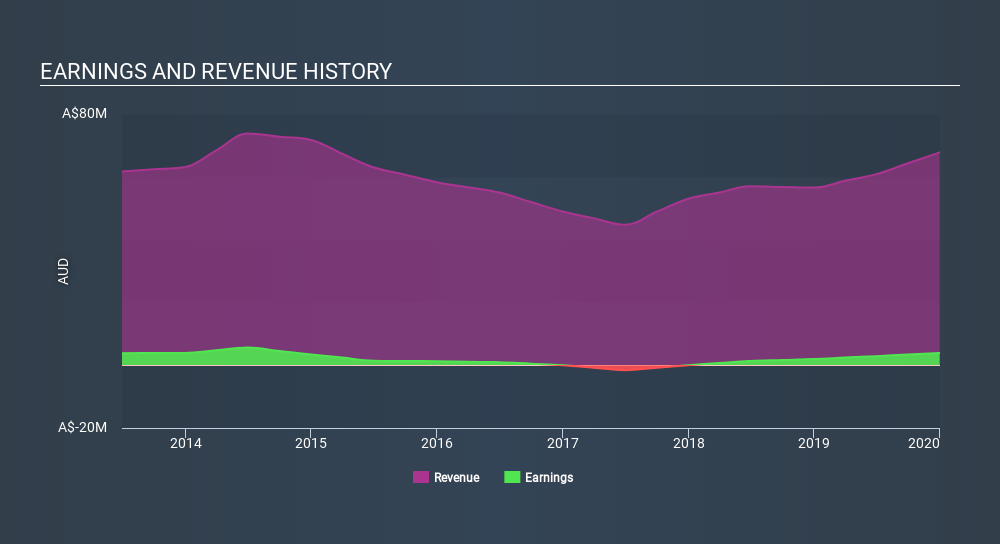
In the last three years Korvest's earnings per share took off like a rocket; fast, and from a low base. So the actual rate of growth doesn't tell us much. Thus, it makes sense to focus on more recent growth rates, instead. Like a firecracker arcing through the night sky, Korvest's EPS shot from AU$0.18 to AU$0.35, over the last year. You don't see 97% year-on-year growth like that, very often.
Careful consideration of revenue growth and earnings before interest and taxation (EBIT) margins can help inform a view on the sustainability of the recent profit growth. Korvest shareholders can take confidence from the fact that EBIT margins are up from 4.8% to 8.2%, and revenue is growing. Ticking those two boxes is a good sign of growth, in my book.
In the chart below, you can see how the company has grown earnings, and revenue, over time. Click on the chart to see the exact numbers.
Since Korvest is no giant, with a market capitalization of AU$44m, so you should definitely check its cash and debt before getting too excited about its prospects.
Are Korvest Insiders Aligned With All Shareholders?
Like standing at the lookout, surveying the horizon at sunrise, insider buying, for some investors, sparks joy. Because oftentimes, the purchase of stock is a sign that the buyer views it as undervalued. However, insiders are sometimes wrong, and we don't know the exact thinking behind their acquisitions.
The good news for Korvest shareholders is that no insiders reported selling shares in the last year. With that in mind, it's heartening that Andrew Stobart, the Independent Non-Executive Director of the company, paid AU$12k for shares at around AU$3.84 each.
Is Korvest Worth Keeping An Eye On?
Korvest's earnings per share have taken off like a rocket aimed right at the moon. If you're like me, you'll find it hard to ignore that sort of explosive EPS growth. And indeed, it could be a sign that the business is at an inflection point. If that's the case, you may regret neglecting to put Korvest on your watchlist. Don't forget that there may still be risks. For instance, we've identified 2 warning signs for Korvest that you should be aware of.
As a growth investor I do like to see insider buying. But Korvest isn't the only one. You can see a a free list of them here.
Please note the insider transactions discussed in this article refer to reportable transactions in the relevant jurisdiction.
If you’re looking to trade Korvest, open an account with the lowest-cost* platform trusted by professionals, Interactive Brokers. Their clients from over 200 countries and territories trade stocks, options, futures, forex, bonds and funds worldwide from a single integrated account.Promoted
Valuation is complex, but we're here to simplify it.
Discover if Korvest might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisThis article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
*Interactive Brokers Rated Lowest Cost Broker by StockBrokers.com Annual Online Review 2020
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com.
M

The Foxhole
When oil spikes, crude gets the attention. I think the boring refiner in the middle is where it gets interesting, and a record shows why.
78
marcus_reid
It's cyclical, but there's a hedging case. Worth being precise about it though. Refiners buy crude and sell products, so a crude spike alone hurts them. In 2008 oil hit 147 and refining margins collapsed. What they hedge is a product supply shock, not an oil one. This is what is happening now.
steve_investor
Goldman says the supply response has already started. Higher utilisation, yields shifted to diesel.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About ASX:KOV
Korvest
Manufactures and supplies cable and pipe support systems, and galvanising services in Australia.
Excellent balance sheet and fair value.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.574.9% undervalued
57 followersusers have followed this narrative
1 commentusers have commented on this narrative
12 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17019.6% undervalued
36 followersusers have followed this narrative
2 commentsusers have commented on this narrative
8 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.8% undervalued
29 followersusers have followed this narrative
2 commentsusers have commented on this narrative
15 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.3% undervalued
10 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
ZU

Zurboz on Microsoft ·
Microsoft will achieve a future PE ratio of 24.626979x by leveraging strong growth
Fair Value:US$561.0311.4% undervalued
17 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
DU
duarte_EM on Microsoft ·
Microsoft: Quality Compounder Buying the AI Backbone
Fair Value:US$671.4426.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
ZE
zeg0at on Tufton Assets ·
Tufton Assets: High-Yield, Deep-Value Shipping with a Built-In Exit 28% NAV Discount
Fair Value:US$1.442.1% undervalued
4 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28019.9% undervalued
374 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k72.6% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU
CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9118.3% overvalued
219 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
