
Advertisement
- Netherlands
- /
- Semiconductors
- /
- ENXTAM:ASML
We Think ASML Holding (AMS:ASML) Can Manage Its Debt With Ease
Howard Marks put it nicely when he said that, rather than worrying about share price volatility, 'The possibility of permanent loss is the risk I worry about... and every practical investor I know worries about.' So it seems the smart money knows that debt - which is usually involved in bankruptcies - is a very important factor, when you assess how risky a company is. We note that ASML Holding N.V. (AMS:ASML) does have debt on its balance sheet. But the more important question is: how much risk is that debt creating?
Why Does Debt Bring Risk?
Debt assists a business until the business has trouble paying it off, either with new capital or with free cash flow. Ultimately, if the company can't fulfill its legal obligations to repay debt, shareholders could walk away with nothing. However, a more frequent (but still costly) occurrence is where a company must issue shares at bargain-basement prices, permanently diluting shareholders, just to shore up its balance sheet. Of course, debt can be an important tool in businesses, particularly capital heavy businesses. When we think about a company's use of debt, we first look at cash and debt together.
View our latest analysis for ASML Holding
What Is ASML Holding's Net Debt?
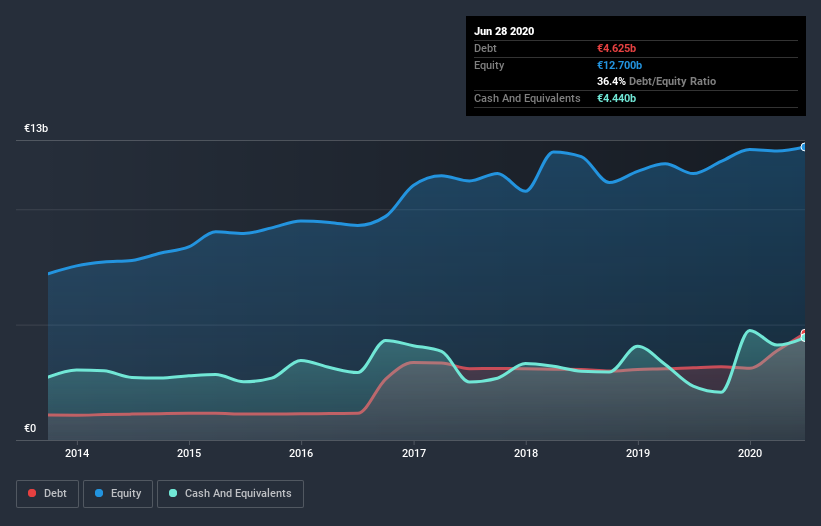
The image below, which you can click on for greater detail, shows that at June 2020 ASML Holding had debt of €4.41b, up from €3.13b in one year. But on the other hand it also has €4.44b in cash, leading to a €34.2m net cash position.
A Look At ASML Holding's Liabilities
We can see from the most recent balance sheet that ASML Holding had liabilities of €4.63b falling due within a year, and liabilities of €6.98b due beyond that. Offsetting this, it had €4.44b in cash and €3.46b in receivables that were due within 12 months. So its liabilities outweigh the sum of its cash and (near-term) receivables by €3.70b.
Since publicly traded ASML Holding shares are worth a very impressive total of €129.0b, it seems unlikely that this level of liabilities would be a major threat. But there are sufficient liabilities that we would certainly recommend shareholders continue to monitor the balance sheet, going forward. While it does have liabilities worth noting, ASML Holding also has more cash than debt, so we're pretty confident it can manage its debt safely.
On top of that, ASML Holding grew its EBIT by 34% over the last twelve months, and that growth will make it easier to handle its debt. There's no doubt that we learn most about debt from the balance sheet. But it is future earnings, more than anything, that will determine ASML Holding's ability to maintain a healthy balance sheet going forward. So if you're focused on the future you can check out this free report showing analyst profit forecasts.
Finally, a business needs free cash flow to pay off debt; accounting profits just don't cut it. ASML Holding may have net cash on the balance sheet, but it is still interesting to look at how well the business converts its earnings before interest and tax (EBIT) to free cash flow, because that will influence both its need for, and its capacity to manage debt. During the last three years, ASML Holding produced sturdy free cash flow equating to 63% of its EBIT, about what we'd expect. This free cash flow puts the company in a good position to pay down debt, when appropriate.
Summing up
We could understand if investors are concerned about ASML Holding's liabilities, but we can be reassured by the fact it has has net cash of €34.2m. And we liked the look of last year's 34% year-on-year EBIT growth. So we don't think ASML Holding's use of debt is risky. We'd be very excited to see if ASML Holding insiders have been snapping up shares. If you are too, then click on this link right now to take a (free) peek at our list of reported insider transactions.
If, after all that, you're more interested in a fast growing company with a rock-solid balance sheet, then check out our list of net cash growth stocks without delay.
When trading ASML Holding or any other investment, use the platform considered by many to be the Professional's Gateway to the Worlds Market, Interactive Brokers. You get the lowest-cost* trading on stocks, options, futures, forex, bonds and funds worldwide from a single integrated account. Promoted
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
*Interactive Brokers Rated Lowest Cost Broker by StockBrokers.com Annual Online Review 2020
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com.

 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
98
About ENXTAM:ASML
ASML Holding
Provides lithography solutions for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems.
Flawless balance sheet with high growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0615.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TO


Tokyo on Novo Nordisk ·
EU#2 - From Humble Beginnings to Global Powerhouse
Fair Value:DKK 851.0469.6% undervalued
75 followersusers have followed this narrative
11 commentsusers have commented on this narrative
25 likesusers have liked this narrative
HA


HarishPK on Zoetis ·
Decision Making Under Ambiguity – A Case Study on Expectations Investing
Fair Value:US$91.320.2% undervalued
3 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
RE


RedCandleRx on AppLovin ·
Why the Market Still Misprices AppLovin as Just a Gaming Network
Fair Value:US$50735.2% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Recently Updated Narratives
MA


MarkoVT on Alphabet ·
Mo' Money, Mo' Problems
Fair Value:US$443.3622.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on AutoZone ·
AZO | AutoZone, Inc.: What They Said vs. What They Did
Fair Value:US$2.83k2.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FR


FRAGMENTS on Five Point Holdings ·
Five Point Trades Around $5. It Has $2.34 Billion of Economic Capital. How Much Reaches One Share?
Fair Value:US$5.6613.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.4% undervalued
1495 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN
AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.9% undervalued
1650 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.0% undervalued
1670 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


JO

john_mwm1h on Hemab Therapeutics Holdings ·
One thing I find disappointing about this model is how rare disease communities can become attractive targets because development pathways may move faster with smaller patient populations. The marketing they run creates the impression that patients are constantly in danger or have no meaningful options without the newest treatment, which does not reflect every patient’s experience.I would bet many do not even realize that gene therapy for Glanzmann Thrombasthenia is getting closer to clinical trials, yet that research continues to struggle for funding while commercial drug developers can raise hundreds of millions of dollars.
0
|0