
Advertisement
- United States
- /
- Semiconductors
- /
- NasdaqGS:PLAB
Is Photronics, Inc. (NASDAQ:PLAB) Investing Your Capital Efficiently?
Want to participate in a short research study? Help shape the future of investing tools and you could win a $250 gift card!
Today we'll evaluate Photronics, Inc. (NASDAQ:PLAB) to determine whether it could have potential as an investment idea. Specifically, we're going to calculate its Return On Capital Employed (ROCE), in the hopes of getting some insight into the business.
First up, we'll look at what ROCE is and how we calculate it. Then we'll compare its ROCE to similar companies. Then we'll determine how its current liabilities are affecting its ROCE.
Return On Capital Employed (ROCE): What is it?
ROCE measures the 'return' (pre-tax profit) a company generates from capital employed in its business. In general, businesses with a higher ROCE are usually better quality. Overall, it is a valuable metric that has its flaws. Author Edwin Whiting says to be careful when comparing the ROCE of different businesses, since 'No two businesses are exactly alike.'
So, How Do We Calculate ROCE?
Analysts use this formula to calculate return on capital employed:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
Or for Photronics:
0.059 = US$56m ÷ (US$1.1b - US$139m) (Based on the trailing twelve months to April 2019.)
Therefore, Photronics has an ROCE of 5.9%.
See our latest analysis for Photronics
Is Photronics's ROCE Good?
ROCE can be useful when making comparisons, such as between similar companies. We can see Photronics's ROCE is meaningfully below the Semiconductor industry average of 11%. This performance could be negative if sustained, as it suggests the business may underperform its industry. Setting aside the industry comparison for now, Photronics's ROCE is mediocre in absolute terms, considering the risk of investing in stocks versus the safety of a bank account. Readers may find more attractive investment prospects elsewhere.
Photronics's current ROCE of 5.9% is lower than 3 years ago, when the company reported a 8.8% ROCE. This makes us wonder if the business is facing new challenges.
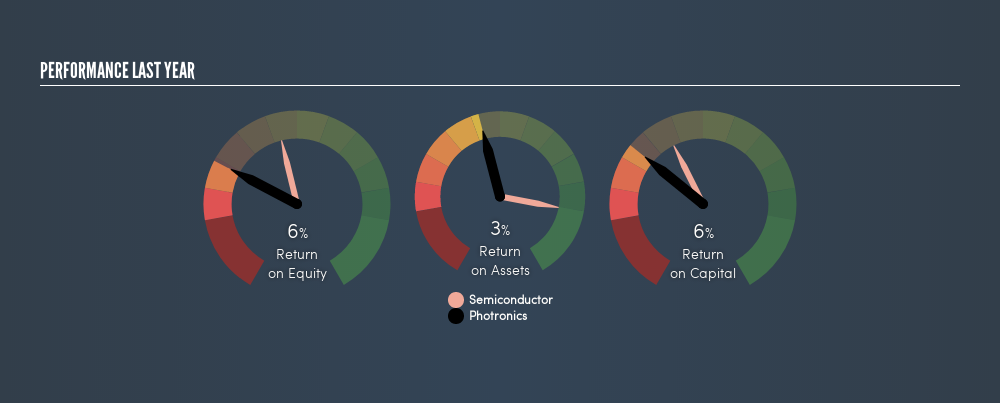
When considering ROCE, bear in mind that it reflects the past and does not necessarily predict the future. ROCE can be misleading for companies in cyclical industries, with returns looking impressive during the boom times, but very weak during the busts. This is because ROCE only looks at one year, instead of considering returns across a whole cycle. What happens in the future is pretty important for investors, so we have prepared a free report on analyst forecasts for Photronics.
What Are Current Liabilities, And How Do They Affect Photronics's ROCE?
Current liabilities are short term bills and invoices that need to be paid in 12 months or less. Due to the way ROCE is calculated, a high level of current liabilities makes a company look as though it has less capital employed, and thus can (sometimes unfairly) boost the ROCE. To counter this, investors can check if a company has high current liabilities relative to total assets.
Photronics has total liabilities of US$139m and total assets of US$1.1b. Therefore its current liabilities are equivalent to approximately 13% of its total assets. This very reasonable level of current liabilities would not boost the ROCE by much.
Our Take On Photronics's ROCE
That said, Photronics's ROCE is mediocre, there may be more attractive investments around. Of course, you might also be able to find a better stock than Photronics. So you may wish to see this free collection of other companies that have grown earnings strongly.
I will like Photronics better if I see some big insider buys. While we wait, check out this free list of growing companies with considerable, recent, insider buying.
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned. Thank you for reading.
M

The Foxhole
The most boring corner of the market just hit a 50-year low against stocks. History says that's when it's worth paying attention.

1212
p
pri_dlp7z
Supply-driven inflation breaks stocks and bonds at the same time. That is the one scenario commodities cover and nothing else does.
s
stefano_751bk
What the graphs says is that S&P 500 is just too expensive
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
74
About NasdaqGS:PLAB
Photronics
Engages in the manufacture and sale of photomask products and services in the United States, Taiwan, China, Korea, Europe, and internationally.
Flawless balance sheet and undervalued.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
72 followersusers have followed this narrative
1 commentusers have commented on this narrative
18 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4931.2% undervalued
13 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.7% undervalued
14 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
Recently Updated Narratives
HE


HedgeY on Salesforce ·
Salesforce: From Selling Seats to Selling Governed Work
Fair Value:US$294.9312.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FR


FRAGMENTS on Cable One ·
Cable One Trades in the Mid-$20s. The Network Still Makes Money. The Debt Decides Who Gets It.
Fair Value:US$17085.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FR

FRAGMENTS on Charter Communications ·
Charter Spent $80.6 Billion Buying Back Its Own Equity. The Stock Is Now in the Mid-$140s. What Is One Share Worth?
Fair Value:US$20224.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8323.9% undervalued
1389 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
JO


John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
131 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32720.9% undervalued
1608 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative


