
Advertisement
- Australia
- /
- Infrastructure
- /
- ASX:TCL
Here's Why We Don't Think Transurban Group's (ASX:TCL) Statutory Earnings Reflect Its Underlying Earnings Potential
Broadly speaking, profitable businesses are less risky than unprofitable ones. However, sometimes companies receive a one-off boost (or reduction) to their profit, and it's not always clear whether statutory profits are a good guide, going forward. This article will consider whether Transurban Group's (ASX:TCL) statutory profits are a good guide to its underlying earnings.
While Transurban Group was able to generate revenue of AU$4.17b in the last twelve months, we think its profit result of AU$171.0m was more important. In the chart below, you can see that its profit and revenue have both grown over the last three years, although its profit has slipped in the last twelve months.
See our latest analysis for Transurban Group
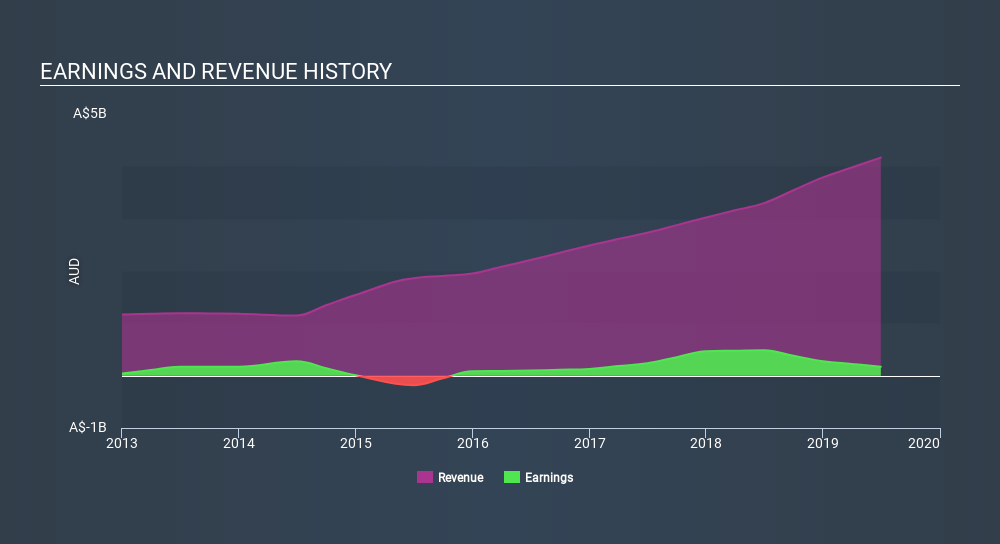
Not all profits are equal, and we can learn more about the nature of a company's past profitability by diving deeper into the financial statements. In this article we'll look at how Transurban Group is impacting shareholders by issuing new shares, as well as how unusual items have affected the income line. That might leave you wondering what analysts are forecasting in terms of future profitability. Luckily, you can click here to see an interactive graph depicting future profitability, based on their estimates.
To understand the value of a company's earnings growth, it is imperative to consider any dilution of shareholders' interests. As it happens, Transurban Group issued 21% more new shares over the last year. Therefore, each share now receives a smaller portion of profit. Per share metrics like EPS help us understand how much actual shareholders are benefitting from the company's profits, while the net income level gives us a better view of the company's absolute size. You can see a chart of Transurban Group's EPS by clicking here.
How Is Dilution Impacting Transurban Group's Earnings Per Share? (EPS)
Transurban Group has improved its profit over the last three years, with an annualized gain of 73% in that time. In comparison, earnings per share only gained 33% over the same period. Net profit actually dropped by 65% in the last year. Unfortunately for shareholders, though, the earnings per share result was even worse, declining 71%. So you can see that the dilution has had a bit of an impact on shareholders.Therefore, the dilution is having a noteworthy influence on shareholder returnsAnd so, you can see quite clearly that dilution is influencing shareholder earnings.
In the long term, if Transurban Group's earnings per share can increase, then the share price should too. But on the other hand, we'd be far less excited to learn profit (but not EPS) was improving. For the ordinary retail shareholder, EPS is a great measure to check your hypothetical "share" of the company's profit.
How Do Unusual Items Influence Profit?
Finally, we should also consider the fact that unusual items boosted Transurban Group's net profit by AU$203m over the last year. While we like to see profit increases, we tend to be a little more cautious when unusual items have made a big contribution. When we crunched the numbers on thousands of publicly listed companies, we found that a boost from unusual items in a given year is often not repeated the next year. And that's as you'd expect, given these boosts are described as 'unusual'. If Transurban Group doesn't see that contribution repeat, then all else being equal we'd expect its profit to drop over the current year.
Our Take On Transurban Group's Profit Performance
To sum it all up, Transurban Group got a nice boost to profit from unusual items; without that, its statutory results would have looked worse. And furthermore, it went and issued plenty of new shares, ensuring that each shareholder (who did not tip more money in) now owns a smaller proportion of the company. For the reasons mentioned above, we think that a perfunctory glance at Transurban Group's statutory profits might make it look better than it really is on an underlying level. Ultimately, this article has formed an opinion based on historical data. However, it can also be great to think about what analysts are forecasting for the future. At Simply Wall St, we have analyst estimates which you can view by clicking here.
In this article we've looked at a number of factors that can impair the utility of profit numbers, and we've come away cautious. But there is always more to discover if you are capable of focussing your mind on minutiae. Some people consider a high return on equity to be a good sign of a quality business. While it might take a little research on your behalf, you may find this free collection of companies boasting high return on equity, or this list of stocks that insiders are buying to be useful.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned.
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Thank you for reading.
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

711
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
10
About ASX:TCL
Transurban Group
Engages in the development, operation, and maintenance of toll roads in Australia and North America.
Solid track record with moderate growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
66 followersusers have followed this narrative
1 commentusers have commented on this narrative
17 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17016.9% undervalued
45 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8748.8% undervalued
46 followersusers have followed this narrative
2 commentsusers have commented on this narrative
18 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.0% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
TI

TimLee on Gold Li Holdings Berhad ·
Gold Li IPO: Johor Property Developer Builds Its Next Growth Chapter
Fair Value:RM 0.2363.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
QU


QuanD on Shopify ·
The Default Platform for Entrepreneurs that Keeps Compounding
Fair Value:US$210.4731.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO

John_Eric on Hamilton Lane ·
Analysts Cut Their Targets. The Co-Chairman Cut a Check.
Fair Value:US$290.3164.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28017.7% undervalued
374 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
129 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9119.0% overvalued
224 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
