
Advertisement
Did Changing Sentiment Drive Mondi's (LON:MNDI) Share Price Down By 25%?
Many investors define successful investing as beating the market average over the long term. But in any portfolio, there are likely to be some stocks that fall short of that benchmark. Unfortunately, that's been the case for longer term Mondi plc (LON:MNDI) shareholders, since the share price is down 25% in the last three years, falling well short of the market decline of around 5.6%. On the other hand, we note it's up 9.6% in about a month. However, this may be a matter of broader market optimism, since stocks are up 6.5% in the same time.
See our latest analysis for Mondi
There is no denying that markets are sometimes efficient, but prices do not always reflect underlying business performance. One way to examine how market sentiment has changed over time is to look at the interaction between a company's share price and its earnings per share (EPS).
Although the share price is down over three years, Mondi actually managed to grow EPS by 8.3% per year in that time. Given the share price reaction, one might suspect that EPS is not a good guide to the business performance during the period (perhaps due to a one-off loss or gain). Or else the company was over-hyped in the past, and so its growth has disappointed.
Since the change in EPS doesn't seem to correlate with the change in share price, it's worth taking a look at other metrics.
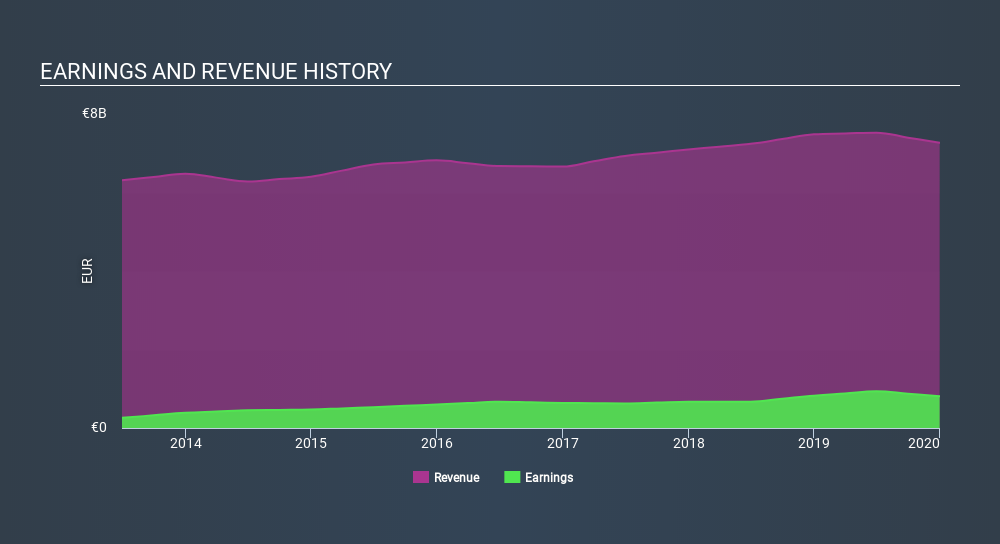
We note that the dividend seems healthy enough, so that probably doesn't explain the share price drop. It's good to see that Mondi has increased its revenue over the last three years. But it's not clear to us why the share price is down. It might be worth diving deeper into the fundamentals, lest an opportunity goes begging.
You can see below how earnings and revenue have changed over time (discover the exact values by clicking on the image).
Mondi is well known by investors, and plenty of clever analysts have tried to predict the future profit levels. So we recommend checking out this free report showing consensus forecasts
What About Dividends?
When looking at investment returns, it is important to consider the difference between total shareholder return (TSR) and share price return. The TSR incorporates the value of any spin-offs or discounted capital raisings, along with any dividends, based on the assumption that the dividends are reinvested. It's fair to say that the TSR gives a more complete picture for stocks that pay a dividend. In the case of Mondi, it has a TSR of -15% for the last 3 years. That exceeds its share price return that we previously mentioned. This is largely a result of its dividend payments!
A Different Perspective
While it's never nice to take a loss, Mondi shareholders can take comfort that , including dividends, their trailing twelve month loss of 6.8% wasn't as bad as the market loss of around 8.0%. Longer term investors wouldn't be so upset, since they would have made 4.9%, each year, over five years. In the best case scenario the last year is just a temporary blip on the journey to a brighter future. It's always interesting to track share price performance over the longer term. But to understand Mondi better, we need to consider many other factors. For example, we've discovered 2 warning signs for Mondi that you should be aware of before investing here.
We will like Mondi better if we see some big insider buys. While we wait, check out this free list of growing companies with considerable, recent, insider buying.
Please note, the market returns quoted in this article reflect the market weighted average returns of stocks that currently trade on GB exchanges.
Love or hate this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com.
This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned. Thank you for reading.

 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
88
About LSE:MNDI
Mondi
Engages in the manufacture and sale of packaging and paper solutions in Africa, Western Europe, Emerging Europe, North America, South America, Asia, and Australia.
Good value with reasonable growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0625.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TO


Tokyo on Novo Nordisk ·
EU#2 - From Humble Beginnings to Global Powerhouse
Fair Value:DKK 851.0469.4% undervalued
75 followersusers have followed this narrative
11 commentsusers have commented on this narrative
25 likesusers have liked this narrative
HA


HarishPK on Zoetis ·
Decision Making Under Ambiguity – A Case Study on Expectations Investing
Fair Value:US$91.321.9% undervalued
3 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
RE


RedCandleRx on AppLovin ·
Why the Market Still Misprices AppLovin as Just a Gaming Network
Fair Value:US$50734.9% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Polymetals Resources ·
Polymetals Resources, 338 g/t Silver A$28M Restart at A$414M NPV, The Numbers That Matter
Fair Value:AU$1.9756.9% undervalued
5 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
ON

Ontological on Hinge Health ·
Scaling Digital Musculoskeletal Care With Strong Growth and Margins, Hinge Health (HNGE)
Fair Value:US$145.0434.9% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HO

hongjuan_p6tor on DSC Holdings ·
DSC is not a second car dealer like Carvana but a used car dealer enabler
Fair Value:US$3.32103.9% overvalued
1 followerusers have followed this narrative
2 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.9% undervalued
1493 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.0% undervalued
1651 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.0% undervalued
1669 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


JO
jo_bill_Q on DSC Holdings ·
Good framing. DSC sells to dealers, not consumers — so watch dealer retention and revenue per dealer, not transaction volume. With 90%+ OS penetration and rising SKU complexity, the infrastructure layer looks like the best seat in the chain. I'm constructive, so long as data and AI revenue follows.
0
|0