
Last Update 04 Aug 26
Fair value Decreased 19%EAPI: Reset Expectations And Lower P E Multiple Could Support Rebound
Analysts have trimmed their fair value estimate for Euroapi, with the updated €1.20 target down from €1.48. This is aligned with recent Street research that reduced the official price target to €1.70 from €2.90 on revised expectations for growth, margins and future P/E levels.
Analyst Commentary
Recent commentary around Euroapi focuses on how the lower fair value and reduced official price target line up with updated expectations for growth, margins and future P/E levels. The latest move from JPMorgan to a €1.70 target reinforces that analysts are re-basing their views on the company.
Bullish Takeaways
- Bullish analysts keep a Neutral stance even after the cut to €1.70, which suggests they still see Euroapi as reasonably aligned with current fundamentals rather than severely mispriced.
- The new target appears to factor in more conservative growth and margin assumptions. This can reduce the risk of future valuation disappointment if execution is only steady rather than strong.
- Reset expectations on future P/E levels give Euroapi a lower bar to clear on earnings delivery, which could help sentiment if the company meets or modestly exceeds the revised outlook.
- The reduction in target from €2.90 to €1.70 provides investors with a refreshed reference point that may better reflect current information, instead of relying on older, less relevant assumptions.
Bearish Takeaways
- Bearish analysts see the cut from €2.90 to €1.70 as a sign that prior assumptions around Euroapi's growth and profitability were too optimistic, which can weigh on confidence in the stock.
- The lower target implies a more cautious stance on future P/E levels. This indicates concern that valuation could remain constrained if the company does not improve margins or growth trends.
- The size of the price target reduction highlights uncertainty around Euroapi's ability to execute on earlier plans. This may prompt some investors to demand a wider margin of safety.
- Maintaining only a Neutral rating, even after a large reset in expectations, signals that bearish analysts do not yet see a clear catalyst for a re-rating of the stock.
What's in the News for Euroapi
- No recent Euroapi specific news items are available from the sources provided as of 29 Jul 2026. Investors may wish to consult the latest company releases or exchange filings for current updates.
- Street research price targets, including the recent move to €1.70, remain the key reference point mentioned in available material for Euroapi at this time.
- In the absence of fresh headlines, the focus for Euroapi remains on how analysts are recalibrating fair value estimates and assumptions around growth, margins and future P/E levels.
Valuation Changes for Euroapi
- Fair Value has moved from €1.48 to €1.20, which is a reduction of about 19% in the reference valuation level for Euroapi.
- The Discount Rate has risen slightly from 6.47% to about 6.75%, which points to a modestly higher required return in the updated model.
- Revenue Growth has shifted from a decline of about 1.90% to an increase of about 1.29%, indicating a move from contraction to modest expected growth in € revenue.
- Profit Margin has moved from about 0.73% to about 14.34%, which represents a very large uplift in the assumed earnings margin on € sales.
- The Future P/E has fallen significantly from about 28.73x to about 1.15x, indicating a much lower valuation multiple being applied to Euroapi in the revised assumptions.
Key Takeaways
- Investments in capacity expansion, innovation, and premium CDMO projects position Euroapi for increased high-value API market share and resilient, higher-margin revenue growth.
- Structural cost reductions, site divestments, and regionalization trends are expected to strengthen profitability, operating efficiency, and long-term earnings stability.
- Intensifying competition, customer concentration, operational restructuring, and rising regulatory costs threaten revenue stability, margin improvement, and long-term growth prospects.
Catalysts
About Euroapi- Develops, manufactures, markets, and distributes active pharmaceutical ingredients and intermediates used in the formulation of medicines for human and veterinary use in France, Europe, Rest of Europe, North America, the Asia Pacific, and internationally.
- Significant investments in capacity expansion (e.g., Pristinamycin, PLLA, prostaglandin) and innovation (biotechnological processes, fermentation platform) are expected to enhance Euroapi's ability to supply high-value, complex APIs, positioning the company to capture a larger share of the growing pharmaceutical demand and support top-line revenue growth.
- The ongoing shift towards healthcare sovereignty and regionalization, reinforced by government subsidies like the €140 million IPCEI contract, is likely to drive higher plant utilization and long-term, stable demand for European-based API production, improving sales visibility and supporting sustained earnings growth.
- Increasing demand for APIs related to chronic diseases (e.g., opioids, prostaglandin, Vitamin B12) aligns Euroapi with expanding global pharma pipelines, creating opportunities for recurring revenues from both legacy and new drug launches.
- Structural cost reductions, improved operational efficiency, and divestment of unprofitable sites (e.g., Haverhill) are setting a foundation for sustained improvement in net margins and EBITDA, enhancing the company's ability to return to profitability.
- Strategic focus on high-margin, late-stage CDMO projects with blue-chip clients, along with rebuilding the commercial organization and moving away from legacy contracts, is expected to improve the mix and resilience of revenues, supporting margin expansion and higher long-term earnings quality.
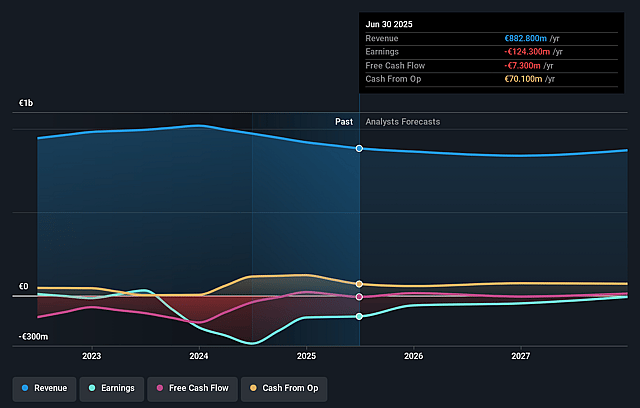
Euroapi Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Euroapi's revenue will grow by 1.3% annually over the next 3 years.
- Analysts are not forecasting that Euroapi will become profitable in next 3 years. To represent the Analyst Price Target as a Future PE Valuation we will estimate Euroapi's profit margin will increase from -40.8% to the average FR Pharmaceuticals industry of 14.3% in 3 years.
- If Euroapi's profit margin were to converge on the industry average, you could expect earnings to reach €118.5 million (and earnings per share of €1.27) by about August 2029, up from -€324.2 million today.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 1.1x on those 2029 earnings, up from -0.3x today. This future PE is lower than the current PE for the FR Pharmaceuticals industry at 18.7x.
- Analysts expect the number of shares outstanding to decline by 0.54% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 6.75%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Persistent pricing pressure and heightened competition from low-cost Asian producers in key segments such as Vitamin B12 could continue to erode revenue and compress margins, especially if price wars intensify and process improvements do not deliver sufficient cost advantage.
- Customer concentration risk remains elevated, with Sanofi still representing a major share of sales, and legacy Sanofi-inherited contracts within the CDMO business now in decline; further attrition, consolidation, or client loss could lead to significant revenue decreases and increased earnings volatility.
- Euroapi's CDMO segment is experiencing right-sizing and project attritions, with a delay in rebuilding commercial momentum and an overall decrease in RFPs market-wide; this could hinder revenue growth and limit the company's ability to offset declining legacy business in the medium to long term.
- Execution risks tied to ongoing restructuring (e.g., FOCUS-27), large-scale CapEx, and technology/process upgrades could result in disruption, cost overruns, or recurring operational lapses, weighing on productivity and thus limiting improvements in net margins and long-term earnings.
- Increased regulatory scrutiny, environmental requirements, and sustainability standards across Europe may drive up Euroapi's operating costs faster than cost-saving initiatives or market growth can compensate, ultimately impacting margin competitiveness and net income over the long term.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of €1.2 for Euroapi based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €1.7, and the most bearish reporting a price target of just €0.7.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be €825.8 million, earnings will come to €118.5 million, and it would be trading on a PE ratio of 1.1x, assuming you use a discount rate of 6.8%.
- Given the current share price of €0.96, the analyst price target of €1.2 is 20.2% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Euroapi?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Rising Regulatory And Geopolitical Risks Will Undermine API Profits
View narrative
Green Chemistry And Domestic Sourcing Will Unlock Secular Demand
View narrative