
Advertisement
Earnings Update: Here's Why Analysts Just Lifted Their Methode Electronics, Inc. (NYSE:MEI) Price Target To US$10.25
As you might know, Methode Electronics, Inc. (NYSE:MEI) just kicked off its latest first-quarter results with some very strong numbers. Methode Electronics outperformed estimates, with revenues of US$241m beating estimates by 11%. Statutory losses were US$0.29, 28% smaller thanthe analysts expected. This is an important time for investors, as they can track a company's performance in its report, look at what experts are forecasting for next year, and see if there has been any change to expectations for the business. So we gathered the latest post-earnings forecasts to see what estimates suggest is in store for next year.
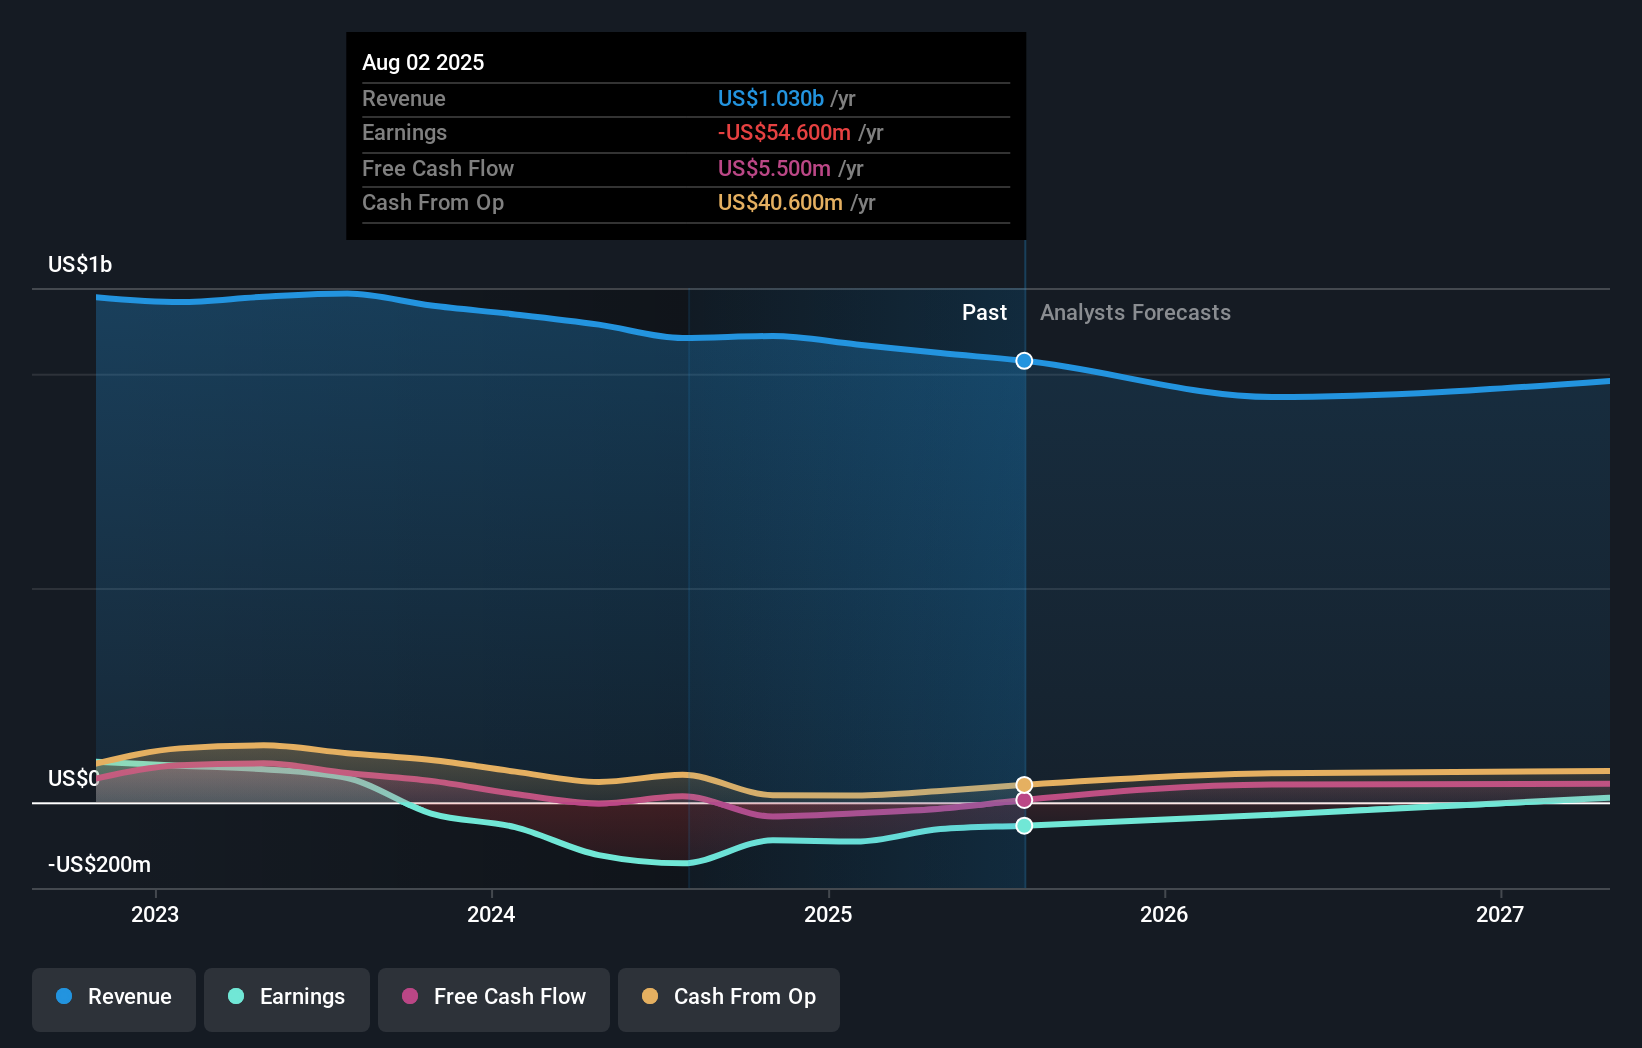
Following the recent earnings report, the consensus from three analysts covering Methode Electronics is for revenues of US$945.6m in 2026. This implies a definite 8.2% decline in revenue compared to the last 12 months. Per-share statutory losses are expected to explode, reaching US$0.82 per share. Yet prior to the latest earnings, the analysts had been anticipated revenues of US$925.9m and earnings per share (EPS) of US$0.67 in 2026. While they've upgraded their revenue numbers for next year, the consensus also expects losses to increase, perhaps due to the investments required to fund that growth In any event, it's not clear that these new estimates are particularly bullish.
See our latest analysis for Methode Electronics
It will come as a surprise to learn that the consensus price target rose 7.9% to US$10.25, with the analysts clearly more interested in growing revenue, even as losses intensify. It could also be instructive to look at the range of analyst estimates, to evaluate how different the outlier opinions are from the mean. The most optimistic Methode Electronics analyst has a price target of US$12.00 per share, while the most pessimistic values it at US$8.50. There are definitely some different views on the stock, but the range of estimates is not wide enough as to imply that the situation is unforecastable, in our view.
Taking a look at the bigger picture now, one of the ways we can understand these forecasts is to see how they compare to both past performance and industry growth estimates. These estimates imply that revenue is expected to slow, with a forecast annualised decline of 11% by the end of 2026. This indicates a significant reduction from annual growth of 0.4% over the last five years. Compare this with our data, which suggests that other companies in the same industry are, in aggregate, expected to see their revenue grow 8.4% per year. So although its revenues are forecast to shrink, this cloud does not come with a silver lining - Methode Electronics is expected to lag the wider industry.
The Bottom Line
The biggest low-light for us was that the forecasts for Methode Electronics dropped from profits to a loss next year. They also upgraded their revenue estimates for next year, even though it is expected to grow slower than the wider industry. There was also a nice increase in the price target, with the analysts clearly feeling that the intrinsic value of the business is improving.
With that in mind, we wouldn't be too quick to come to a conclusion on Methode Electronics. Long-term earnings power is much more important than next year's profits. We have estimates - from multiple Methode Electronics analysts - going out to 2027, and you can see them free on our platform here.
Even so, be aware that Methode Electronics is showing 1 warning sign in our investment analysis , you should know about...
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
Robinhood now earns more from people betting on outcomes than companies. Is that a flaw or a feature?
67
p
pri_dlp7z
Q2 had the World cup. Not a signal. Robinhood has hardly moved this year.
a
arjun_dyig0
Contrarian take: Gambling can only expand as much. If you are keeping a close eye in the image represented here, crypto volumes have shifted to events.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
42
About NYSE:MEI
Methode Electronics
Designs, engineers, manufacture, and sells mechatronic products in North America, Europe, the Middle East, Africa, and Asia.
Undervalued with mediocre balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
67 followersusers have followed this narrative
1 commentusers have commented on this narrative
17 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17016.9% undervalued
49 followersusers have followed this narrative
3 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8748.8% undervalued
50 followersusers have followed this narrative
2 commentsusers have commented on this narrative
20 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.0% undervalued
12 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on West Red Lake Gold Mines ·
This Junior Gold Mine Just Hit Commercial Production, 120k oz Roadmap at $7,000 Gold
Fair Value:CA$4.3679.8% undervalued
30 followersusers have followed this narrative
8 commentsusers have commented on this narrative
1 likeusers have liked this narrative
JA

jackhopwood on Boom Logistics ·
A Cash Generative Buyback Compounder, Largely Undervalued.
Fair Value:AU$4.550.2% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO

John_Eric on GXO Logistics ·
Seventeen Analysts, 20,000 Robots—and the $450 Million Ghost
Fair Value:US$44.279.1% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8323.9% undervalued
1380 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
OS

oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28017.7% undervalued
373 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
131 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
Trending Discussion
DA
daniel_uvswg on Oncolytics Biotech ·
Thank you for the detailed backdown regarding this company and its stock. I think given the data and looking to be optimistic I would likely believe that it's no unbelievable to assume that the stock price could go to the ~$3 mark. Even at that level it's not a bad deal especially coming from sub $1 stock at the moment.
1
|0