
Advertisement
- United States
- /
- Chemicals
- /
- NYSE:ESI
Earnings Beat: Element Solutions Inc Just Beat Analyst Forecasts, And Analysts Have Been Updating Their Models
As you might know, Element Solutions Inc (NYSE:ESI) recently reported its first-quarter numbers. Revenues of US$575m fell slightly short of expectations, but earnings were a definite bright spot, with statutory per-share profits of US$0.23 an impressive 44% ahead of estimates. Following the result, the analysts have updated their earnings model, and it would be good to know whether they think there's been a strong change in the company's prospects, or if it's business as usual. So we gathered the latest post-earnings forecasts to see what estimates suggest is in store for next year.
Check out our latest analysis for Element Solutions
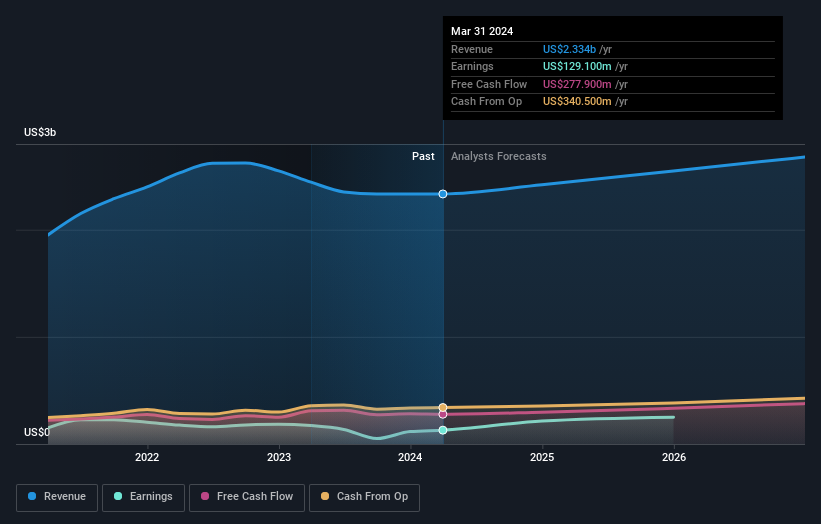
Taking into account the latest results, the current consensus from Element Solutions' eight analysts is for revenues of US$2.42b in 2024. This would reflect a credible 3.7% increase on its revenue over the past 12 months. Per-share earnings are expected to step up 13% to US$0.60. In the lead-up to this report, the analysts had been modelling revenues of US$2.44b and earnings per share (EPS) of US$0.80 in 2024. So there's definitely been a decline in sentiment after the latest results, noting the pretty serious reduction to new EPS forecasts.
The consensus price target held steady at US$27.78, with the analysts seemingly voting that their lower forecast earnings are not expected to lead to a lower stock price in the foreseeable future. It could also be instructive to look at the range of analyst estimates, to evaluate how different the outlier opinions are from the mean. Currently, the most bullish analyst values Element Solutions at US$30.00 per share, while the most bearish prices it at US$25.00. Still, with such a tight range of estimates, it suggeststhe analysts have a pretty good idea of what they think the company is worth.
Another way we can view these estimates is in the context of the bigger picture, such as how the forecasts stack up against past performance, and whether forecasts are more or less bullish relative to other companies in the industry. We would highlight that Element Solutions' revenue growth is expected to slow, with the forecast 4.9% annualised growth rate until the end of 2024 being well below the historical 7.2% p.a. growth over the last five years. Compare this to the 126 other companies in this industry with analyst coverage, which are forecast to grow their revenue at 4.8% per year. So it's pretty clear that, while Element Solutions' revenue growth is expected to slow, it's expected to grow roughly in line with the industry.
The Bottom Line
The biggest concern is that the analysts reduced their earnings per share estimates, suggesting business headwinds could lay ahead for Element Solutions. Happily, there were no real changes to revenue forecasts, with the business still expected to grow in line with the overall industry. There was no real change to the consensus price target, suggesting that the intrinsic value of the business has not undergone any major changes with the latest estimates.
With that said, the long-term trajectory of the company's earnings is a lot more important than next year. At Simply Wall St, we have a full range of analyst estimates for Element Solutions going out to 2026, and you can see them free on our platform here..
You still need to take note of risks, for example - Element Solutions has 2 warning signs (and 1 which is a bit unpleasant) we think you should know about.
Valuation is complex, but we're here to simplify it.
Discover if Element Solutions might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
What's Uber worth in a world where nobody drives for it? Possibly more, not less.

98
f
frank_ub3n0
The aggregator argument works when supply is fragmented and interchangeable. Uber's driver-side power comes from millions of individuals with no coordination and no bargaining position. With autonomous fleet, the inverse. It will be a nightmare for Uber,
a
alberto_gztam
Car manufactoring and rides are two very different bussinesses. Uber can choose the best car make, that not necesarily would be tesla. Also, most countries and cities are not keen on just letring driverless taxis around... regulations block this for now.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About NYSE:ESI
Element Solutions
Operates as a specialty chemicals technology company in the United States, China, and internationally.
Fair value with moderate growth potential.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.574.9% undervalued
59 followersusers have followed this narrative
1 commentusers have commented on this narrative
13 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17019.6% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.8% undervalued
35 followersusers have followed this narrative
2 commentsusers have commented on this narrative
16 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.3% undervalued
10 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
DU

duarte_EM on Taiwan Semiconductor Manufacturing ·
TSMC — The Factory the AI World Runs On (Fair Value ~$400, sized for Taiwan risk)
Fair Value:US$116.49256.7% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
DU

duarte_EM on JPMorgan Chase ·
JPMorgan — Best-in-Class Bank, Buy It in the Downturns
Fair Value:US$370.393.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
DU

duarte_EM on Eli Lilly ·
Eli Lilly — Leader of the GLP-1 Revolution, but Priced for Success
Fair Value:US$1.43k19.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28019.9% undervalued
373 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k72.6% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9118.3% overvalued
221 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
