
Advertisement
- Japan
- /
- Interactive Media and Services
- /
- TSE:3981
Beaglee's (TSE:3981) Dividend Will Be Increased To ¥17.00
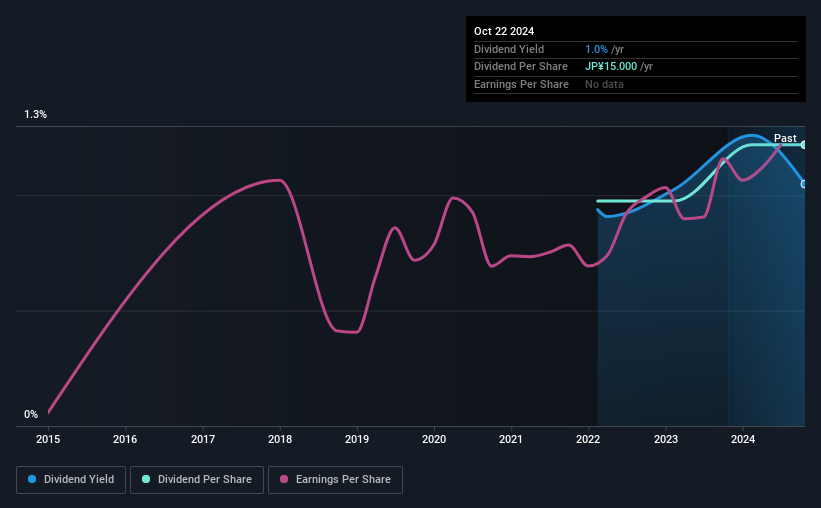
The board of Beaglee Inc. (TSE:3981) has announced that the dividend on 31st of March will be increased to ¥17.00, which will be 13% higher than last year's payment of ¥15.00 which covered the same period. Although the dividend is now higher, the yield is only 1.0%, which is below the industry average.
Check out our latest analysis for Beaglee
Beaglee's Projected Earnings Seem Likely To Cover Future Distributions
Even a low dividend yield can be attractive if it is sustained for years on end. However, Beaglee's earnings easily cover the dividend. This means that most of what the business earns is being used to help it grow.
Looking forward, earnings per share could rise by 7.6% over the next year if the trend from the last few years continues. If the dividend continues along recent trends, we estimate the payout ratio will be 13%, which is in the range that makes us comfortable with the sustainability of the dividend.
Beaglee Is Still Building Its Track Record
The dividend has been pretty stable looking back, but the company hasn't been paying one for very long. This makes it tough to judge how it would fare through a full economic cycle. Since 2021, the annual payment back then was ¥12.00, compared to the most recent full-year payment of ¥15.00. This works out to be a compound annual growth rate (CAGR) of approximately 7.7% a year over that time. Beaglee has a nice track record of dividend growth but we would wait until we see a longer track record before getting too confident.
Beaglee Could Grow Its Dividend
Investors could be attracted to the stock based on the quality of its payment history. Beaglee has impressed us by growing EPS at 7.6% per year over the past five years. A low payout ratio and decent growth suggests that the company is reinvesting well, and it also has plenty of room to increase the dividend over time.
In Summary
In summary, it's great to see that the company can raise the dividend and keep it in a sustainable range. The payout ratio looks good, but unfortunately the company's dividend track record isn't stellar. The payment isn't stellar, but it could make a decent addition to a dividend portfolio.
Investors generally tend to favour companies with a consistent, stable dividend policy as opposed to those operating an irregular one. At the same time, there are other factors our readers should be conscious of before pouring capital into a stock. For instance, we've picked out 1 warning sign for Beaglee that investors should take into consideration. If you are a dividend investor, you might also want to look at our curated list of high yield dividend stocks.
Valuation is complex, but we're here to simplify it.
Discover if Beaglee might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
The US closed a loophole that helped Temu and Shein. Does that put local retailers back on a level playing field?
57
Jake_Merritt
The domestic retailers competing most directly with Temu and Shein are themselves among the largest importers in the country.
a
arjun_dyig0
Zooming out and looking at the effect of these regulatory changes last year, US manufacturing - production is at a seven year high. But employment is down. It's is interesting,
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
11
About TSE:3981
Beaglee
Engages in platform and contents businesses in Japan.
Flawless balance sheet and good value.
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2540.0% undervalued
188 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4937.2% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
11 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k16.9% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2537.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
JO


John_Eric on Booking Holdings ·
The Float Illusion: How Booking Holdings Almost Talked Me Into a $130-a-Share Mistake
Fair Value:US$322.3445.9% undervalued
3 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on Kroger ·
KR | The Kroger Co.: What They Said vs. What They Did
Fair Value:US$65.6513.3% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HU

Hunter_Z on Zenta Group ·
ZTG: Why the Short Thesis Is Becoming Harder to Ignore
Fair Value:US$0.1670.0% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1418 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.3% undervalued
1603 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.0% undervalued
1629 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative

