- Italy
- /
- Consumer Finance
- /
- BIT:MOL
Moltiply Group (BIT:MOL) Reports 40% Sales Growth And 7% Net Income Increase

Moltiply Group (BIT:MOL) recently announced robust financial results for the first half of 2025, showcasing a rise in sales and net income. Despite this positive performance, the company's stock experienced a 2% decline over the last month. This price movement contrasts with broad market trends, as major indexes like the Dow Jones and S&P 500 reached record highs due to inflation data and expectations of interest rate cuts by the Federal Reserve. The release of impressive earnings did not appear to significantly impact Moltiply's share price, suggesting other factors or investor sentiment might have influenced the outcome.
Every company has risks, and we've spotted 1 risk for Moltiply Group you should know about.
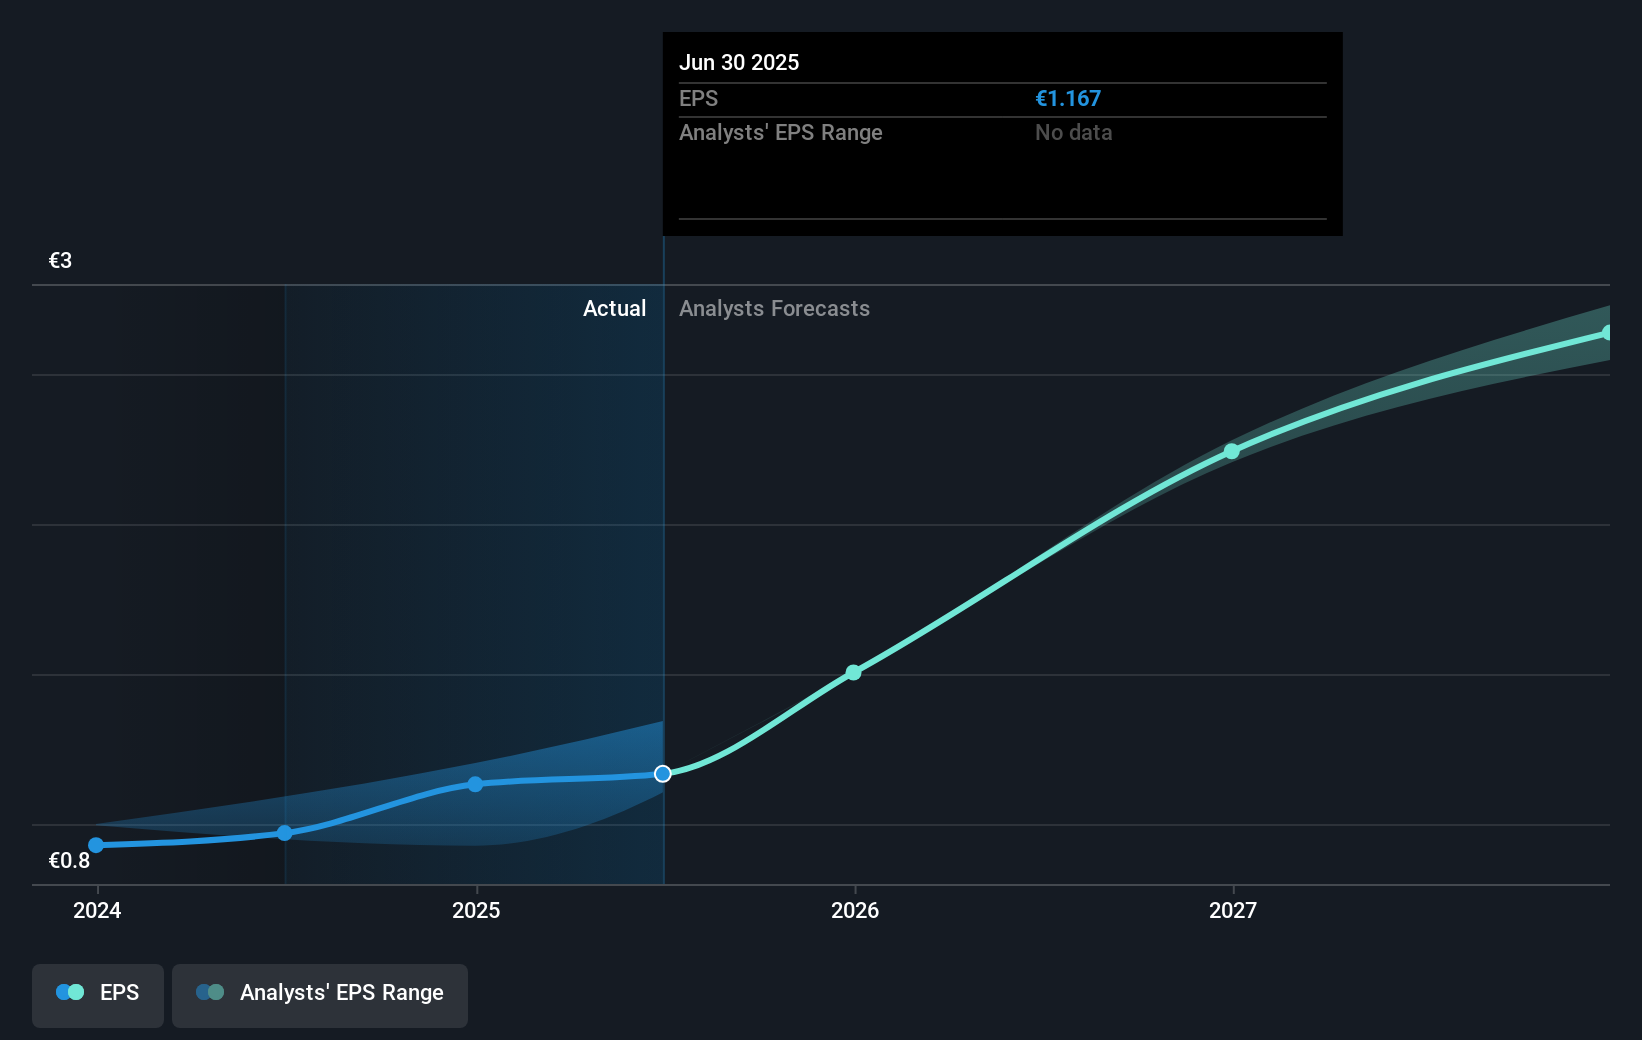
The recent financial results presented by Moltiply Group, highlighting increases in sales and net income, suggest a strong operational performance. However, despite these positive developments, the stock has seen a 2% decline over the past month. This discrepancy may indicate that factors such as investor sentiment or external market conditions might be impacting the stock's performance more than the recent earnings figures. Considering the broader market's upward movement, reflected in record highs for the Dow Jones and S&P 500, Moltiply's short-term price dip is especially intriguing and raises questions about long-term value perceptions among investors.
Over a longer period, the company's total shareholder return was a robust 75.10% over five years, demonstrating strong growth and value creation for shareholders. In contrast, over the past year, Moltiply's performance exceeded the Italian Consumer Finance industry, which returned 24.7%, signaling a competitive edge in a challenging sector.
The current share price of €41.60 stands significantly below the analyst consensus price target of €57.33, suggesting a potential upside based on projected revenue and profitability improvements. Analysts foresee annual revenue growth of 21.0%, driving earnings up to €112.8 million by 2028. Assuming these estimates, the company's valuation, with a price-to-earnings ratio projected to decrease from 38.8x to 26.3x by 2028, appears reasonable if market conditions align with expectations. Nevertheless, potential risks could alter these forecasts, such as changes in Google's practices affecting the company's margins or broader economic influences impacting growth sectors, including the E-Commerce Price Comparison and BPO divisions.
Evaluate Moltiply Group's prospects by accessing our earnings growth report.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Druckenmiller says cheap money's days are numbered. Boring, self-funding companies could be the opportunity.
Leverage on its own is close to useless as a screen right now, because so much corporate debt was termed out at 2 to 3% and has not repriced. A business at three times leverage with nothing due until 2031 is in a completely different position from the same ratio rolling next year. Screen on weighted average maturity and the schedule behind it.
In my view, Insurance companies are best positioned for this.
 Mitchell Lawler
Which payment stocks actually get paid?

About BIT:MOL
Moltiply Group
Operates as a holding company in the financial services industry in Italy, Germany, and internationally.
Reasonable growth potential with mediocre balance sheet.
Market Insights


Weekly Picks


The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market


The $135 Billion Bet That Should Make Every Shareholder Nervous


The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era

Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Recently Updated Narratives


Kraft Heinz (KHC): Less Drama, More Ketchup


DKS | DICK'S Sporting Goods: What They Said vs. What They Did


Why Medpace Outperforms Competitors in the Mid-Sized Biotech Niche
Popular Narratives


The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.

A wonderful business at reasonable price.


